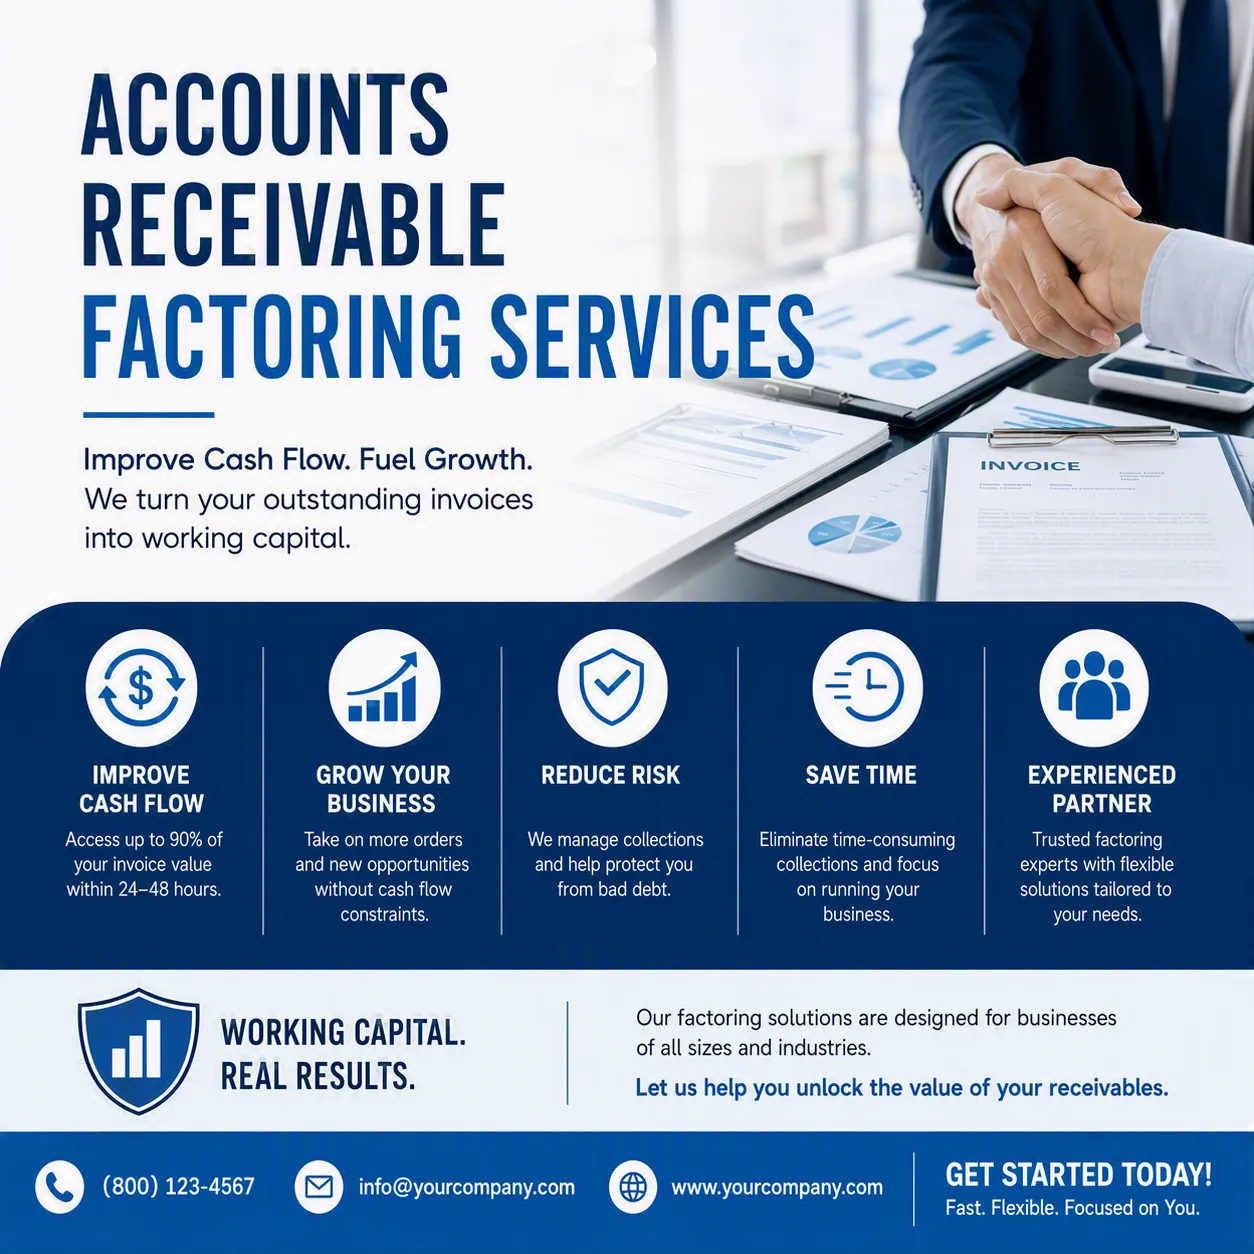

Maintaining a steady cash flow is one of the ongoing challenges businesses face, particularly when customers take weeks or months to pay outstanding invoices. Even a profitable company can experience working-capital pressure when a significant portion of its revenue is tied up in accounts receivable. Accounts Receivable Factoring Services offer one potential way for businesses to access funds tied to eligible invoices before customers make their payments.
Understanding how factoring works, its potential advantages, and the considerations involved can help business owners determine whether this type of financing fits their financial needs.
What Are Accounts Receivable Factoring Services?
Accounts receivable factoring is a form of business financing in which a company sells or assigns eligible invoices to a factoring company in exchange for an advance. The factoring provider generally provides a percentage of the invoice value upfront, while the remaining amount, less applicable fees, is paid according to the agreement after the customer settles the invoice.
Factoring is different from a conventional business loan because the financing is connected to the company's receivables rather than being structured solely around borrowing against future income.
The exact structure can vary between providers and agreements. Businesses should review the terms carefully to understand advance rates, fees, collection responsibilities, eligibility requirements, and any recourse provisions.
How Does Invoice Factoring Work?
The process typically begins when a business provides goods or services to a customer and issues an invoice. Instead of waiting until the invoice's due date, the business submits eligible invoices to a factoring provider.
After reviewing the invoices and customer accounts, the factoring company may advance an agreed percentage of the invoice value. The customer subsequently pays the invoice according to the original payment terms.
Once payment is received, the factoring provider releases the remaining balance to the business after deducting the applicable factoring fees and other charges specified in the agreement.
This structure can provide businesses with faster access to working capital without requiring them to wait for customers to pay according to longer invoice cycles.
Potential Benefits of Accounts Receivable Factoring
One of the main reasons companies consider Accounts Receivable Factoring Services is improved access to working capital.
Instead of having funds tied up in unpaid invoices, a business may be able to use a portion of its receivables to support ongoing operations. This can be particularly relevant for businesses that need cash to cover payroll, inventory purchases, operating expenses, or new projects while waiting for customers to pay.
Factoring can also provide a financing option for businesses that may not fit traditional lending criteria. Depending on the provider, underwriting may place significant emphasis on the creditworthiness of the business's customers and the quality of its receivables.
What Businesses Should Consider
Factoring is not free financing, so businesses should carefully compare the costs with the value of faster access to capital. Fees can vary depending on factors such as invoice volume, customer payment history, industry, payment terms, and the specific agreement.
Businesses should also understand whether the arrangement is with recourse or without recourse. Under a recourse arrangement, the business may remain responsible for certain unpaid invoices if the customer fails to pay. The exact obligations depend on the contract.
Another consideration is customer communication. Some factoring arrangements involve the provider handling collections or communicating directly with customers. Businesses should understand how this process will work before entering into an agreement.
Choosing a Factoring Provider
When researching Accounts Receivable Factoring Services, businesses should evaluate providers based on their experience, transparency, funding structure, fees, customer service, and contract terms.
It is useful to ask about advance rates, processing times, minimum invoice volumes, termination provisions, reserve requirements, and how disputes or overdue invoices are handled.
Comparing multiple providers can help a business identify an arrangement that aligns with its cash-flow requirements and operating model.
Final Thoughts
Accounts receivable can represent a significant source of working capital, but waiting for customers to pay invoices can create cash-flow challenges. Accounts Receivable Factoring Services provide businesses with an alternative way to access funds associated with eligible outstanding invoices.
For companies considering factoring, understanding the costs, contractual responsibilities, customer implications, and financing structure is essential. With careful evaluation and a suitable provider, invoice factoring can become one component of a broader working-capital strategy designed to help businesses manage cash flow more efficiently.



















Sign in to leave a comment.