
Honestly, back when I first started looking into financing multi-family properties, I was completely overwhelmed. I remember sitting at my kitchen table late at night, staring at a stack of loan disclosures, a half-empty mug of lukewarm coffee, and feeling this deep pit in my stomach. The terminology alone felt like it was written in another language, and every lender I talked to gave me a slightly different pitch.
It is easy to assume that borrowing money for a multi-unit property is pretty much the same across the board, but that is a mistake that gets expensive fast. I’ve seen this happen a lot, where buyers jump into a deal thinking an Apartment building loan works just like a standard commercial mortgage, only to hit a wall midway through underwriting. The terms shift, the income requirements get tighter, and suddenly you are scrambling to save a deal that should have been straightforward.
The truth is, while an apartment building loan technically falls under the general umbrella of commercial real estate financing, the way lenders treat it—and the way you need to prepare for it—is totally different. Getting it wrong doesn't just cost you time; it can drain your reserves before you even get the keys. Let’s talk through how this actually works on the ground, so you do not have to learn the hard way like I did.
What Is an Apartment Building Loan, Really?
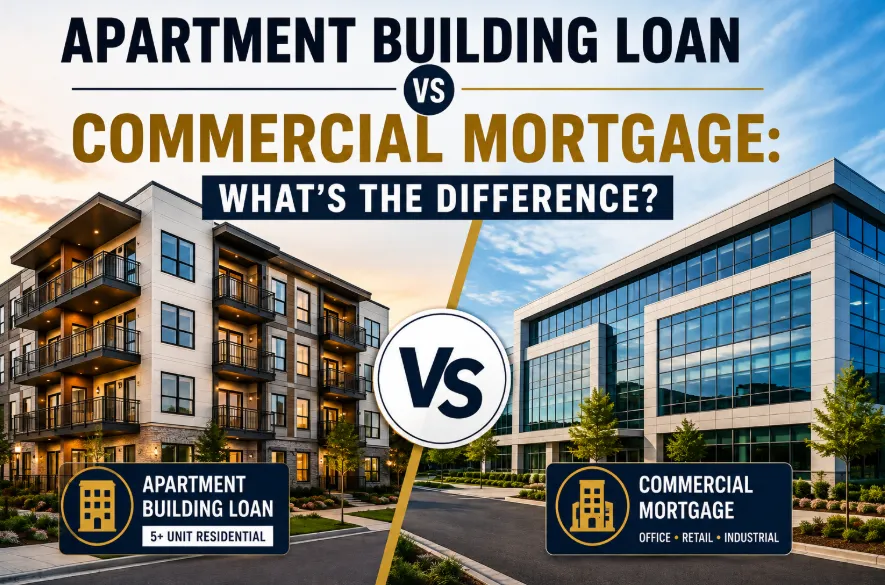
At its core, an apartment building loan is specifically designed for residential properties with five or more units. Anything with four units or fewer falls under residential financing, where you can still get conventional 30-year fixed mortgages. Once you hit five units, you step into commercial territory, even though everyday people are living there.
That shift changes everything about how lenders evaluate you. With a standard house, the bank looks primarily at your personal income, your credit score, and your debt-to-income ratio. But when you apply for an apartment building loan, the property itself takes center stage. Lenders care far more about the Net Operating Income (NOI) generated by tenant leases than they do about your personal day-job salary.
In my experience, this catches first-time investors completely off guard. You might have flawless personal credit and a great high-paying job, but if the building’s rent roll is weak or operating expenses are out of control, the bank will turn down your apartment building loan application without hesitating.
How Commercial Mortgages Differ Across Other Property Types
A general commercial mortgage covers a massive range of real estate—retail strip centers, industrial warehouses, office buildings, mixed-use properties, and medical spaces. Because these properties house businesses rather than residents, the underlying risk model for the lender is completely different from a standard residential multi-unit setup.
Here is where the key distinctions come up:
- Lease structures: Commercial leases are often multi-year agreements (5, 10, or even 15 years) with triple-net terms where the tenant pays taxes, insurance, and maintenance. Apartment leases are typically 12-month agreements where you absorb maintenance spikes.
- Vacancy sensitivity: If a single tenant leaves an office building, you might lose 50% or 100% of your cash flow overnight. With a 20-unit building, one tenant moving out drops your gross revenue by only 5%, making multi-family properties inherently lower risk.
- Economic resilience: People can close a store or downsize an office during a downturn, but they always need a place to live. That basic reality makes securing an apartment building loan slightly more forgiving during economic shifts than retail or office financing.
Comparing Key Financing Factors
| Feature | Apartment Building Loan | General Commercial Mortgage |
|---|---|---|
| Primary Property Type | 5+ unit residential complexes | Office, retail, industrial, mixed-use |
| Typical Lease Length | 12 months | 3 to 10+ years |
| Underwriting Focus | Rent roll, occupancy rates, NOI | Tenant creditworthiness, business viability |
| LTV Ratios | Typically 70% to 80% | Typically 65% to 75% |
| Lender Options | Fannie Mae, Freddie Mac, HUD, Banks | Commercial Banks, Life Insurance Co., CMBS |
Why the Lender Type Matters More Than You Think
When you begin looking for money to buy a property, you soon learn that the lender is as important as the interest rate. Some banks only move if the paperwork is spotless. They want clean tax forms, strong net income, and lots of cash sitting in accounts.
Real estate is rarely that neat. A lot of deals involve units that need repairs, or they have been empty for a while.
This is where an asset based mortgage lender can really matter. Most people do not think about it, but traditional lenders often spend a lot of time digging through your old tax records. An asset based mortgage lender looks more at what the property is worth and what it can earn. If the numbers work and there is enough equity, they can push the deal through faster.
I have personally used this kind of financing when a traditional bank would not approve the purchase. The seller had messy records, and that was the end of it for that bank. With the asset based loan, the interest can be higher at first, but you can still close, handle the repairs, and then refinance later into a more stable long term loan.
If your tax returns do not show the full picture, going with an asset based mortgage lender instead of a strict bank can help you reach the closing table. Even if you plan to hold the property for a long time, this type of financing can act as the short bridge you need while you renovate units.
Underwriting Realities: What Lenders ACTUALLY Look At
Lenders evaluate every apartment building loan through a very specific metric called the Debt Service Coverage Ratio (DSCR). If you remember nothing else from this guide, remember DSCR.
Why Most Investors Get Their Expenses Wrong
Most buyers look at the seller's financial statement and take it at face value. Big mistake. Sellers routinely leave out realistic maintenance costs, self-manage to hide property management fees, or underestimate property tax reassessments that happen after the sale. And trust me, that gets expensive fast.
Lenders will apply their own underwriting stress tests. They will assume a minimum vacancy rate (usually 5% to 10%) even if your building is 100% occupied today. They will also plug in a mandatory management fee (typically 8% to 10%) even if you plan to manage it yourself. If the numbers don't pass their stress test, your loan amount gets cut, and you are forced to bring more cash to the closing table.
Step-by-Step: Securing Your Financing Without the Drama
- Clean up the rent roll: Ensure all current leases are signed, deposits are documented, and tenant payment histories are clear.
- Order a realistic appraisal and inspection: Do not skip physical inspections; deferred maintenance on HVAC units or roofs can destroy your cash flow assumptions.
- Build your Lender Package: Prepare two years of property P&L statements, current rent rolls, photos, market rent comparisons, and your personal financial statement.
- Evaluate non-recourse options: Try to secure non-recourse debt where possible so your personal assets outside the property are protected if things go sideways.
Frequently Asked Questions
What is the minimum down payment for an apartment building loan?
Most lenders require between 20% and 30% down depending on the property's DSCR and location.
How does a 4-unit property differ from a 5-unit property for financing?
Four units qualify for residential 30-year fixed mortgages, while five units require commercial underwriting.
What is DSCR and why do lenders care so much about it?
DSCR measures cash flow against debt obligations to ensure the property earns enough to pay its mortgage.
Can I get an apartment building loan with bad personal credit?
Yes, especially if you work with lenders focused primarily on property value and real estate assets.
What is non-recourse debt in multi-family real estate?
Non-recourse loans prevent the lender from seizing your personal assets if you default, taking only the property.
How long does it take to close an apartment building loan?
Commercial bank loans take 45 to 60 days, while specialized government loans can take 90 to 180 days.
Why do commercial mortgages have balloon payments?
Lenders use balloon structures to reset interest rates and re-evaluate property risk every 5 to 10 years.
Are interest rates higher for apartment loans than home loans?
Generally yes, commercial interest rates run slightly higher than standard residential home loans.
What expenses can I deduct from Net Operating Income?
You deduct property taxes, insurance, repairs, utilities, management fees, and routine maintenance costs.
Can I use rental income to qualify for the mortgage?
Yes, property rent roll is the primary income source lenders evaluate during commercial underwriting.
Educational & Planning Resources
- Fannie Mae Multifamily Guide: Excellent overview of standard underwriting guidelines for 5+ unit properties.
- Local Property Assessor Portfolios: Crucial for calculating prospective property tax increases post-sale.
- Commercial Loan Calculators: Useful for testing different DSCR scenarios and balloon payment amortization schedules.
Final Thoughts
Financing multi-family real estate is easily one of the most effective ways to build real long-term wealth, but you have to treat it like a business from day one. Respect the difference between residential promises and commercial underwriting realities. Run your numbers conservatively, plan for unexpected repairs, and work with lenders who actually understand the multi-family space. Once you get that first deal under your belt and establish a track record, every deal after that gets a whole lot easier.











Sign in to leave a comment.