

There’s something about getting out on the water that makes everyday problems feel a little farther away.
The engine starts. The boat leaves the dock. The shoreline gets smaller in the distance. Suddenly, it's just you, the open water, and a day that feels like it was made for relaxing.
But before you untie the lines and head out, there’s one part of boat ownership that deserves attention long before you reach the water: insurance.
Boat insurance isn't exactly the most exciting part of owning a vessel. Nobody buys a boat because they're excited about reading policy documents. Yet understanding your coverage before something goes wrong can make an enormous difference when an accident, theft, storm, or unexpected mishap turns a great day into a very expensive one.
So, what does boat insurance actually cover? What isn't covered? Do you really need a separate policy? And how much protection is enough?
Let's take a closer look.
Why Boat Insurance Matters More Than Many Owners Expect
It’s easy to think, “My boat is just sitting at the marina most of the time. What could happen?”
Quite a lot, actually.
Boats face risks both on and off the water. A collision can damage the hull. A storm can cause serious structural damage. Someone could steal the vessel—or valuable equipment from it. A mechanical problem could leave you stranded. And an accident involving another person or boat could potentially leave you responsible for significant costs.
Then there are the less obvious risks.
Your boat may be damaged while being transported to a lake. Someone may get injured while aboard. A dock could be damaged during an accident. Fishing equipment, electronics, safety equipment, or other personal property could be lost.
Boat ownership comes with more exposure than simply protecting the vessel itself.
That's where the right coverage can help.
What Is Boat Insurance?
Boat insurance is designed to provide financial protection against certain risks associated with owning and operating a boat.
The exact protection depends on the policy, insurer, coverage limits, deductibles, exclusions, and endorsements you choose. That's important because two boat owners can have policies that look similar on the surface but provide very different protection.
A typical policy may include several types of coverage.
Physical Damage Coverage
This generally helps protect the boat itself against covered losses.
Depending on the policy, covered causes of damage may include things such as:
- Collision
- Theft
- Fire
- Certain storms
- Vandalism
- Other specified risks
The details matter. Don't assume that every type of damage is automatically covered simply because you have boat insurance.
Always check the actual terms of your policy.
Liability Coverage: The Part You Don't Want to Ignore
Imagine you're pulling away from the dock and accidentally hit another boat.
Nobody intended for it to happen. But now there's property damage—and potentially injuries.
This is where liability coverage can become extremely important.
Liability protection may help cover certain costs you're legally responsible for following a covered accident, subject to the policy's terms and limits.
And it isn't only about collisions.
If a passenger is injured on your boat, for example, you could potentially face medical expenses or a liability claim.
The boat itself may be expensive, but liability exposure can sometimes become an even bigger financial concern.
Does Homeowners Insurance Cover Your Boat?
This is one of the most common questions boat owners ask.
The answer isn't simply yes or no.
Some homeowners policies may provide limited coverage for certain boats or boating-related losses, but that coverage can have restrictions, exclusions, or relatively low limits. It may not provide the broad protection you expect for a larger or more valuable vessel.
That's why assuming your homeowners policy automatically covers everything can be risky.
If you own a boat, review your existing homeowners coverage carefully and ask specifically about the vessel, its equipment, liability exposure, storage, transportation, and use.
You may discover that separate boat coverage makes more sense.
What About the Things You Keep on the Boat?
Your boat isn't usually empty.
You might have fishing gear, life jackets, portable electronics, water sports equipment, tools, coolers, navigation equipment, and other belongings aboard.
Depending on the policy, some of these items may be covered—but coverage can vary considerably.
Certain personal property may have limits or exclusions. Some specialized equipment may require additional coverage.
So before assuming that everything on your boat is protected, make an inventory.
Take photographs.
Keep receipts for expensive equipment when possible.
Document serial numbers for valuable electronics or gear.
If you ever need to file a claim, having this information readily available can make the process much easier.
What Is Usually Not Covered?
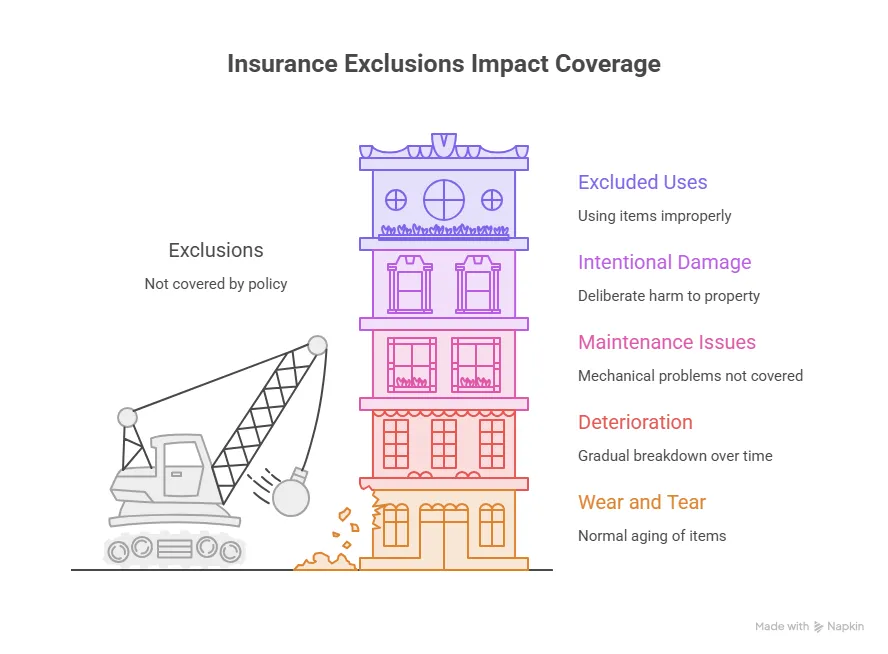
This is where reading the fine print becomes especially important.
Insurance isn't designed to cover every possible situation.
Depending on the policy, exclusions can involve things such as:
- Normal wear and tear
- Gradual deterioration
- Certain mechanical or maintenance issues
- Intentional damage
- Unapproved or excluded uses
- Certain types of racing or competition
- Damage occurring outside specified navigation areas
Policies differ, so never rely solely on a general list of exclusions.
Your actual contract controls.
If you're unsure about something, ask before you need to make a claim—not after.
Agreed Value vs. Actual Cash Value
One of the more important decisions when insuring a boat involves how the vessel's value is handled after a covered loss.
Two terms you'll commonly encounter are agreed value and actual cash value.
Agreed Value
With an agreed-value approach, you and the insurer establish a value for the boat when the policy is written, subject to the policy's terms.
This can provide greater certainty about how a covered total loss may be valued.
Actual Cash Value
Actual cash value generally takes depreciation into account when determining the value of a covered loss.
That can mean the amount paid after a total loss may be lower than what you originally paid for the boat.
Which option is appropriate depends on your circumstances, the boat's value, the policy terms, and your budget.
It's a detail worth discussing rather than overlooking.
Don't Forget About Towing and Emergency Assistance
Nobody plans on breaking down in the middle of the lake.
That's precisely why it happens at the worst possible time.
Emergency assistance or towing coverage may help with certain situations such as breakdowns, fuel delivery, jump starts, or towing, depending on the policy.
For boaters who regularly travel away from the marina, this type of protection can be particularly useful.
Think of it as the boating equivalent of roadside assistance—except your “road” happens to be water.
What Happens to Your Boat During a Storm?
Weather is one of the realities every boat owner has to respect.
Strong winds, lightning, heavy rain, flooding, and other severe conditions can cause substantial damage.
Whether a particular storm-related loss is covered depends on the policy language and circumstances.
Your responsibility doesn't end with insurance, either.
Proper preparation matters.
That can include:
- Securing the boat properly
- Following marina storage requirements
- Removing or securing loose equipment
- Checking bilge systems
- Following recommended winterization procedures
- Moving the boat when appropriate
- Following local weather and boating advisories
Good insurance and good maintenance work together.
How Much Boat Insurance Do You Need?
There isn't one magic coverage amount that works for every boat owner.
Consider the value of your vessel first.
Then look beyond the boat itself.
Ask yourself:
What would happen financially if I were responsible for damaging someone else's property?
What if someone were seriously injured while aboard?
What if my boat were stolen?
What if a storm caused significant damage?
What would replacing my equipment cost?
Your answers can help you identify where your biggest financial exposures are.
An experienced insurance professional can also help you evaluate coverage limits, deductibles, and optional protections based on your boat and how you use it.
Your Boat's Value Isn't the Only Thing That Matters
A $15,000 fishing boat and a $150,000 yacht obviously have different insurance needs.
But the boat's purchase price isn't the only factor.
Insurers may consider details such as:
- Boat type
- Length
- Age
- Value
- Engine type
- Horsepower
- Storage location
- Where you operate the boat
- How frequently you use it
- Your boating experience
- Safety features
- Claims history
- Intended use
That's why getting a personalized quote is usually more useful than trying to estimate your premium from someone else's experience.
Who Is Allowed to Operate Your Boat?
Here's something boat owners sometimes overlook: who actually drives the boat?
Maybe it's just you.
Maybe your spouse uses it.
Maybe your adult children take it out.
Maybe friends occasionally borrow it.
Don't assume everyone is automatically covered in every circumstance.
Policy language can address permitted operators, household members, inexperienced operators, and other situations differently.
If other people regularly operate your boat, tell your insurance professional.
It's much better to clarify the situation before an accident occurs.
What About Your Boat Trailer?
Your boat may spend plenty of time on the road rather than the water.
That means your trailer deserves attention too.
Coverage for the trailer can vary depending on the policy and circumstances. Don't assume the trailer is automatically covered simply because the boat is insured.
If you transport your boat regularly, ask specifically how your policy treats the trailer and what happens if the boat or trailer is damaged during transportation.
A Quick Pre-Launch Insurance Checklist
Before you head out for the season, take a few minutes to review your policy.
Check your coverage limits
Are they still appropriate for your boat and financial situation?
Review your deductible
Would you comfortably be able to pay it after a covered loss?
Confirm your navigation area
Does your policy cover where you actually plan to use the boat?
Review your equipment coverage
Have you added expensive electronics, fishing gear, or other equipment?
Check your listed operators
Has anyone new started using the boat?
Review your boat's value
If the vessel has been upgraded or significantly modified, make sure your policy reflects the change where appropriate.
Look at your liability protection
Don't focus only on protecting the boat. Your potential liability exposure deserves serious consideration.
What If You Only Use Your Boat During Summer?
Seasonal use doesn't mean seasonal risk.
Your boat still needs protection while it's sitting in storage.
In fact, theft, fire, vandalism, severe weather, and other losses can happen while a vessel is parked at a marina, stored at home, or sitting in a storage facility.
Your policy may address these situations differently depending on where and how the boat is stored.
Before putting the boat away for the off-season, confirm that your coverage remains appropriate.
How to Choose the Right Insurance Provider
Shopping for boat insurance isn't just about finding the lowest number on a quote.
A policy that costs slightly less but leaves important gaps in protection may not be a bargain when you actually need it.
Look for an Insurance Company or insurance professional that is willing to explain:
- What is covered
- What isn't covered
- Your deductibles
- Liability limits
- How claims are handled
- Available optional coverage
- Navigation restrictions
- Storage requirements
- How the boat's value is determined
You shouldn't need a law degree to understand your insurance.
If an explanation leaves you more confused than when you started, keep asking questions.
Looking for Boat Insurance Near Madison Heights?
If you're searching for Boat Insurance near Madison Heights, Michigan, start by finding an insurance professional who understands your actual boating situation.
Tell them where you keep your boat, where you typically use it, how often you take it out, who operates it, and what equipment you carry.
Those details can make a difference when determining what coverage may be appropriate.
Local guidance can also be useful because your insurance needs aren't necessarily identical to those of a boat owner several states away.
Don't Wait Until the First Accident to Read Your Policy
Here's perhaps the most important boating insurance advice of all:
Read your policy before you need it.
Nobody wants to imagine a collision, theft, storm, or injury ruining their boating season. But understanding your coverage when everything is going well gives you an advantage.
You'll know your limits.
You'll know your deductible.
You'll understand the major exclusions.
And you'll know who to call if something goes wrong.
That's a much better position to be in than opening your policy for the first time after an accident.
Final Thoughts: Protect the Good Days on the Water
Boat insurance may never be the reason you bought your boat.
You bought it for the weekends. The fishing trips. The sunsets. The family memories. The quiet mornings and the days when the water seems to stretch forever.
Insurance exists for the part nobody wants to think about.
A good policy won't prevent an accident from happening, stop a storm from rolling in, or guarantee that nothing will go wrong. What it can do is help reduce the financial impact of certain covered losses and give you a clearer path forward when the unexpected happens.
Before your next trip, take a few minutes to review your coverage. Ask questions. Check your limits. Make sure your policy matches the boat you own and the way you actually use it.
Then, once the paperwork is handled, get back to what owning a boat is really about:
getting out on the water and enjoying the ride.





















Sign in to leave a comment.