
Your yield really comes from three moving parts. Purchase price sets the floor, the rent sets the ceiling, and the empty weeks in between decide how close you get to it. Towers that score on all of them are not random, so it pays to know what they have in common before you sign anything.
Business Bay apartments cover two different worlds on price. Buy in an older inland tower and AED 1,400 a square foot gets you in. The branded canal addresses want nearer AED 3,500. That gap sets your return long before a tenant matters.
Canal-Facing Premium: What The Water View Adds
Start with the view, since it moves the rent more than anything else on the spec sheet. A one-bed facing inland leased for about AED 95K a year in early 2026. Put the same box on the canal or a high floor and it pulled AED 115K to 130K.
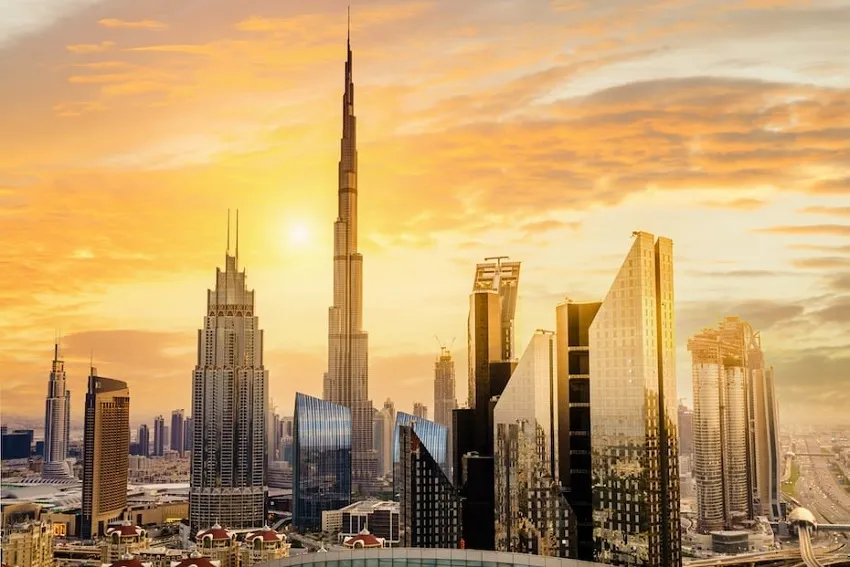
So the water is worth a 20 to 35 percent bump in rent. Step up to the branded towers on Marasi Drive, the Dorchester and Bugatti addresses, and that canal-facing premium widens to around 35 percent over plain stock on the same block.
The catch sits on the buy side. Canal-front and branded units cost more per foot going in, so run the yield on your real purchase number rather than the glossy rent figure before the promenade wins you over.
Tenant Demographic: Who Signs The Lease
Stable rent is really a question of who signs the lease, and the tenant demographic here leans corporate. A DIFC banker, a consultant billing hours on Sheikh Zayed Road, an engineer at one of the tech firms nearby: that is the renter pool, and what they want is a furnished one-bed close to the office.
That crowd signs annual contracts and stays put. They renew without drama, they pay on the first, and nobody talks a decent unit down to nothing.
Two-beds tilt the mix toward sharers and young families, trading a touch of yield for longer stays. That is often the smarter swap if re-letting every twelve months sounds like a chore.
Occupancy Rate Drivers: Why Vacancy Stays Under 6 Percent
Empty weeks drain yield faster than a soft rent does, so the occupancy rate drivers deserve real weight. Early 2026 had vacancy under 6 percent across the district. Put plainly, 94 units in every 100 were paying their way.
Location carries most of that. DIFC is seven minutes away, Downtown under five, and that short commute keeps a steady queue of professionals competing for the same units.
Management does the rest. A tower with quick maintenance and tidy common areas keeps tenants renewing, while a neglected one leaks them to the building next door no matter how good the view is.
Short lets are the wildcard. Slap a DTCM holiday-home permit on a canal unit and it can beat a long lease by 30 to 45 percent, with peak occupancy around 75 to 85 percent. Management takes 18 to 22 percent though, and furnishing is not cheap, so the edge is thinner than it first looks.
Where The Yield Lands
Net yield is what you keep, and Business Bay is gentler on that number than Downtown. Service charges run about AED 15 to 25 a square foot against AED 40 and up in prime Burj-adjacent towers, so more of the rent survives to your account.
Add it all up and gross yields sit in the 6 to 9 percent band, with well-placed one-beds at the top and bigger units trailing. For many buyers it is the most dependable way to invest Dubai property capital for monthly income, which is why it trades more actively than
comparable Dubai properties out in the Marina or on the Palm.
One risk worth pricing in. The construction pipeline holds north of 12,000 units. Should they all land between 2026 and 2028, a 5 to 10 percent dip in rents is the likely cost of the market absorbing them.
Which argues for quality over a bargain: pick a proven, well-run building rather than the cheapest floor plate on the board. In a supply glut the desirable towers hold their tenants and their rent; the weak ones start discounting.




















Sign in to leave a comment.