
You can buy home before selling your current house in Seattle — and for most homeowners looking to buy another house before selling yours, it's actually the smarter move.
Seattle sellers pick the strongest offer, not the first one. Most homeowners assume they have to sell before they can buy home before selling their current house, but waiting to buy another house before selling yours can cost you the home you actually want, especially once your offer carries a home sale contingency.
The good news: there's more than one way to buy home before selling, from bridge loans to programs built specifically to help you buy another house before selling yours without a contingency slowing you down.
This guide walks through every option to buy home before selling, what it takes to qualify, and how to decide whether you should buy another house before selling yours or sell first instead.
Why You Should Buy Home Before Selling In Seattle's Market
When you buy home before selling your current house, you skip one of the biggest weaknesses in a real estate offer: the home sale contingency.
A home sale contingency is a condition in your offer. It says your deal to buy another house before selling yours only closes if your current home sells first. If that sale falls through, the deal to buy home before selling can collapse with it. This protects you, but it puts the risk on the seller.
In a fast market like Seattle, sellers rarely accept that risk. When a home draws several offers in days, a contingent offer to buy another house before selling yours looks weaker than a clean one, even at the same price. Given the choice, sellers pick the offer with no strings attached — which is exactly why buyers who buy home before selling tend to win.
This is why choosing to buy home before selling — rather than waiting — competes so well. It tells the seller you're ready to close no matter what happens with your current home. That certainty is what lets you buy another house before selling yours
on the same footing as a cash buyer.
Waiting has a real cost, too. Sell first, then try to buy another house before selling yours would have let you buy sooner, and someone with a cleaner offer may already have the home you wanted. Choosing to buy home before selling keeps you in the game.
Ways To Buy Home Before Selling Your House
Wanting to buy another house before selling yours means finding a way to fund the new purchase before your old home closes. Here are the most common ways homeowners buy home before selling.
Bridge Loan
A bridge loan is a short-term loan that uses the equity in your current home to help you buy another house before selling yours. It "bridges" the gap between the new purchase and the old sale. Bridge loans usually come with a repayment window of six to twelve months. Because they're short-term and higher risk for the lender, they often carry higher interest rates and extra fees than a standard mortgage used to buy home before selling.
HELOC And Home Equity Loan
Both let you borrow against your current home's value to buy another house before selling yours, but they work differently.
HELOC
A HELOC, or home equity line of credit, works like a credit card and is one of the more flexible ways to buy home before selling. You get a credit limit, and you only pay interest on what you actually use. The rate is usually variable, meaning it can go up or down over time.
Home Equity Loan
A home equity loan gives you one lump sum upfront to buy another house before selling yours. It comes with a fixed interest rate and a fixed monthly payment, so your costs stay the same for the life of the loan.
Buy Now, Sell Later Programs
These are programs built specifically to help you buy home before selling. Most work by lining up a backup buyer for your current home, or advancing you funds against your equity, so your move to buy another house before selling yours isn't tied to a sale contingency.
CrossCountry Mortgage offers a Buy Now, Sell Later option that lets buyers make an offer on a new home before their current one sells. Orchard offers a similar program, backing your offer so you can buy another house before selling yours without waiting on the sale. Homeward's program works the same way, giving buyers backing to make a stronger offer while their current home is still on the market.
Rent-Back Agreement (Sale-Leaseback)
With a rent-back agreement, also called a sale-leaseback, you sell your current home first, then stay in it as a tenant for an agreed period. This gives you time to buy another house before selling yours without rushing, while the buyer of your old home waits to move in.
Carrying Two Mortgages
Some homeowners simply take on two mortgage payments at once — the old one and the new one — while they buy another house before selling yours. This means covering two monthly payments out of pocket in the meantime. If the old home takes longer to sell than expected, that cash-flow strain can add up fast.
How Contingency Buster Lets You Buy Home Before Selling

The Contingency Buster Program lets you buy home before selling — and buy another house before selling yours — with the least risk and the least hassle. Here's how the process works, step by step.
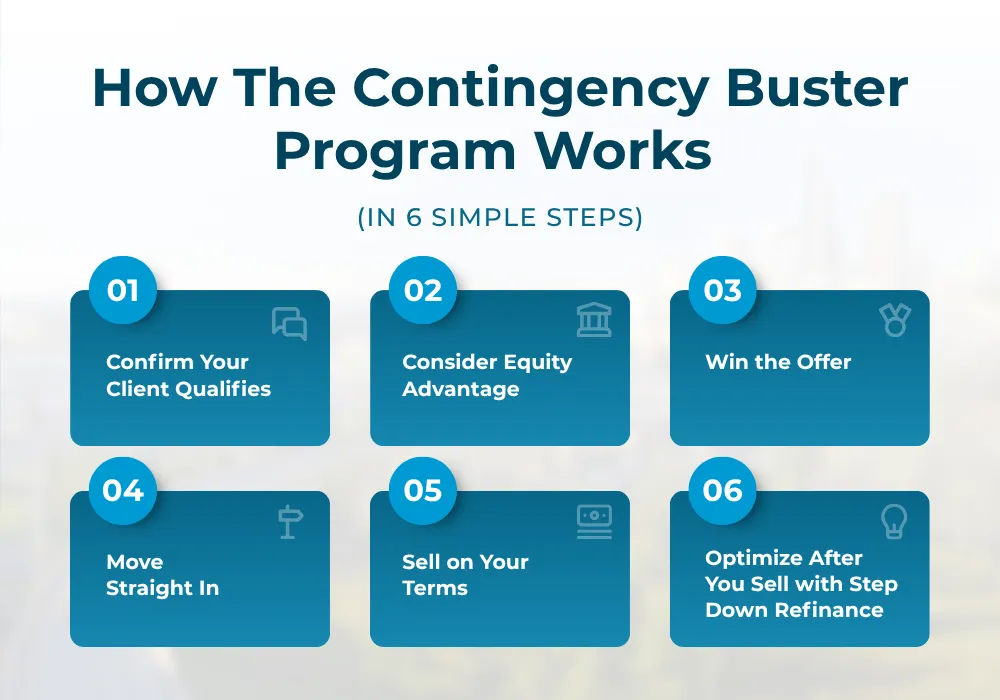
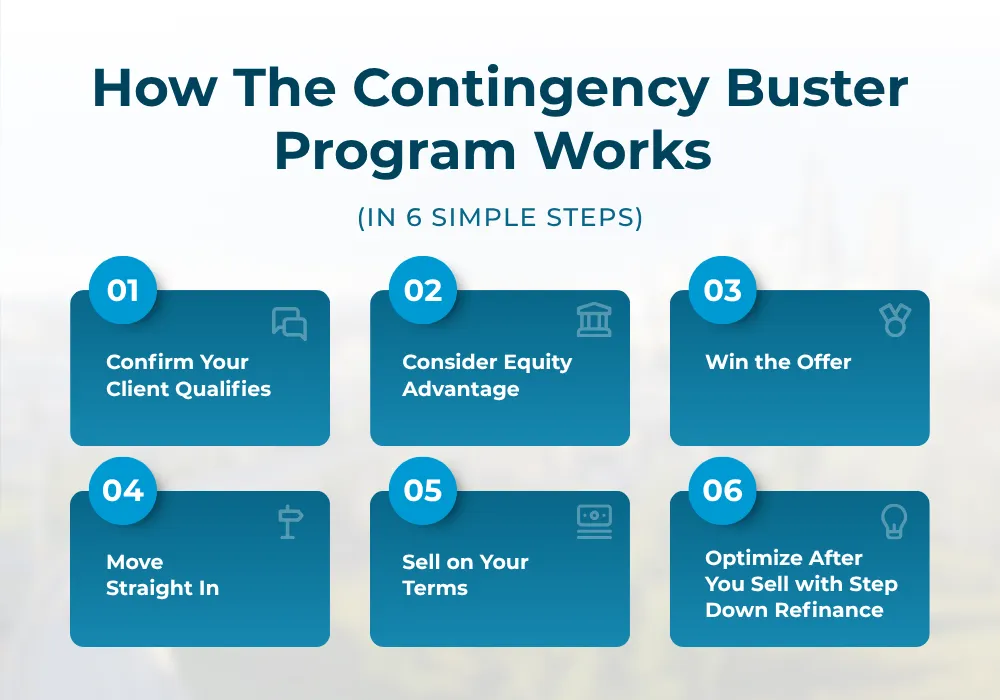
Step 1: Confirm You Qualify
To buy home before selling through this program, you need at least 22% equity in your current home. That's the only requirement to make the sale contingency disappear from your next offer.
Step 2: Use Equity Advantage
Equity Advantage lets you access up to 75% of your current home's loan-to-value equity before it sells, so you can buy another house before selling yours without waiting on the market. This isn't a loan. There's no interest and no monthly payment. The advance is simply repaid in full through escrow once your current home sells.
Step 3: Make A Non-Contingent Offer
With your funding in place, your offer to buy home before selling goes in backed by a guaranteed backup purchase contract on your current home. That removes the sale contingency entirely. Seattle's Mortgage Broker moves quickly, helping you buy another house before selling yours while competing directly with cash buyers.
Step 4: Move Into Your New Home
Once you close, you move straight into your new home. There's no storage unit to rent and no temporary housing to arrange. You move once.
Step 5: Sell Your Old Home
With your old home now empty, you can stage it fully and list it on your own schedule, before or after your move. A vacant, staged home can sell 33 to 50% faster, and for 5 to 10% more than a comparable unstaged home, according to NAR — one more reason to buy another house before selling yours instead of listing an occupied home.
Step 6: Refinance With Step Down Refinance
After your old home sells, any leftover equity can be applied to your new mortgage through the Step Down Refinance program. This lowers the principal balance on the home you bought before selling.
What You Need To Buy Home Before Selling
Before you buy home before selling — or buy another house before selling yours — lenders and programs look at a few key numbers. Here's what you need to have in order.
Understand Your Current Home's Equity And Down Payment
Your equity is the difference between what your home is worth and what you still owe on it. Lenders calculate this by ordering a valuation on your home and subtracting your loan balance. That equity can then be converted into cash through a loan, an advance, or the sale itself, and used as the down payment when you buy home before selling.
Know Your Debt-To-Income Ratio And Mortgage Preapproval
Your debt-to-income ratio, or DTI, compares your monthly debt payments to your monthly income. Lenders use this number to decide how much they'll let you borrow toward a plan to buy another house before selling yours. If you end up carrying two mortgages at once, even for a short time, your DTI goes up, and that can affect what you qualify for.
This is why mortgage preapproval matters before you try to buy home before selling. Getting preapproved before you start house hunting tells you exactly what you can afford and shows sellers you're a serious, qualified buyer.
Find Out About Closing Costs
Buying a new home comes with standard closing costs on top of your down payment. These typically include lender fees, title insurance, escrow fees, appraisal costs, and recording fees. Budgeting for these costs ahead of time keeps you from being caught off guard at the closing table when you buy home before selling.
How To Decide If You Should Buy Home Before Selling
Deciding whether to buy home before selling — or buy another house before selling yours — comes down to your equity, your budget, and how comfortable you are with risk.
If you have enough equity and want to avoid contingency risk, moving twice, and limited access to your cash, choosing to buy home before selling is usually the stronger move. If your equity is low or your budget is tight, selling first may be the safer path, even with the trade-offs that come with it.
A real estate agent plays a big part in helping you buy another house before selling yours. Your agent coordinates closing dates between your sale and purchase, negotiates rent-back terms with buyers or sellers when needed, and helps you time your offer to when the local market favors you most. That coordination is often the difference between a smooth move and a stressful one.
Selling first still makes sense in some cases. If you don't have 22% equity, or your budget can't absorb even a short overlap in payments, selling first removes the pressure that comes with trying to buy another house before selling yours. You give up some negotiating power on your next offer, but you avoid taking on financial risk you can't comfortably carry.
Move First, Without The Wait
Choosing to buy home before selling means you never lose a home to a cleaner offer. Talk to Seattle's Mortgage Broker to see if you qualify to buy another house before selling yours through the Contingency Buster Program.
Frequently Asked Questions
Can You Close On A House Before Selling Your Current One?
Yes. With options like a bridge loan, a HELOC, a home equity loan, or a program like Contingency Buster, you can buy home before selling — closing on a new home while your current one is still on the market.
What If My House Doesn't Sell As Planned?
This is the biggest risk of trying to buy another house before selling yours. If you're carrying two mortgages, a slow sale means more months of double payments. Programs with a guaranteed backup purchase contract remove this risk, since you already have a committed buyer for your old home before you make your next offer.
How Does A Home Sale Contingency Work In A Competitive Market?
A home sale contingency ties your purchase to selling your current home first. In a competitive market, sellers usually pass on these offers because they add risk and delay — which is why so many buyers now choose to buy home before selling instead. A non-contingent offer, backed by cash, a loan, or a backup purchase contract, competes far better.
What Happens If Your Home Sells Before You've Found A New One?
If your home sells before you've found your next one, you may need temporary housing or a rent-back agreement to stay in your current home a bit longer. This is one reason many buyers prefer to buy another house before selling yours in the first place.
Is It Better To Buy Or Sell First Financially?
It depends on your equity and budget. Choosing to buy home before selling gives you more control and stronger offers, but it can mean carrying two mortgages briefly. Selling first is safer financially if your equity is limited, but it comes with less negotiating power when you're ready to buy another house before selling yours.








Sign in to leave a comment.