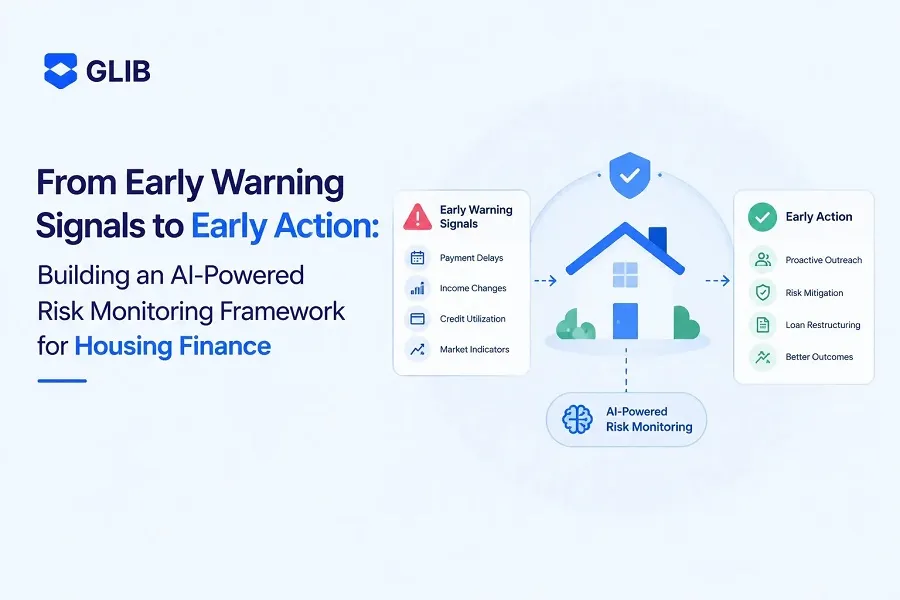

The Risk Doesn’t Begin When the EMI Bounces
In housing finance, a stressed account is rarely the result of a single event.
A borrower may have changed employment. A property may have encountered construction delays. A title document may remain unresolved. A valuation may have changed. Multiple loans may have been sanctioned within the same family. Repayment behaviour may begin deteriorating.
Individually, these may look like isolated exceptions.
Together, they can form a pattern.
This is the fundamental challenge behind Early Warning Signals (EWS) in housing finance: identifying meaningful signals early enough to enable investigation and action.
The National Housing Bank (NHB), in its Early Warning Signals Framework in HFCs circular dated April 26, 2023, highlighted deficiencies associated with reported frauds, including seller impersonation, fake income or employment documents, fake title deeds and builder-borrower collusion. The circular also noted that some deficiencies were identified only after borrowers stopped paying EMIs following loan disbursement.
NHB therefore called for an EWS framework that could trigger alerts before an account becomes an NPA or is declared fraudulent, with EWS tracking integrated into the HFC’s credit monitoring process as a continuous activity.
The implication is significant:
EWS cannot simply be another checklist sitting alongside the lending process. It needs to become part of the intelligence layer around the loan lifecycle.
What Does an Early Warning Signal Look Like in Housing Finance?
The NHB advisory provides an indicative list of EWS indicators for retail loans.
These cover significantly more than repayment behaviour.
They include:
- Incomplete pre-disbursement conditions
- Missing documents prescribed in legal or valuation reports
- Changes in borrower occupation
- Adverse developments in the borrower’s employment sector
- Construction not progressing according to schedule
- Delays in post-disbursement documentation
- Difficulty contacting the borrower
- Other lenders reporting NPA or fraud in the same project
- Waiver of KYC requirements
- DSA-level NPA or fraud patterns
- Title or collateral disputes
- Concealment of loan-related information
- Persistent SMA-2 status
- Balance transfer proposals with additional borrowing
- Cash-based EMI servicing
- Repeated NACH/PDC bounces
- Multiple loans among family members
- Abrupt changes in property value
- Delayed CERSAI/MCA charge creation
- Loans granted without required builder/developer NOC
This list demonstrates an important characteristic of housing-loan risk:
Risk is distributed across data.
It doesn’t necessarily reside inside the core lending system.
It can exist within documents, borrower information, property records, repayment data, sourcing channels and credit-monitoring systems.
That creates a technology challenge.
The Data Fragmentation Problem
Consider a hypothetical housing-loan account.
At origination:
KYC documents appear complete.
The income documents support the declared income.
The property documents pass initial review.
The loan is sanctioned and eventually disbursed.
Several months later:
- The borrower’s occupation changes.
- Construction progress is slower than expected.
- A post-disbursement document remains outstanding.
- The borrower starts servicing EMIs through cash.
- NACH has bounced multiple times.
Each event may be captured by a different process.
The KYC team sees one piece.
The property-monitoring team sees another.
The collections team sees another.
The credit-monitoring team sees another.
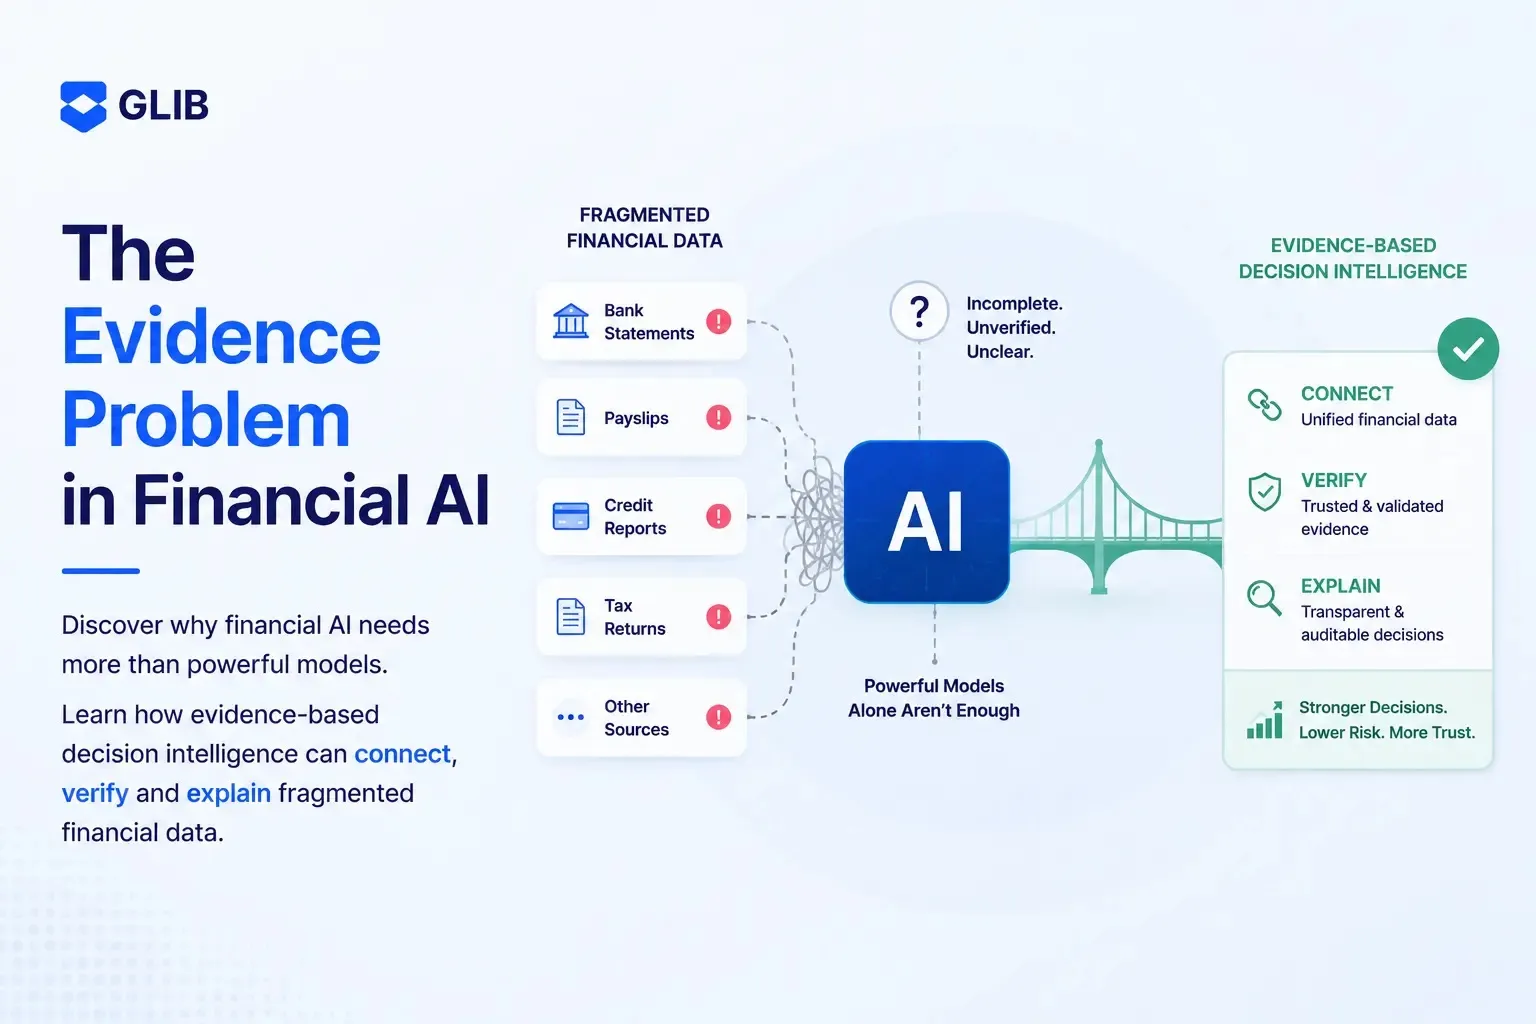
The challenge is therefore not merely data availability.
It is data connectivity and contextualisation.
From Rule-Based Checks to Connected Risk Intelligence
Traditional EWS implementations can rely heavily on predefined rules.
For example:
If NACH bounces exceed a defined threshold → generate an alert.
This is useful.
But consider a more contextual scenario:
NACH bounces + change in occupation + unresolved documentation + construction delay
The value comes not just from detecting four individual events, but from bringing them together for investigation.
This creates a three-layer architecture for intelligent EWS.
What an AI-Powered Housing Finance EWS Architecture Could Look Like
A conceptual architecture can be represented as:
The important principle is that AI should augment the monitoring process rather than operate as a black-box replacement for risk governance.
Beyond Retail Loans
The NHB advisory also identifies EWS indicators for Corporate/Project Loans.
These include:
- Restructuring requests
- Promoter stake reductions
- Legal proceedings and penalties
- Construction delays
- Additional credit sought to repay existing loans
- Management changes
- Substantial related-party transactions
- Discrepancies in annual reports
- Non-routing of receipts through designated escrow accounts
This broadens the opportunity beyond individual home loans.
An intelligent EWS architecture can potentially support:
- Retail Housing Loans
- Construction Finance
- Builder/Project Monitoring
- Corporate Borrower Monitoring
- Portfolio Risk Monitoring
The common requirement is the same:
Bring fragmented evidence together and turn it into actionable intelligence.
How GLIB Fits Into the EWS Journey
GLIB’s Agentic Decisioning & Automation Platform brings together document intelligence, financial intelligence, AI agents and workflow orchestration.
For housing finance, this architecture can be applied across stages such as:
Origination
Analyse and structure borrower and property documentation.
Underwriting
Bring financial and documentary evidence into decisioning workflows.
Fraud & Risk
Surface relevant anomalies and potential risk indicators.
Post-Disbursement Monitoring
Continuously evaluate defined signals across the loan lifecycle.
Credit Monitoring
Route relevant signals, evidence and exceptions into monitoring workflows.
The underlying principle is simple:
Don’t wait for the risk event. Look for the signals that precede it.
The Future of Housing Finance Risk Management
The NHB framework provides HFCs with an important foundation: identify relevant warning signals and integrate their tracking into continuous credit monitoring.
The technology opportunity is to make that process more connected.
When documents, financial information, borrower behaviour, property information and repayment signals can participate in a common intelligence layer, HFCs can move from simply recording exceptions toward understanding patterns.
Because the most valuable risk signal may not be the one that arrives last.
It may be the one that appeared much earlier—but was never connected to the others.
Source
National Housing Bank, NHB(ND)/DOS/Sup. Circular No. 9/2022-23, Department of Supervision, April 26, 2023.
The EWS indicators referenced in this article are based on the indicative list in the NHB advisory. HFCs were advised to add indicators based on their own experience.


















Sign in to leave a comment.