

Navigating the Global Fully Automatic Prefilled Syringe Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global fully automatic prefilled syringe market has entered a phase of sustained expansion, driven by the convergence of biologics innovation, chronic disease management needs, and operational efficiency demands across pharmaceutical manufacturing. Valued at approximately $8.44 billion in 2025, the market is projected to grow at a compound annual growth rate of 9.48 percent through 2032, reaching an estimated $15.91 billion. This trajectory reflects more than incremental volume growth; it signals a structural shift in how drug delivery systems are designed, manufactured, and deployed across therapeutic areas.
Several interconnected challenges are reshaping the industry's operating environment. First, capacity constraints persist despite aggressive capital investments. The concentration of supply among a limited number of tier-one manufacturers and equipment providers creates bottlenecks during periods of surging demand, particularly for specialized formats required by biologics and cell and gene therapies. Second, regulatory harmonization remains uneven. While recent standardization efforts and guidance frameworks aim to streamline combination product compliance, manufacturers must still navigate divergent requirements across jurisdictions, increasing validation timelines and cost structures. Third, material compatibility and sterility assurance continue to pose technical risks. As drug formulations grow more complex and sensitive to container-closure interactions, the industry faces mounting pressure to deliver consistent, low-particle, and chemically inert prefillable systems without compromising scalability.
These challenges are not merely operational friction points. They represent strategic inflection points that will determine which organizations capture market share over the next decade. Companies that align capacity planning, regulatory readiness, and materials science capabilities with end-user therapeutic needs will be best positioned to navigate the transition from volume-driven growth to value-driven differentiation.
Key Growth Drivers Reshaping the Market
Innovation in prefillable syringe architectures and automated fill-finish equipment is accelerating the shift toward integrated, ready-to-use platforms. Manufacturers are increasingly offering pre-sterilized, siliconized, or silicone oil-free systems designed to reduce manual handling, minimize contamination risk, and streamline batch release. Advanced polymer and glass formulations now support ultra-low temperature storage for biologics and enable specialized applications in ophthalmology and sensitive injectables. Simultaneously, filling and closing equipment has evolved toward modular, high-throughput configurations capable of handling nested ready-to-use formats with flexible output ranges. These technological advances reduce changeover times, improve process consistency, and lower the total cost of ownership for production lines that must accommodate diverse molecule profiles.
Policy and regulatory dynamics are exerting a dual influence on market growth. Standardization initiatives, including updated requirements that define specifications for prefillable syringes and filling equipment, are reducing ambiguity in design qualification and supplier selection. At the same time, regulatory expectations for combination products continue to tighten, placing greater emphasis on quality systems, labeling harmonization, and post-market surveillance. These frameworks are not friction alone; they are shaping procurement behavior. Manufacturers and developers are increasingly prioritizing suppliers with demonstrated compliance maturity, validated aseptic processes, and flexible capacity to manage multi-product portfolios. Recent approvals of prefilled syringe presentations for chronic disease, immunization, and specialty therapies illustrate how regulatory clarity and delivery-system innovation are converging to expand addressable use cases.
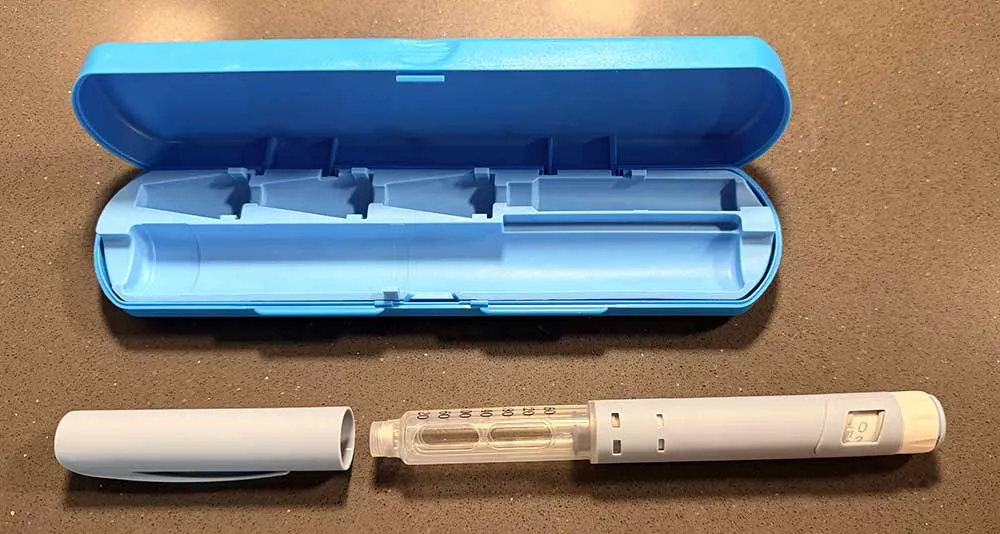
Demand-side shifts are equally consequential. The rising prevalence of diabetes, autoimmune conditions, and oncology indications is driving sustained utilization of prefilled delivery systems that support patient self-administration and reduce preparation errors in clinical settings. Providers and health systems are recognizing that ready-to-use formats shorten administration workflows, decrease dosing variability, and improve adherence in outpatient and home-care environments. For pharmaceutical developers, prefilled syringes offer a pathway to differentiate complex therapies through improved usability, particularly where reconstitution steps or multi-dose vials introduce handling complexity. This alignment between therapeutic complexity and delivery convenience is expanding the strategic relevance of prefillable systems beyond traditional volume-injectable categories.
Supply chain and cost structures are undergoing parallel transformation. Capital investments in domestic and nearshore production capacity are gradually reshaping geographic sourcing patterns, reducing exposure to long lead times and single-region dependencies. At the same time, the economics of prefillable manufacturing are being redefined by automation levels, line efficiency, and format standardization. Producers that can balance throughput with flexibility, while maintaining stringent sterility and particle-control standards, are gaining cost advantages that translate into competitive pricing and more attractive partnership terms. The interplay between material availability, equipment reliability, and regulatory compliance is increasingly determining margin resilience in a market where demand is rising but cost pressures remain persistent.
Worldwide Height Safety Equipment Market
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a concentrated group of tier-one suppliers that combine materials expertise, prefillable system platforms, and integrated equipment capabilities. A small number of companies command the majority of market share, reflecting the high barriers associated with regulatory compliance, manufacturing scale, and long-term qualification relationships with pharmaceutical developers. Leading players are differentiated by their ability to offer end-to-end solutions, from barrel and plunger assemblies to automated filling lines and sterile packaging formats, enabling customers to reduce sourcing complexity and accelerate time to market.
Strategic positioning varies across the field. Some manufacturers emphasize platform breadth, offering washable, siliconized, and pre-sterilized formats across glass and polymer materials to serve diverse therapeutic requirements. Others focus on specialized capabilities, such as silicone oil-free systems for sensitive molecules, ultra-low temperature compatibility for biologics, or nested ready-to-use configurations that support start-ups and large pharma alike. Equipment providers complement these offerings by delivering modular filling and closing systems with high output flexibility, supporting everything from early-stage development batches to large-scale commercial production. This duality of platform breadth and specialized performance is reshaping procurement decisions, as developers increasingly seek partners who can support multiple stages of the product lifecycle.
Recent corporate and product developments underscore the pace of change. One integrated prefillable syringe platform became commercially available in early 2026, signaling a move toward unified systems that combine barrel, plunger, and shield components into a single qualified solution for biologics and vaccines. In parallel, major suppliers announced significant capacity expansions, including multi-million-dollar investments to establish new production lines for glass prefillable syringes at domestic facilities. These moves reflect both demand anticipation and a strategic effort to reduce lead-time risk for customers. On the regulatory front, approvals of prefilled syringe presentations for specialty therapies and vaccine simplification initiatives demonstrate how delivery-system redesign is becoming a commercial lever, not just a convenience feature.
Market evolution is trending toward both consolidation and segmentation. Consolidation is likely as scale advantages in manufacturing, qualification, and global distribution favor larger platforms that can serve multi-regional demand. Segmentation will intensify as specialized formats gain relevance for sensitive biologics, ultra-cold storage, ophthalmology, and self-administration use cases. New entrants and contract development and manufacturing organizations are expanding sterile fill-finish capacity with automated precision lines, creating additional options for developers seeking flexibility or regional supply resilience. The net effect is a landscape where incumbents must defend platform relevance while investing in differentiation, and where capability differentiation, rather than volume alone, increasingly determines long-term positioning.
Forward Outlook: Trends Shaping the Next Three to Five Years
Over the next three to five years, several trends will define how value is created and captured in this market. First, integrated prefillable platforms will become the preferred procurement model for many developers. By combining components and system qualification into a single solution, suppliers can reduce validation burden and accelerate launch readiness. This trend will favor organizations that can deliver consistent quality across multiple formats while maintaining the flexibility to support evolving molecule profiles. The commercial opportunity lies in building platform ecosystems that scale across therapeutic categories, rather than treating each project as a bespoke engineering exercise.
Second, capacity expansion and geographic rebalancing will continue to influence supply dynamics. Investments in domestic and nearshore production are likely to reduce lead-time vulnerability and support regional demand surges, particularly for immunization and chronic care programs. However, capacity growth will need to be matched by process robustness and sterility assurance to avoid quality-related disruptions. Organizations that align expansion plans with demand forecasting and qualification timelines will be better positioned to convert capacity into reliable revenue streams.
Worldwide Oblong Container Market
Third, material and design innovation will deepen, especially around particle reduction, low extractables, and ultra-low temperature performance. As biologics and specialty formulations become more sensitive, the container-closure system becomes a critical determinant of product stability and patient safety. Suppliers that can demonstrate compatibility, low particle load, and consistent performance under demanding storage and handling conditions will gain preference in high-value programs. The risk is that differentiation becomes incremental unless paired with demonstrable clinical and operational benefits, which means evidence generation and technical communication will matter as much as product design.
PW Consulting
Uncertainty remains in the pace of regulatory harmonization, raw material availability, and demand volatility tied to therapeutic pipeline outcomes. Prefilled syringe adoption will continue to depend on whether developers view delivery systems as enablers of differentiation or as commodity components. The organizations that treat them as strategic assets, aligning design, capacity, and compliance with end-user needs, will be the ones that shape market direction rather than react to it.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to strengthen platform versatility without sacrificing quality and compliance rigor. Investing in flexible line configurations, validated ready-to-use formats, and materials suited to sensitive molecules can broaden addressable demand while protecting margin. Building demonstration capacity, robust qualification packages, and clear technical documentation will help convert interest into long-term partnerships.
For investors, the opportunity lies in identifying which capabilities will command premium positioning as the market matures. Platform integration, specialized material expertise, and scalable sterile fill-finish capacity are becoming differentiators. Evaluating suppliers and developers against their ability to manage regulatory complexity, support ultra-low temperature or low-particle requirements, and maintain expansion discipline will improve capital allocation decisions.
For procurement and supply chain leaders, the focus should be on resilience and qualification efficiency. Diversifying across qualified platforms, aligning sourcing strategies with demand volatility, and prioritizing partners with demonstrated aseptic process maturity can reduce launch risk. Early engagement on format selection and compatibility testing will help avoid late-stage redesigns that delay programs and increase cost.
As the market evolves from volume growth to capability-driven competition, detailed segment intelligence, regional demand patterns, and supplier-level capability mapping become essential inputs for strategic planning. Decision-makers seeking to evaluate specific formats, forecast capacity needs, or assess partnership fit will benefit from a more granular view of segmentation, competitive moves, and pricing dynamics. For a deeper exploration of subsegments, regional trajectories, and customized scenario analysis, the full PW Consulting report provides the detailed framework needed to translate market signals into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Fully Automatic Prefilled Syringe Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com





















Sign in to leave a comment.