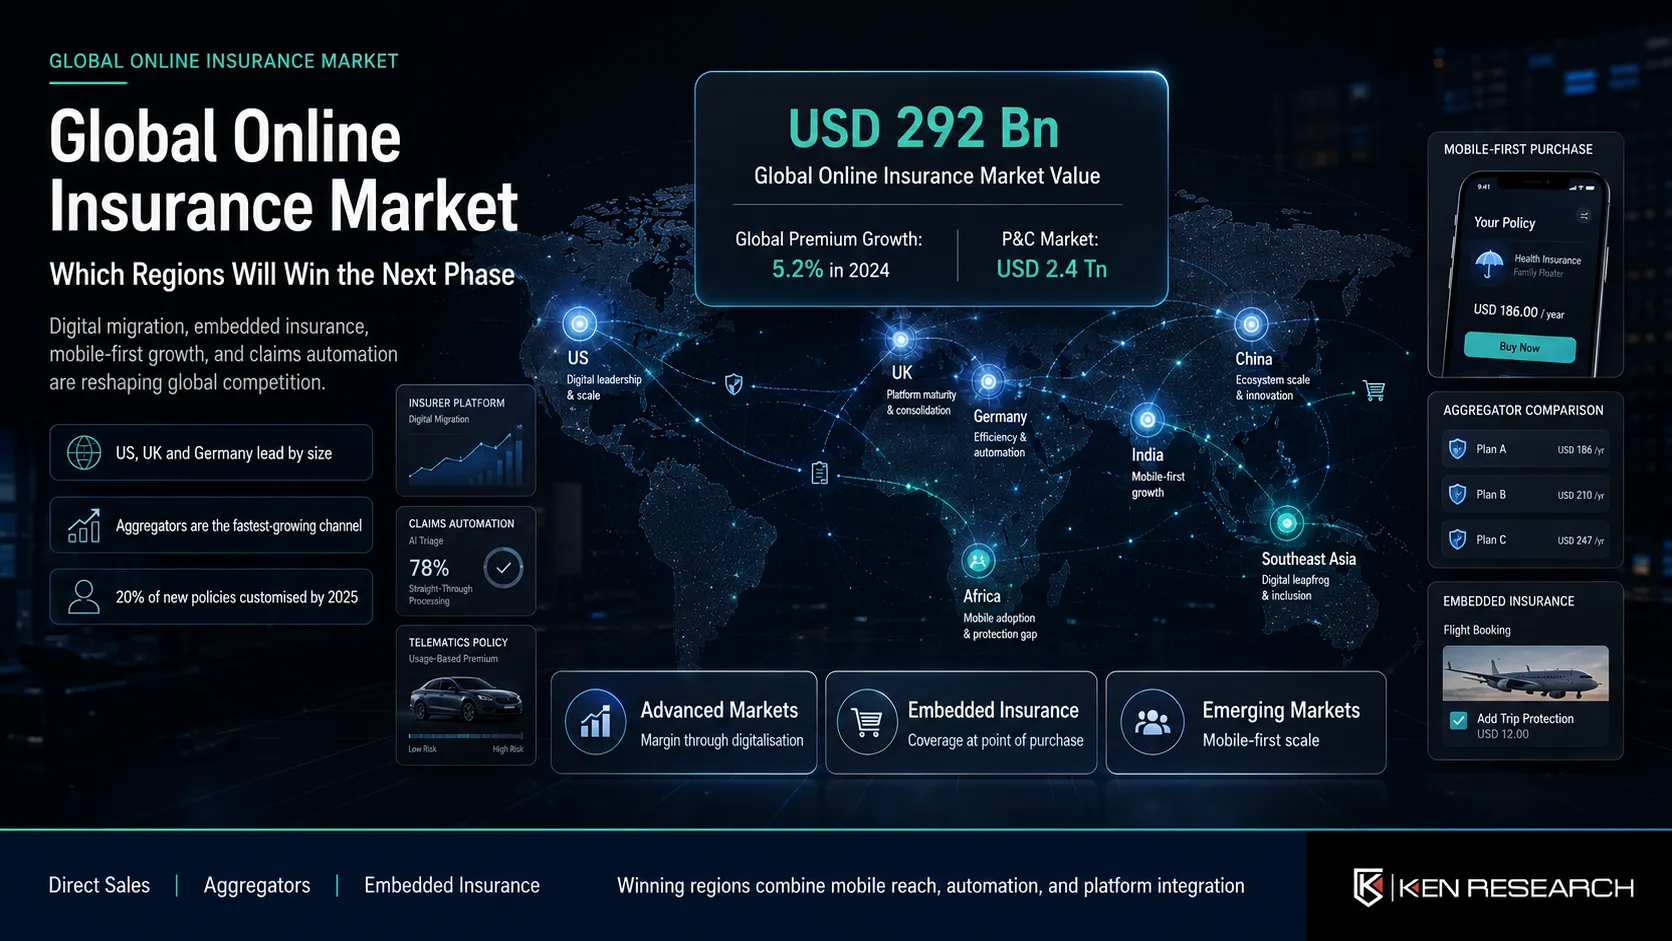

The Global Online Insurance Market was valued at USD 292 billion, based on a five-year historical analysis, per Ken Research estimates. The broader global insurance industry recorded total premium real growth of 5.2% in 2024, before slowing to an estimated 2% in 2025, per Swiss Re Institute's sigma research. The global P&C insurance market alone has doubled in size over the past 20 years to USD 2.4 trillion, per Swiss Re Institute's September 2025 sigma report, with the online channel capturing a growing share of this at every stage. The US, UK, and Germany lead by market size and digital infrastructure, while emerging markets in Asia and Africa are posting the fastest growth rates. About 20% of new insurance policies are expected to be customized by 2025, per Ken Research, reflecting the shift toward data-driven personalisation that online platforms enable and legacy distribution channels cannot. The Global Online Insurance Market report by Ken Research covers market sizing by geography and product type, competitive landscape, distribution channel dynamics, and demand outlook to 2030.
Key Insights: Global Online Insurance Market
- Global Online Insurance Market valued at USD 292 billion, per Ken Research five-year historical analysis
- Global total insurance premium real growth reached 5.2% in 2024, slowing to estimated 2% in 2025, per Swiss Re Institute sigma 2/2025
- Global P&C insurance market reached USD 2.4 trillion, having doubled in 20 years, per Swiss Re Institute sigma 3/2025
- US, UK, and Germany are the dominant online insurance markets by size and digital infrastructure
- Emerging markets account for 20% of world P&C premium, a share that Swiss Re Institute expects to rise as technical capabilities improve
- About 20% of new insurance policies expected to be customised by 2025, per Ken Research, driven by digital platform data capabilities
- Direct sales remain the leading digital sub-segment; online aggregators are the fastest-growing distribution channel
- Non-life emerging market premiums grew 5.3% in 2023, per Swiss Re Institute sigma 3/2024, led by Asia
- Key players: Allianz, AXA, State Farm, Progressive, Lemonade, Policybazaar, Ping An, Bajaj Allianz
The Three Competitive Axes of the Global Online Insurance Market
The Global Online Insurance Market does not have a single growth story. It has three, operating in parallel across different geography and product combinations, and the regions that win the next phase will be those that execute effectively on whichever axis fits their structural starting point.
Axis : Advanced markets, margin through digitalisation. The US, UK, Germany, and advanced Asia Pacific are not high-growth online insurance markets in volume terms. Swiss Re Institute forecasts global premium growth broadly in line with GDP over the next decade in advanced markets. What drives online channel expansion here is not new insurance buyers but migration of existing buyers from agent and broker channels to direct digital purchase. The US digital insurance platform market, with an 88% adoption rate of digital platforms among insurers, reflects how far advanced markets have moved. The competitive battleground is user experience, claims automation, and telematics-enabled personalisation.
Three structural dynamics shaping who wins across the Global Online Insurance Market:
- Insurtech disruption and consolidation: The global insurtech ecosystem has attracted substantial venture investment, with India alone accounting for 35% of the USD 3.66 billion in Asia-Pacific insurtech investment, per S&P Global Market Intelligence. Globally, insurtechs like Lemonade in the US, Acko in India, and ZhongAn in China have validated digital-native insurance models and are now consolidating. M&A activity is accelerating as larger incumbents acquire digital capabilities rather than build them.
- Embedded insurance expansion: The integration of insurance into non-insurance digital platforms including e-commerce, ride-hailing, travel, and fintech is the fastest-growing distribution channel in the Global Online Insurance Market. This model removes the purchase friction entirely, offering coverage at the point of need during a transaction already taking place. Embedded insurance is expanding the addressable market beyond consumers who actively seek insurance.
- Emerging market leapfrogging: Non-life premiums in emerging markets grew 5.3% in 2023, per Swiss Re Institute, with Asia contributing the majority. India, Southeast Asia, and sub-Saharan Africa are all building digital insurance infrastructure on mobile-first foundations, skipping the legacy agent model entirely. The India Online Insurance Market exemplifies this: with 850 million broadband subscribers and IRDAI mandating digital customer journeys, India is building at scale faster than advanced markets migrated.
Competitive Landscape of the Global Online Insurance Market
Allianz, AXA, State Farm, Progressive, and Lemonade lead in advanced markets by brand, capital, and digital platform maturity. In Asia, Ping An and ZhongAn dominate China's digital insurance market; Policybazaar leads India's aggregator segment. Market concentration at the top five insurer level has been declining across nine of eleven large markets analysed by Swiss Re Institute, as smaller specialised players and MGAs take share through niche product capability and lower cost structures. Captives represent an estimated USD 60 to 80 billion global market, per Swiss Re Institute, reflecting the growing appetite for non-standard risk solutions that digital platforms increasingly serve. The Malaysia Online Insurance Market and Singapore Online Insurance Market represent two distinct Southeast Asian models worth benchmarking: Malaysia as a mobile-first volume market, Singapore as a regulatory innovation hub with outsized global influence.
Conclusion
The Global Online Insurance Market is being shaped by three forces converging simultaneously: digital migration in advanced markets compressing legacy distribution margins; embedded insurance expanding the addressable market in every geography; and emerging market mobile-first infrastructure enabling scale without the agent model legacy. Swiss Re Institute's forecast of 2% real premium growth in 2025 versus 5.2% in 2024 signals a more selective competitive environment where efficiency and digital capability determine who grows and who stagnates. The regions that will win the next phase are not the largest today but those building the deepest mobile distribution reach, the fastest claims automation, and the most seamless embedded product integration. The Global Online Insurance Market Outlook to 2030 maps the full competitive and regional trajectory in detail.
FAQs
1. What is the size of the Global Online Insurance Market?
The Global Online Insurance Market was valued at USD 292 billion, based on a five-year historical analysis, per Ken Research estimates. The broader global insurance industry grew at 5.2% in real terms in 2024, per Swiss Re Institute sigma research, before slowing to an estimated 2% in 2025 due to global economic uncertainty and tariff-related headwinds. The US, UK, and Germany are the dominant markets by size, digital infrastructure, and platform maturity. Emerging markets in Asia account for the fastest volume growth within the global total.
2. Which distribution channels are driving the Global Online Insurance Market?
Direct sales remain the leading digital distribution sub-segment, as consumers increasingly purchase insurance directly from insurer websites and apps. Online aggregators are the fastest-growing channel, enabling multi-product price comparison and driving consumer switching. Embedded insurance, integrated into e-commerce, fintech, travel, and ride-hailing platforms, is emerging as the structurally most disruptive channel, removing purchase intent requirements entirely. For a detailed distribution channel breakdown, the Global Online Insurance Industry Analysis by Ken Research covers channel share and competitive dynamics in full.
3. How are insurtechs reshaping the Global Online Insurance Market?
Insurtechs have moved the Global Online Insurance Market from incremental digitisation to structural disruption. Digital-native models including Lemonade in the US, Acko in India, ZhongAn in China, and Wefox in Europe have validated that insurance can be bought, managed, and claimed entirely online without agent involvement. The global insurtech sector has attracted billions in venture capital, with India alone accounting for 35% of Asia-Pacific insurtech investment, per S&P Global Market Intelligence. The current phase is consolidation: incumbents are acquiring digital capabilities through M&A, and insurtechs with proven unit economics are scaling while weaker models exit.
4. What is embedded insurance and why does it matter for the Global Online Insurance Market?
Embedded insurance is the integration of insurance products within non-insurance digital platforms at the point of transaction. A consumer buying a flight gets travel insurance offered within the booking flow. A consumer financing a smartphone gets device insurance bundled at purchase. This model eliminates the need for the consumer to actively seek insurance, dramatically expanding the addressable market. It is the fastest-growing distribution model in the Global Online Insurance Market because it converts passive non-buyers into insured customers without a separate sales process.
5. Which regions will drive Global Online Insurance Market growth to 2030?
Emerging markets in Asia will contribute the largest share of incremental volume growth, led by India, Indonesia, Vietnam, and the Philippines, all of which are building mobile-first digital insurance infrastructure on large uninsured populations. Advanced markets including the US, UK, and Germany will drive revenue growth through premiumisation, personalisation, and digital claims automation rather than new buyer volume. The Thailand Online Insurance Market and Malaysia Online Insurance Market represent two of the most instructive Southeast Asian growth stories within this regional expansion.






















Sign in to leave a comment.