

Buying a building that has a business downstairs and living space upstairs can look like a pretty simple deal. Suddenly, there are questions about zoning, leases, income, appraisals, insurance, occupancy, and the condition of the building.
I have seen buyers get excited about a property, make an offer, and only afterward discover that the lender does not view it the same way they do. That is a rough place to be. Money has already been spent, deadlines are getting closer, and nobody wants to start over.
Mixed use mortgage loans can work well for the right property and borrower. But banks do not look at these buildings exactly like they look at a single family home. They are trying to understand how the residential and commercial parts work together, how much income the property produces, and what the property would be worth if something went wrong.
Honestly, the best time to learn all of this is before you fall in love with the building.
What Is a Mixed Use Property?
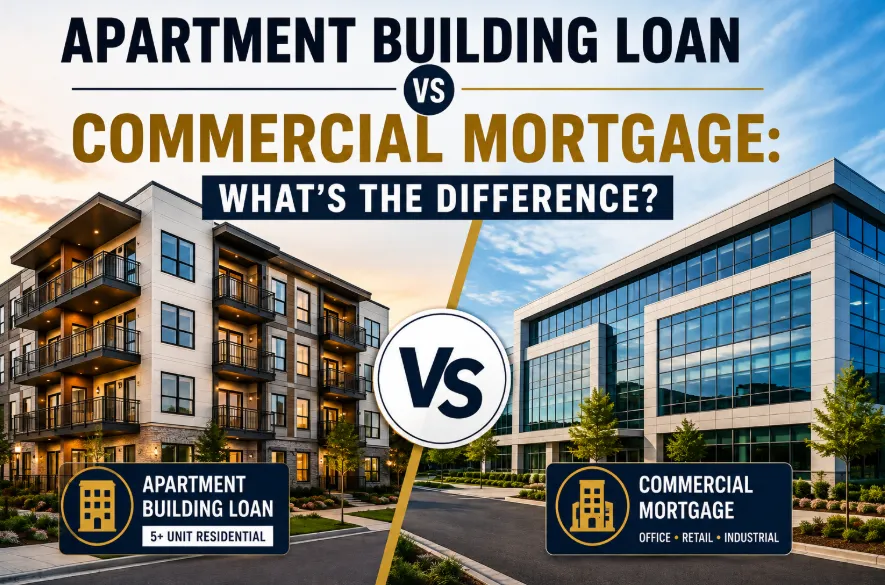
A mixed use property combines residential and commercial space. The common example is a retail store on the first floor with an apartment above it. It could also be a professional office with a residence, a small restaurant with living quarters, or a building containing apartments and several commercial units.
The physical layout is only part of the story. Legal use matters just as much.
A building may look like a perfect mixed use property, but the lender will want to know whether the residential and commercial spaces are properly permitted. Zoning records, permits, property records, and the certificate of occupancy can all come into play.
I have seen situations where an owner added a living area years ago and assumed it was fine because nobody complained. That does not mean a lender will accept it. If the use is not legal, financing can become difficult.
So before spending serious money on inspections and other closing work, verify what the property is actually allowed to be used for.
How Banks Decide Which Financing Fits
The first major question is whether the property is primarily residential or commercial. Mixed use mortgage loans require that distinction early.
There is no single rule that every lender follows. One bank may look closely at the percentage of residential space, while another may place more weight on the property's income and intended use.
A building with a large owner occupied residence and a small office may be treated differently from a building with several retail spaces and one apartment.
If the commercial side is dominant, the lender may move the transaction into commercial underwriting. That can change the down payment, documentation, loan term, interest rate, appraisal process, and other requirements.
This is why mixed use mortgage loans should be discussed with the lender early, not after the purchase contract is signed.
Owner Occupancy Makes a Difference
Ask yourself who will actually use the property.
If you plan to live in the residential portion and operate your business in the commercial space, that is different from buying the entire building as an investment.
A lender wants the intended use stated clearly. Do not try to make the property sound more residential or more commercial simply because you think one category will be easier.
The Appraisal Can Change Everything
Many buyers think an appraisal is simply about finding the market value. With a mixed use property, the process can be more involved.
The appraiser may consider comparable sales, current rents, vacancy, property expenses, building condition, legal use, location, and the income the property can reasonably produce.
Suppose you agree to buy a building for $900,000 because the seller says that is its value. The appraisal comes back at $800,000. The bank may not base the loan on the seller's price. You may suddenly need more cash, renegotiate the purchase, or walk away.
I have seen this happen a lot.
A buyer may also assume that strong rents automatically mean a high value. Not necessarily. The appraiser has to look at the whole property and the local market.
What the Appraiser May Review
The list can include:
- Building condition and deferred repairs
- Total and usable square footage
- Residential and commercial areas
- Zoning and permitted use
- Comparable sales
- Current leases and rents
- Vacancy
- Operating expenses
- Location and neighborhood demand
- Recent improvements
Unusual properties can also be harder to compare. That does not automatically mean the value will be lower. It simply means the details matter more.
Rental Income Is a Big Part of the Picture
For an investment property, income can have a major influence on the underwriting decision.
The bank may review the rent roll, leases, property taxes, insurance, maintenance, management costs, utilities, and other expenses. Saying that a property brings in $10,000 a month is only the beginning.
The lender wants to know what is left after reasonable operating costs.
For an owner occupied property, the business itself may also be reviewed. Tax returns, profit and loss statements, bank statements, and other financial records can be requested.
This is one area where a commercial real estate loan can be different from a standard home mortgage. The lender may spend much more time examining the property's income and expenses.
Do not inflate projected rent to make the deal look better. Use numbers you can support. If the current rent is below market because of an old lease, explain that rather than pretending the higher rent already exists.
Down Payment and Loan Terms
Do not assume the cash needed at closing will look like a typical home purchase.
The required equity depends on the lender, property, occupancy, loan program, and overall risk. Some mixed use transactions may require more money down than a conventional owner occupied residence.
Loan terms can also be different. A commercial real estate loan may have shorter terms, different amortization schedules, variable rates, prepayment provisions, or a balloon payment.
Look beyond the monthly payment.
A payment can look comfortable while the loan still has a large balance due at maturity. Ask how long the rate is fixed, how the loan amortizes, whether there is a prepayment penalty, and what happens when the term ends.
Understanding those details before closing is far better than learning about them later.
Florida Location Can Affect the Numbers
Florida has very different real estate markets. A mixed use building in Miami does not have the same operating costs or market conditions as one in Tampa, Orlando, Jacksonville, Fort Lauderdale, or a smaller community.
Insurance deserves special attention. Wind and flood coverage can affect the property's expenses, depending on where the building sits and what coverage is required.
Property taxes matter too.
Get realistic numbers before you build your financial projections. I have seen buyers use a seller's old insurance figure or a rough tax estimate and then discover that the actual expenses are much higher.
And trust me, that gets expensive fast.
Local zoning is another issue. It can also affect how a commercial real estate loan is structured. Rules can differ between cities and counties, so never assume that because a neighboring building has apartments and retail, your property can automatically be used the same way.
Existing Leases Tell a Story
Tenants can make a property easier to understand because there is real income to review. But leases can also reveal risk.
A lender may look at rent amounts, lease expiration dates, renewal options, rent increases, security deposits, tenant responsibilities, and unusual concessions.
Consider two buildings.
The first has five tenants, each with reasonable rent and leases that extend for several years. The second has one tenant producing most of the income, and that lease expires in six months.
Both properties may look good from the outside. From a lender's perspective, they are not the same.
Vacancy is another concern. If a large commercial area is empty, the lender may use a conservative income assumption rather than counting on a new tenant appearing immediately.
A Realistic Example
Imagine a buyer finds a two story building in South Florida. A small café occupies the first floor, and there is a legal apartment upstairs. The buyer plans to live upstairs and keep the café tenant.
The lender first checks the zoning and permitted use. Everything matches.
The appraiser reviews comparable properties and supports the purchase price. Good.
Then the lender reviews the café lease. It has three years remaining and reasonable increases. Better.
The buyer's finances show enough liquidity, manageable debt, and the required equity.
Now the deal makes sense.
But change one detail. Suppose the apartment was never legally approved. Or the café lease ends next month. Or the building needs a major roof replacement.
The lender now has a different risk to consider.
That is how underwriting works. A single detail can change the conversation.
How to Make the Financing Process Easier
Start with the property documents.
Confirm the zoning. Verify the legal use. Review every lease. Get insurance estimates. Understand the real operating expenses. Then talk with lenders that have experience with this type of property.
Do not send the same application blindly to a dozen banks.
Instead, explain the property clearly. Tell the lender how much space is residential, how much is commercial, who will occupy it, what the current income is, and what you plan to do.
A short conversation can tell you whether you are even in the right lending lane.
When a Commercial Real Estate Loan May Be Better
If the property is mainly commercial, generates substantial rental income, or is being purchased as an investment, a commercial real estate loan may fit better than a standard residential mortgage.
The underwriting may take more work, but the loan can be structured around the property's actual purpose.
There is no universal best option. The right financing, including a commercial real estate loan when appropriate, depends on the property, borrower, occupancy, income, and long term plans.
Questions to Ask Your Lender
Before applying for mixed use mortgage loans, ask how the property will be classified and how rental income will be calculated.
Find out the expected down payment, reserve requirements, appraisal process, interest rate, amortization period, loan term, closing costs, and prepayment rules.
Ask whether there is a balloon payment.
And if you do not understand a term, ask for an explanation in plain English. You are signing the loan. You should understand it.
Frequently Asked Questions
Can mixed use properties qualify for mortgage financing?
Yes. Approval depends on the property's legal use, value, condition, income, occupancy, and the lender's guidelines.
Are mixed use mortgage loans harder to qualify for?
They can be, because lenders may evaluate both residential and commercial factors.
Can I live in a mixed use building?
Yes, in many cases, if the residential use is legal and permitted under the loan program.
Can rental income help me qualify?
It can when the lender accepts the income and the amount is supported by leases and other records.
Is a larger down payment required?
Not always. The required equity depends on the lender, property, borrower, and loan structure.
Does my credit score matter?
Yes, but credit is only one part of the lender's overall evaluation.
Can I refinance a mixed use property?
Yes. Refinancing may be available depending on the property's value, income, existing debt, and borrower qualifications.
Are leases important to underwriting?
Very. Lease terms help the lender judge how stable the property's income may be.
Does zoning affect financing?
Absolutely. The lender needs confidence that the property's current use is legal.
Should I get insurance quotes before applying?
Yes. Insurance is part of the property's operating costs and can affect the overall numbers.
Resources
Before you apply, check local county or city zoning departments, property appraiser records, insurance providers, and your accountant or real estate attorney.
Those sources can help confirm details that should not be based only on a seller's description.
A lender experienced with mixed use properties can also explain what documents will be needed and how the property may be evaluated.
Final Thoughts
Banks are not trying to make mixed use financing difficult for no reason. They are looking at a property that has several moving parts.
The building matters. The income matters. The leases matter. Zoning matters. Insurance matters. Your finances matter too.
The biggest mistake is waiting until the last minute to figure these things out.
If you are considering mixed use mortgage loans in Florida, start the financing conversation before you become fully committed to the property. Find out how the lender will classify it, what the appraisal needs to support, and whether the income can carry the debt.
Be honest about repairs. Be clear about your intended use. Bring organized records.
For buyers comparing mixed use mortgage loans, it can be helpful to speak with a lender that understands both residential and commercial property. If a commercial real estate loan is the better fit, you want to know that early, while you still have room to make a smart decision.
The goal is not simply getting approved. It is buying a property with financing that still makes sense years after you receive the keys.










Sign in to leave a comment.