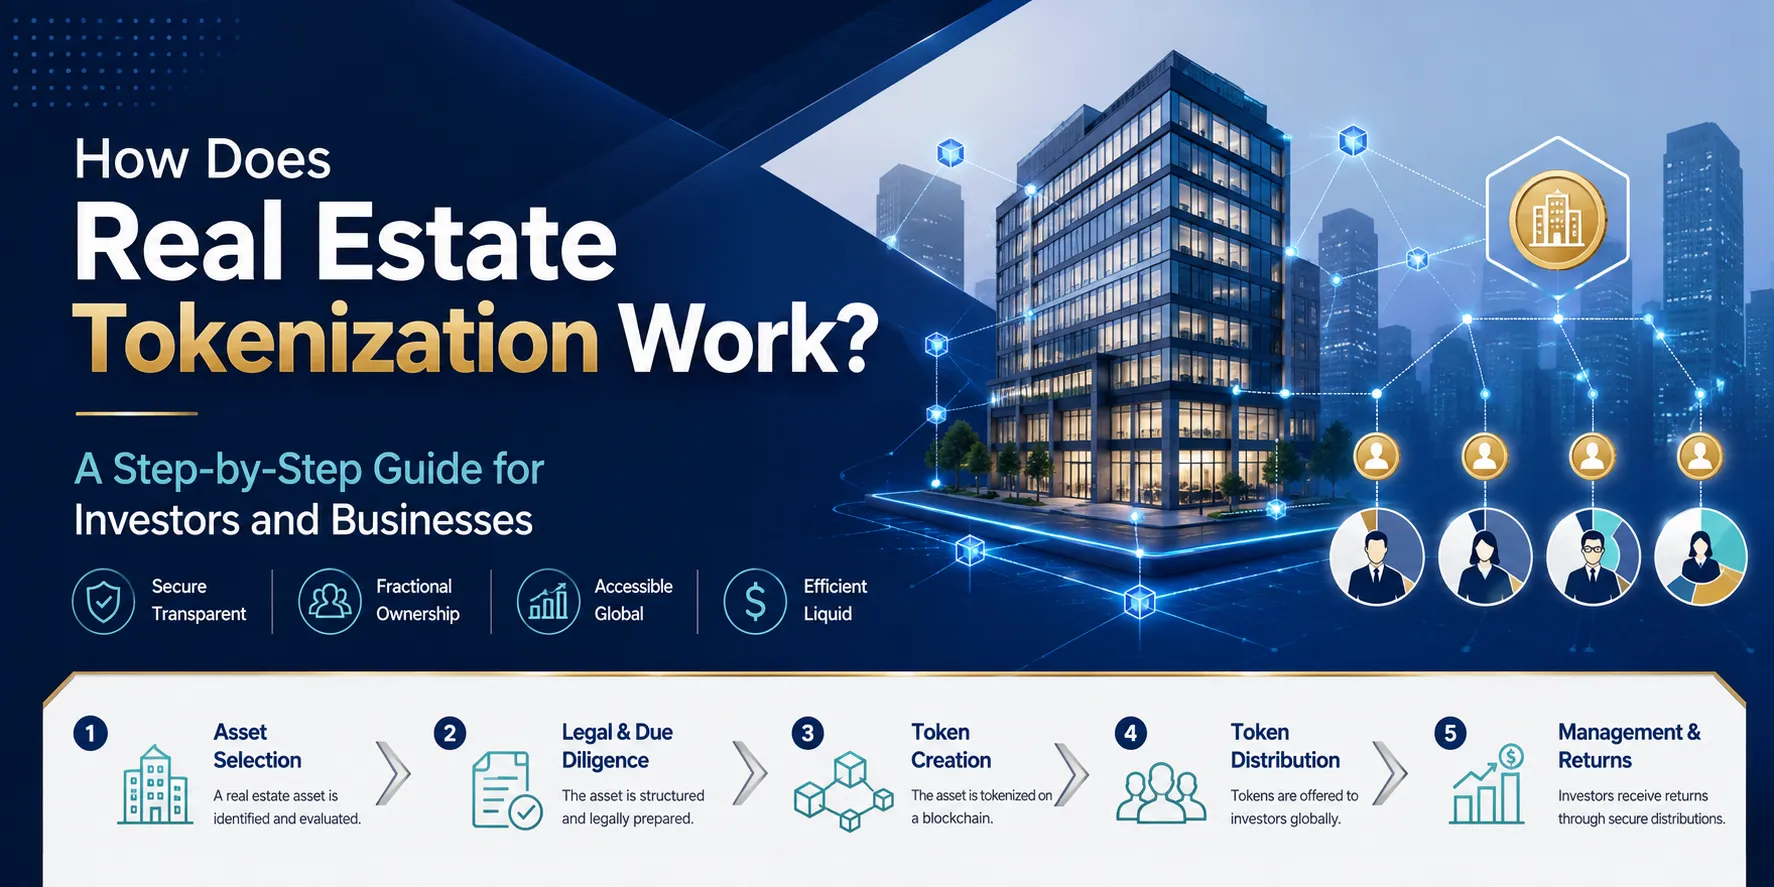

Real estate has traditionally been viewed as a valuable but relatively illiquid asset class. Buying a property usually requires significant capital, extensive documentation, legal due diligence, intermediaries, and a long holding period. Even when investors want to sell, finding a suitable buyer and completing the transaction can take weeks or months. Real estate tokenization is emerging as a way to modernize this process by representing ownership interests or financial claims related to real estate as digital tokens on a blockchain.
Instead of requiring one investor to purchase an entire property, tokenization can divide an economic or ownership interest into many digital units. Investors can potentially purchase smaller portions, while property owners and businesses can access a broader pool of capital. Deloitte estimates that the value of tokenized real estate could reach approximately $4 trillion by 2035, compared with less than $0.3 trillion in 2024, representing a projected compound annual growth rate of 27%.
However, tokenization is much more than simply putting a property on a blockchain. The legal structure, ownership rights, property valuation, compliance procedures, custody arrangements, smart contracts, investor onboarding, and secondary-market mechanisms all have to work together. This guide explains how real estate tokenization works step by step and what investors and businesses should understand before entering the market.
What Is Real Estate Tokenization?
Real estate tokenization is the process of creating blockchain-based digital tokens that represent ownership, an economic interest, debt, equity, fund interests, or another legally defined claim connected to a real estate asset.
The underlying property does not literally become digital. Instead, a legal and financial structure is established around the property, and tokens are issued to represent defined rights within that structure. Depending on the jurisdiction and project design, the property may be held directly by a legal entity such as a special-purpose vehicle (SPV), while investors hold tokens representing shares or beneficial interests in that entity.
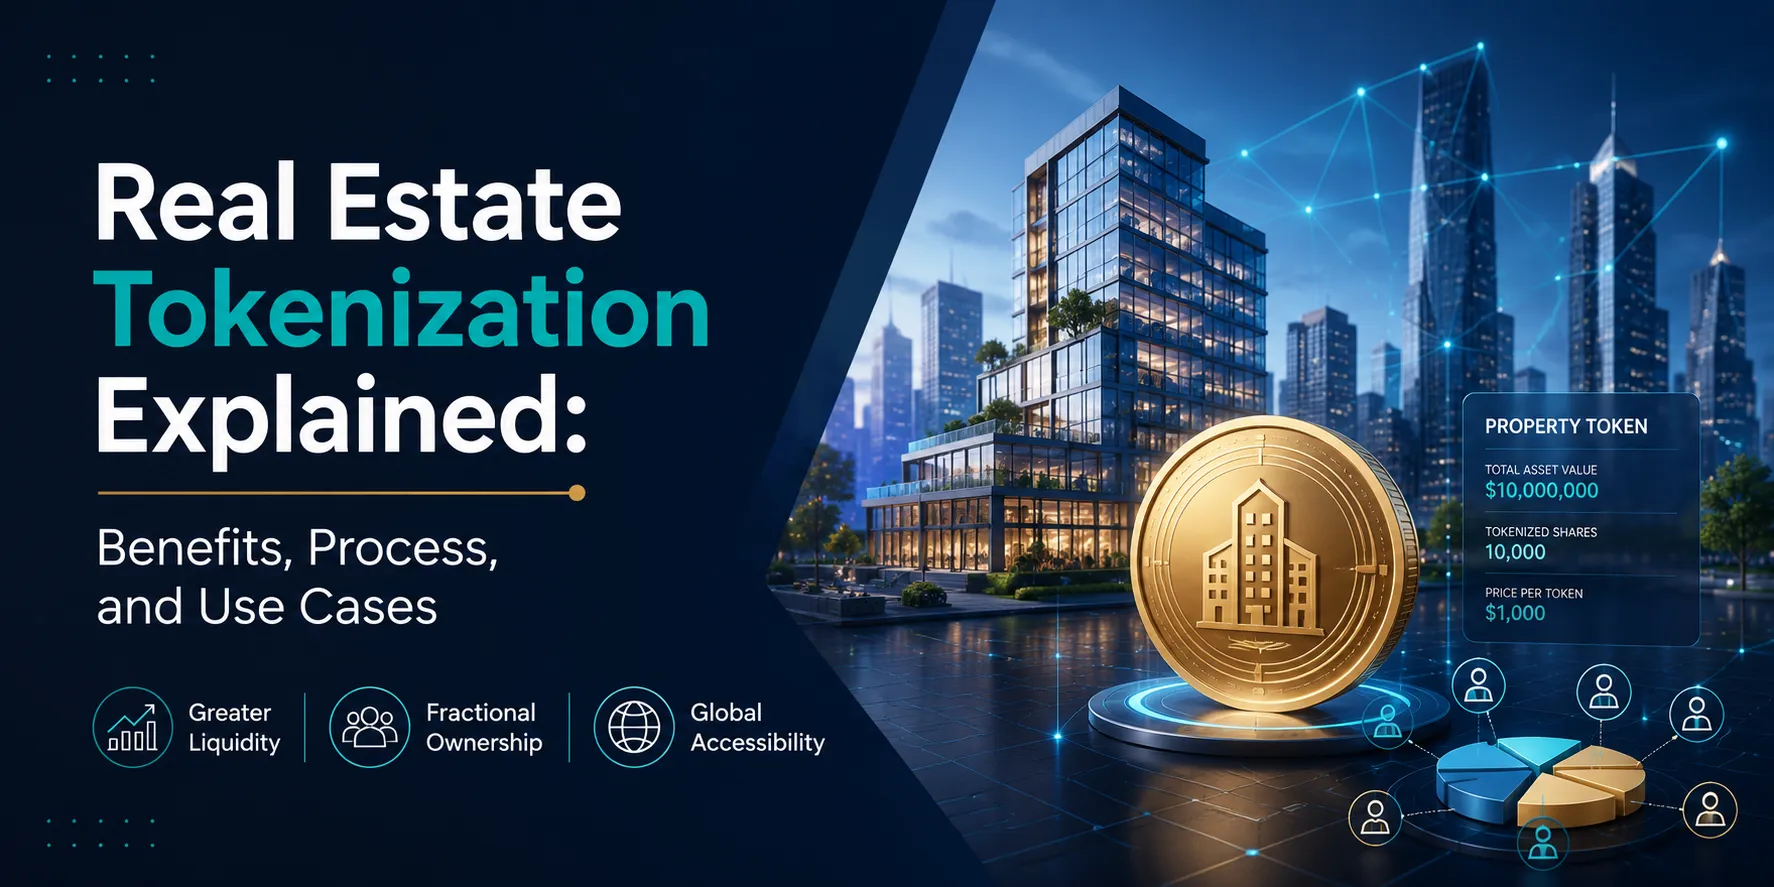
For example, imagine a commercial property valued at $10 million. Instead of selling the entire property to one investor, the owner could establish a suitable legal entity and issue 100,000 tokens representing defined interests in the investment structure. An investor purchasing 1,000 tokens could therefore obtain exposure equivalent to 1% of the tokenized interest, subject to the legal terms.
This distinction is important because owning a token does not automatically mean owning the underlying property. The token's rights must be legally connected to the asset through enforceable agreements and the appropriate ownership structure.
The Bank for International Settlements describes tokenization as using distributed-ledger technology to issue or represent assets in digital form. It highlights potential benefits such as improved efficiency, reduced costs, transparency, and fractionalization, while also emphasizing regulatory and operational risks.
Why Are Businesses Tokenizing Real Estate?
The appeal of tokenization comes from its potential to address several structural limitations in traditional real estate investment.
First, tokenization can support fractional ownership. High-value properties that would traditionally be accessible only to wealthy individuals or institutions can potentially be divided into smaller investment units, depending on applicable securities and property laws.
Second, blockchain infrastructure can provide a shared digital record of transactions. Rather than relying entirely on disconnected databases maintained by different intermediaries, tokenized systems can record ownership and transfers on a common ledger.
Third, smart contracts can automate selected processes. Distribution rules, transfer restrictions, investor eligibility checks, corporate actions, and other conditions can potentially be incorporated into the digital infrastructure.
Fourth, tokenization may create new possibilities for liquidity. Real estate itself remains relatively illiquid, but tokenized interests can potentially be transferred through compliant secondary markets. This does not guarantee liquidity; an active market, eligible buyers, appropriate regulation, and suitable infrastructure are still necessary.
Deloitte identifies tokenized private real estate funds, tokenized ownership of loans and securitizations, and tokenized ownership of undeveloped or under-construction projects as important areas of potential growth.
How Does Real Estate Tokenization Work? Step-by-Step
Step 1: Select and Evaluate the Real Estate Asset
The process begins with identifying the property or real estate portfolio to be tokenized.
It could be a residential building, office complex, hotel, retail property, industrial facility, development project, mortgage portfolio, or real estate investment fund. Businesses need to determine whether the asset has sufficient economic value and a suitable ownership structure for tokenization.
Due diligence is critical at this stage. The property may need to be evaluated for:
- Legal ownership and title
- Existing mortgages or liens
- Property valuation
- Rental income and operating expenses
- Tax obligations
- Insurance
- Existing leases
- Regulatory restrictions
- Development or zoning requirements
Tokenization does not eliminate traditional real estate due diligence. Instead, it adds a digital layer on top of it.
Step 2: Establish the Legal and Ownership Structure
This is one of the most important stages of the entire process.
A business must determine exactly what the token represents. For example, tokens could represent equity in an SPV that owns a property, an interest in a real estate fund, a debt claim secured by real estate, or another legally structured financial interest.
The legal structure determines investor rights, revenue distribution, voting rights, transfer restrictions, redemption provisions, and what happens if the property is sold or the issuer defaults.
This is also where jurisdiction becomes critical. A token that represents an investment interest may fall under securities regulations depending on the jurisdiction and structure. The U.S. Securities and Exchange Commission, for example, stated in January 2026 that tokenized securities can be securities represented through crypto assets, with different models providing different rights to holders.
Therefore, legal counsel and regulatory specialists should be involved before tokens are issued.
Step 3: Determine the Token Economics
Once the legal framework is established, the issuer decides how the tokenized investment will work economically.
Suppose a property is valued at $20 million and the issuer intends to tokenize $10 million of equity. The business could establish a defined number of tokens and determine the value represented by each unit.
The token model may specify:
- Total token supply
- Initial token price
- Minimum investment
- Investor eligibility
- Revenue-sharing mechanism
- Voting rights
- Lock-up periods
- Transfer restrictions
- Redemption conditions
- Fees
- Distribution schedules
The objective is to make the economic relationship between the property, the legal entity, and the token completely clear.
Step 4: Conduct Valuation and Financial Structuring
An independent or appropriately qualified valuation process helps establish the property's financial basis.
For income-generating properties, projected rental income, occupancy, operating expenses, capitalization rates, debt obligations, and market conditions may influence valuation.
For development projects, the model may consider construction costs, projected sales values, financing requirements, development timelines, and expected returns.
This information becomes part of the investment proposition. Investors need enough information to understand what they are purchasing and what risks they are assuming.
Step 5: Develop the Smart Contract
The next stage involves creating the blockchain infrastructure that governs the tokens.
A smart contract can define how tokens are issued, transferred, burned, or restricted. In regulated real estate projects, transfer rules may prevent tokens from being sent to wallets that have not completed required investor verification.
Smart contracts can also support automated processes such as distributions or compliance-related restrictions.
The Bank for International Settlements notes that tokenization can combine asset information with rules and governance on programmable platforms, allowing certain transactions to execute automatically when predefined conditions are met.
Because smart contracts can control valuable assets and investor rights, security testing and independent auditing are essential. A coding error can create consequences that are difficult to reverse, particularly when blockchain transactions are designed to be immutable.
Step 6: Complete KYC, AML, and Investor Compliance
Real estate tokenization does not mean investors can simply connect a wallet and purchase any property anonymously.
Depending on the structure and jurisdiction, businesses may need Know Your Customer (KYC), Anti-Money Laundering (AML), investor accreditation or suitability checks, sanctions screening, tax documentation, and other compliance processes.
A compliant platform therefore needs an investor onboarding system capable of verifying participants before allowing them to acquire or transfer relevant tokens.
This is particularly important for security-token structures because regulatory obligations may continue after the initial issuance.
Step 7: Issue the Real Estate Tokens
After legal, financial, technical, and compliance requirements are completed, the tokens can be issued.
The issuance can occur through a dedicated tokenization platform or blockchain infrastructure. Investors may purchase tokens using traditional currency, stablecoins, or other approved settlement mechanisms, depending on the platform and regulatory framework.
The token issuance should be directly connected to the legal documentation establishing what the tokens represent.
For example, if an SPV legally owns a property and investors hold tokenized equity interests in that SPV, the documentation needs to establish the relationship between token ownership and the investor's rights.
Step 8: Manage the Property and Distribute Returns
Tokenization does not remove the need for traditional property management.
Tenants still need to pay rent. Buildings require maintenance. Taxes and insurance still have to be paid. Property managers still need to operate the asset.
The difference is that certain investor-facing processes can be digitized.
For an income-generating property, rental revenue could flow through the established legal and financial structure, with eligible distributions calculated according to the token holders' rights.
This can make investor reporting and distribution processes more systematic, although actual implementation depends on the legal and financial architecture.
Step 9: Enable Compliant Secondary Trading
One of the most frequently discussed advantages of tokenization is potential secondary-market liquidity.
Instead of waiting for the entire property to be sold, investors may eventually be able to transfer their tokenized interests to eligible buyers through a compliant secondary marketplace.
However, tokenization should not be marketed as a guarantee that real estate becomes instantly liquid.
Liquidity depends on market demand, regulatory permissions, trading infrastructure, investor eligibility, pricing transparency, and the willingness of buyers and sellers to transact.
The OECD identifies improved liquidity potential and tradability among the possible benefits of tokenization while also recognizing regulatory and market-adoption challenges.
A Practical Example of Real Estate Tokenization
Consider a company that owns a $5 million apartment building generating rental income.
Instead of selling the entire building, the company establishes an appropriate legal entity and creates 50,000 tokens representing defined equity interests in that entity.
An investor purchasing 500 tokens would hold a 1% interest in the tokenized equity pool, assuming the structure assigns proportional rights.
Rental income, after applicable expenses and according to the offering terms, could be distributed to eligible token holders. If the property is eventually sold, the proceeds could be allocated according to the rights attached to the tokens.
The blockchain records token ownership and transfers, while the legal agreements establish the actual relationship between the tokens, investors, and property.
This example illustrates an important principle: blockchain provides the digital infrastructure, but legal agreements provide the foundation for enforceable ownership and economic rights.
Benefits of Real Estate Tokenization for Investors
For investors, the most significant attraction is potentially lower barriers to participation. Fractionalization can allow investors to gain exposure to properties without purchasing an entire building.
Tokenization can also improve transparency because transaction records and certain asset information can be made accessible through blockchain infrastructure.
Another potential advantage is programmability. Automated distribution mechanisms and compliance rules can reduce some administrative processes.
Investors may also gain access to more diversified opportunities. Instead of allocating a large amount of capital to one property, an investor could potentially distribute smaller investments across multiple tokenized assets, subject to platform availability and investment restrictions.
However, investors should not confuse technological convenience with reduced investment risk. Tokenized real estate remains exposed to property-market risk, interest-rate changes, vacancies, operational costs, valuation uncertainty, regulatory changes, and platform or smart-contract risks.
Benefits for Real Estate Businesses
For property owners and investment managers, tokenization can potentially broaden the investor base and create alternative fundraising structures.
Businesses can potentially structure portfolios around different investor preferences, such as geographic location, property type, income characteristics, or sustainability objectives.
Deloitte notes that tokenization could enable institutional investors to create customized portfolios using tokens aligned with particular investment strategies.
Tokenization may also reduce certain administrative inefficiencies by integrating issuance, ownership records, compliance rules, and selected financial processes into digital infrastructure.
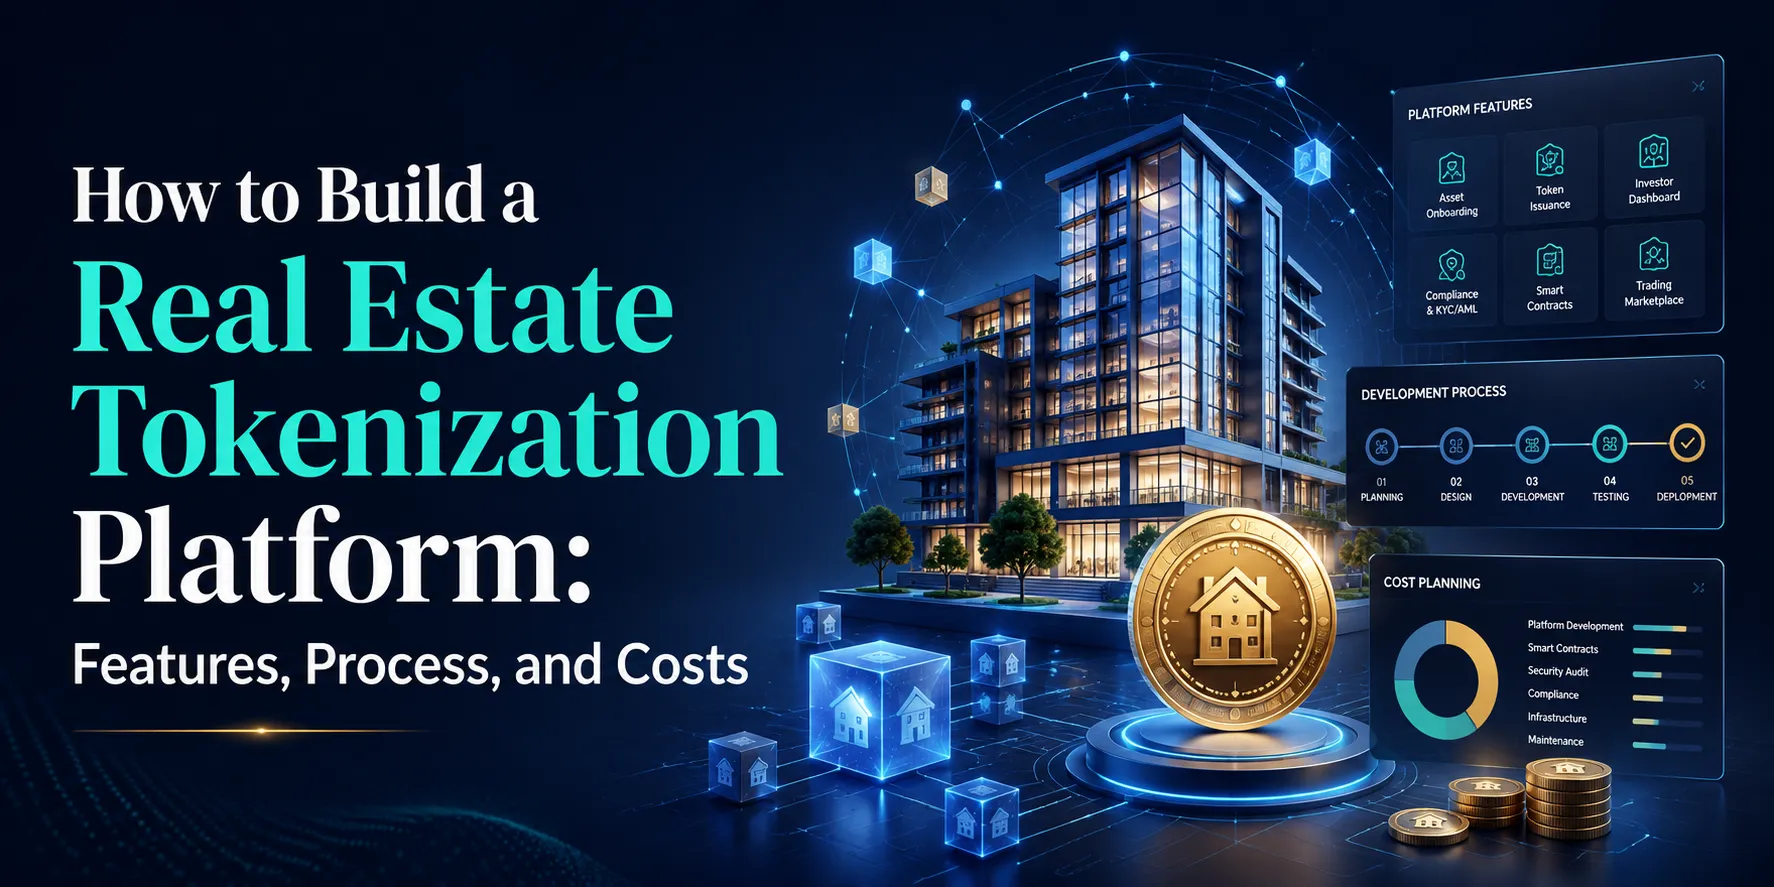
For businesses considering Property tokenization development services, the focus should therefore extend beyond token creation. A successful platform requires legal architecture, investor management, smart contracts, compliance systems, property-data integration, payment infrastructure, and potentially secondary-market functionality.
Key Risks and Challenges
Despite its potential, real estate tokenization has significant challenges.
Regulatory uncertainty remains one of the biggest concerns because token classification and investor requirements vary across jurisdictions.
Legal enforceability is equally important. A blockchain record alone does not automatically establish ownership of physical property.
Liquidity risk should also be considered. A token may be technically transferable without having an active market.
Smart-contract vulnerabilities can result in financial losses or operational failures.
Oracle and data risks can emerge when blockchain systems rely on external information such as property valuations, rental income, or asset status.
The BIS has highlighted risks involving third-party service providers, liquidity and maturity mismatches, leverage, asset valuation, interconnectedness, and operational fragilities in tokenized systems.
Consequently, businesses should approach tokenization as a combination of real estate, financial structuring, legal compliance, and blockchain engineering, rather than as a purely technical project.
What Should Investors Check Before Buying Tokenized Real Estate?
Investors should investigate the underlying property and the token structure before committing capital. Key questions include:
- Who legally owns the property?
- What exactly does the token represent?
- Are token-holder rights legally enforceable?
- How are rental income and other returns distributed?
- What fees does the platform charge?
- What happens if the property value declines?
- Can tokens be transferred, and to whom?
- Is there an actual secondary market?
- Who controls the smart contracts?
- Has the smart contract undergone an independent security audit?
- What happens if the platform or issuer fails?
These questions help distinguish a properly structured tokenized real estate investment from a project that simply places a digital token around an unclear investment proposition.
The Future of Real Estate Tokenization
The long-term opportunity is potentially significant. Deloitte's projection of $4 trillion in tokenized real estate by 2035 illustrates the scale that industry analysts believe could emerge if regulatory frameworks, infrastructure, and investor adoption develop successfully.
The next phase is likely to involve greater integration between blockchain networks and traditional financial infrastructure. Tokenized funds, digital securities, automated distributions, compliant secondary markets, and interoperable settlement systems could gradually make tokenization more practical.
At the same time, regulators and financial institutions are likely to place greater emphasis on investor protection, custody, transparency, settlement, and operational resilience. The BIS has emphasized that tokenization's benefits must be balanced against governance, legal, liquidity, and operational risks.
The most successful platforms will therefore not simply focus on issuing tokens. They will build systems in which the legal rights, financial economics, blockchain records, compliance mechanisms, and real-world asset management processes remain synchronized.
Conclusion
Real estate tokenization works by connecting a legally structured real estate investment with blockchain-based digital tokens that represent defined ownership or economic rights. From selecting and valuing the property to establishing the legal structure, designing token economics, developing smart contracts, completing investor verification, issuing tokens, distributing returns, and potentially enabling secondary trading, every stage must work together to create a credible investment ecosystem. For businesses exploring Real estate asset tokenization services, choosing an experienced technology partner is essential because the project requires more than basic blockchain development. Blockchain App Factory provides best services for real estate tokenization, combining blockchain development, smart contract implementation, token infrastructure, and platform development capabilities to help businesses build secure and scalable tokenization solutions.









Sign in to leave a comment.