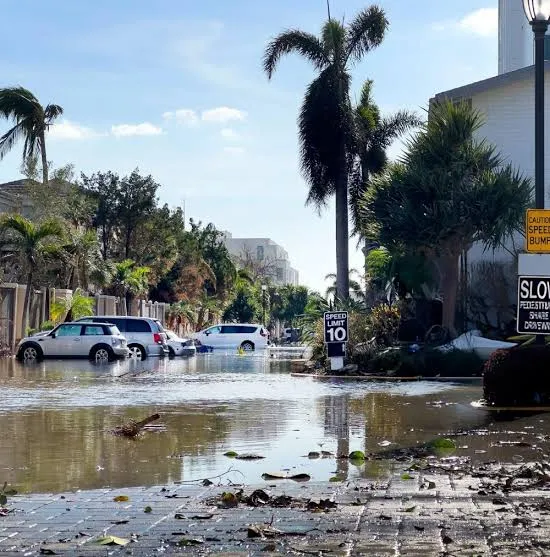

Florida's property insurance market has gone through a turbulent stretch over the past several years. Several carriers have exited the state or gone insolvent, and premiums have climbed sharply. Homeowners have grown noticeably more cautious about how they handle claims.
This caution starts from the very beginning of the process. That shift affects how people research a public adjuster in Tampa today compared to just a few years ago. What used to be a decision made mostly after a major storm has changed.
It has increasingly become a decision homeowners think through in advance, well before any damage actually occurs to their property.
What's Driving the Change
Insurer instability sits at the center of this broader shift. State regulators placed multiple property insurers into receivership following the 2022 hurricane season. That is according to a stability report from Florida's Office of Insurance Regulation.
When a carrier becomes insolvent, existing claims can face delays or transfer entirely to a state guaranty association. Premium increases have compounded this pressure significantly. Florida homeowners now pay some of the highest property insurance premiums in the country.
That is nearly three times the national average, according to the Insurance Information Institute. Paying significantly more for coverage has made many homeowners far more attentive. They now pay closer attention to how thoroughly their claims get handled once damage actually occurs.
Legislative changes have also reshaped the landscape during this same period. State lawmakers passed reforms in 2022 and 2023 aimed at stabilizing the property insurance market. Those reforms have since influenced how insurers price policies.
They have also shaped how quickly new carriers have entered or reentered the state.
Who It Affects and How
Every homeowner with property coverage in the state feels some version of this shift. The effect is strongest for people who have never had to file a claim before this period. They are entering a market shaped by years of instability.
They have no personal frame of reference for what a normal claims process is even supposed to look like. Longtime residents who filed claims a decade ago are also adjusting their expectations. The process, the insurer landscape, and the average premium have all changed substantially.
All of that has changed since their last experience with a claim.
Renters and condominium owners are not exempt from this shift either. Association-level policies and individual unit coverage have both been affected by the same market pressures. The exposure still looks different from that of a single-family homeowner.
Small business owners with commercial property coverage have noticed similar volatility. That volatility shows up in their own renewal quotes over the same stretch of years. None of these groups are positioned identically.
But all of them are navigating a market that behaves differently than it did before this period of instability began.
What to Do, and What Not to Do
Homeowners should avoid assuming their current insurer will remain in the same financial position indefinitely. Many carriers have changed status in recent years. Periodically confirming a carrier's standing is a reasonable precaution.
This information is usually publicly available, and checking it is not an overreaction to normal market conditions. Homeowners should not, however, let market anxiety push them into panic decisions. That applies to decisions about coverage or claims made without reviewing their specific policy first.
Broad market trends can inform good decisions. They do not replace the need to read the actual contract that governs a specific claim.
Switching insurers reflexively, without comparing actual coverage terms, is another decision worth slowing down for. A lower premium from a new, less established carrier is not automatically a better deal. Financial stability and claims-handling reputation both factor into that comparison.
Practical Steps for Adapting
Reviewing policy terms annually, rather than only after damage occurs, helps homeowners stay oriented. Market conditions continue to shift around them. Keeping thorough home documentation year-round, not just after a storm, reduces how much scrambling any future claim eventually requires.
Researching a carrier's financial history before renewing or switching policies adds one more layer of informed decision-making to the process. Comparing notes with neighbors or local community groups about recent claims experiences can also help. It can surface useful, practical information that official sources sometimes miss.
Setting aside a modest reserve for deductibles and short-term expenses, when a household budget allows for it, helps. This further reduces the financial shock of an unexpected claim in an uncertain market.
Conclusion
Florida's insurance market volatility has changed the emotional and practical starting point for a lot of homeowners. That change happens well before any claim ever gets filed. Interest in working with a public adjuster in Tampa now often begins earlier in the process.
That shift is driven by a market that has taught people to prepare rather than simply react. Where this trend goes next likely depends on whether the state's insurer market eventually stabilizes. Either way, the habits of documentation and early policy review are worth keeping.
This volatility has encouraged those habits regardless of what happens to the broader market in the years ahead.























Sign in to leave a comment.