
Most people don't think about their insurance policy until the renewal notice arrives.
The bill shows up. The price looks a little higher than last year. You might sigh, make the payment, and move on.
But here's the thing: your insurance policy isn't supposed to be a "set it and forget it" purchase. Your vehicle changes. Your mileage changes. Your household changes. Your financial situation changes. Even the way you use your car can change from one year to the next.
Yet the policy often stays exactly the same.
That's why one thorough policy review can sometimes make a bigger difference than drivers expect. It may uncover discounts they weren't receiving, coverage they no longer need, or—just as importantly—areas where they may actually need stronger protection.
The goal isn't simply to make the premium smaller. It's to make sure you're paying for insurance that still makes sense for your life.
Your Policy May Be Based on an Older Version of Your Life
Think about where you were when you first purchased your current policy.
Maybe you drove to work every day. Perhaps you had a different vehicle, lived in another neighborhood, or had fewer drivers in your household. Maybe you were commuting long distances and now work primarily from home.
Insurance doesn't automatically know when those things change.
That's why a policy review matters. It gives you an opportunity to update the information your insurer uses and make sure your coverage reflects your current circumstances.
A policy built around yesterday's lifestyle may not be the most cost-effective policy for today.
Start With the Most Important Question: What Has Changed?
A useful insurance review begins with a simple conversation:
"What's different since the last time we reviewed this policy?"
That question can uncover a surprising number of potential adjustments.
Have you:
- Bought or sold a vehicle?
- Changed your daily commute?
- Started working remotely?
- Reduced the number of miles you drive?
- Added or removed a household driver?
- Moved?
- Paid off an auto loan?
- Added safety or anti-theft technology to your vehicle?
- Changed your financial priorities?
- Purchased another insurance policy that could potentially be bundled?
Even one of these changes could justify taking another look.
Mileage Can Be an Overlooked Factor
Your driving habits are not necessarily the same as they were a few years ago.
Remote work, hybrid schedules, job changes, and lifestyle adjustments have caused many drivers to spend less time behind the wheel.
If your annual mileage has dropped significantly, it's worth asking your insurance professional whether that change could affect your premium.
The important part is accuracy. Never report an artificially low mileage figure just to chase a cheaper rate. Your insurance information should reflect your actual usage.
But if your circumstances genuinely changed, your policy should have a chance to catch up.
The Drivers on Your Policy Deserve a Second Look
Households are constantly evolving.
A teenager may have recently earned a license. An adult child may have moved out. A spouse may have changed jobs. Someone who once regularly used your vehicle may no longer drive it.
These changes can affect how your policy should be structured.
This is also an area where guessing can create problems. Simply removing someone from a policy because they don't drive frequently may not be appropriate depending on your insurer's rules and household circumstances.
A policy review gives you the opportunity to explain what's changed and let your insurance professional determine what needs to be updated.
Your Deductible Could Be Worth Revisiting
Your deductible is another piece of the policy that can quietly remain unchanged for years.
A higher deductible can sometimes reduce your premium, while a lower deductible generally means you'll pay less out of pocket if you have a covered claim.
But the right choice depends on your financial situation.
If you have enough savings to comfortably handle a higher deductible, you may want to explore whether changing it could reduce your premium. If paying a large unexpected amount would put serious pressure on your budget, a lower deductible may provide more practical protection.
There's no universally "best" deductible.
There's only the deductible that makes sense for you.
Don't Remove Coverage Without Understanding the Consequences
This is where insurance cost-cutting can go wrong.
When premiums increase, the natural reaction is to look for something to remove. But eliminating coverage without understanding what you're giving up can create a much bigger financial problem later.
For example, liability coverage protects you when you're legally responsible for injuries or property damage. Collision coverage can help with damage to your vehicle from covered accidents. Comprehensive coverage can address certain non-collision losses such as theft, vandalism, or weather-related damage, subject to the policy terms.
Reducing or removing coverage should be an informed decision—not simply a reaction to a higher bill.
Look for Discounts You May Have Missed
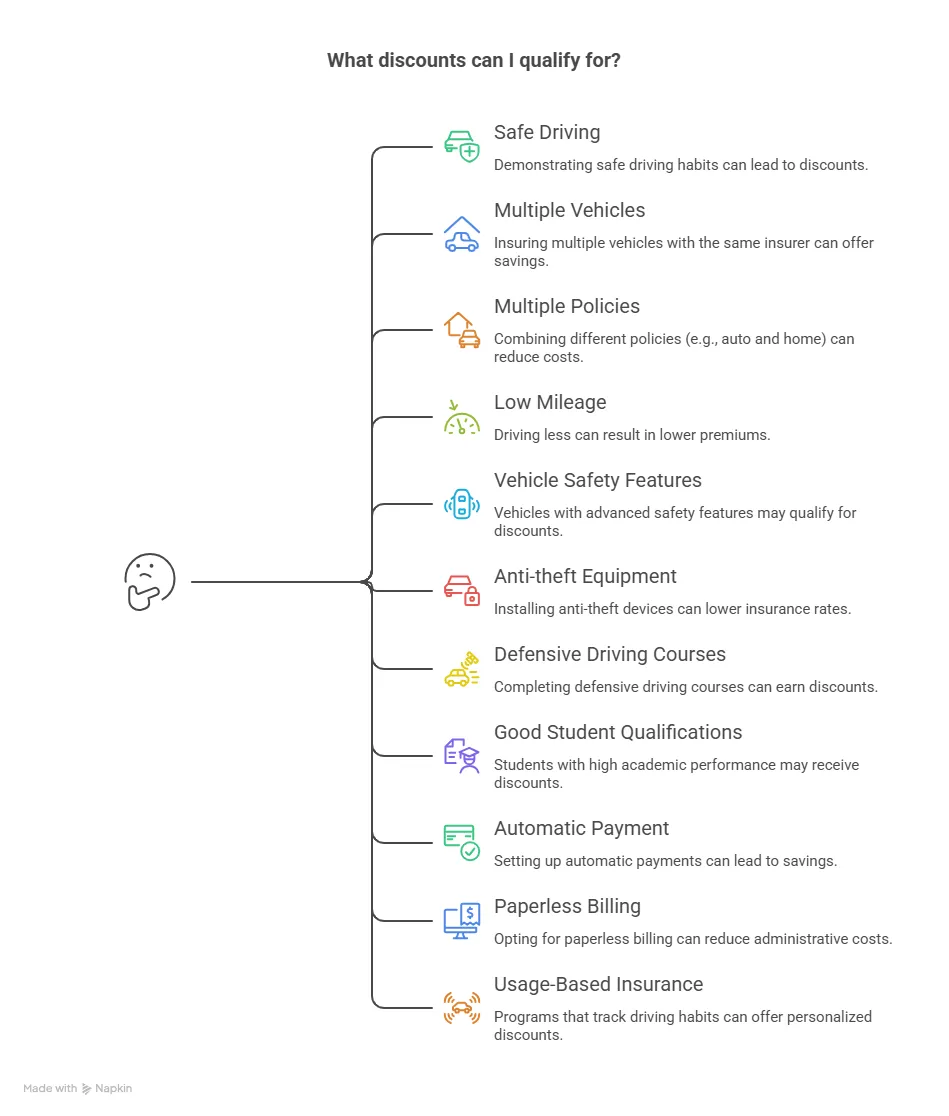
One of the most productive parts of a policy review is asking about available discounts.
Depending on the insurer and your circumstances, you may qualify for savings related to:
- Safe driving
- Multiple vehicles
- Multiple policies
- Low mileage
- Vehicle safety features
- Anti-theft equipment
- Defensive driving courses
- Good student qualifications
- Automatic payment
- Paperless billing
- Usage-based insurance programs
The challenge is that eligibility can change.
A discount you didn't qualify for several years ago might now apply. Conversely, a discount you once received may no longer be available if your circumstances have changed.
That's another reason an annual review is worthwhile.
Your Vehicle May Have Changed More Than You Realize
Today's vehicles are increasingly sophisticated.
Advanced driver-assistance systems, cameras, sensors, connected technology, and anti-theft features can change both the value of a vehicle and the way it is repaired.
If you've purchased a newer vehicle, don't assume your previous policy structure is automatically ideal for it.
A policy review can help ensure that vehicle information, coverage, deductibles, and applicable discounts are accurate.
It can also be a good opportunity to discuss whether additional protection makes sense for a financed or leased vehicle.
Don't Forget About Optional Coverage
Optional coverage can be extremely useful—but not every driver needs every option.
During a policy review, go through each endorsement and additional service and ask:
"Do I still need this?"
Maybe you have roadside assistance through another membership. Perhaps you rarely need rental transportation and have other options available. Or maybe an optional protection that once seemed unnecessary has become more valuable because your circumstances changed.
The answer won't be the same for everyone.
The important thing is knowing what you're paying for and why.
Compare the Total Value, Not Just the Premium
Shopping around can be helpful, particularly when rates have changed.
But comparing insurance based solely on the monthly price can produce misleading results.
Imagine one quote costs less but has lower liability limits and significantly higher out-of-pocket costs. Another costs slightly more but provides substantially stronger protection.
Which one is actually cheaper?
That's the question consumers should ask.
A good comparison looks at coverage limits, deductibles, exclusions, available benefits, customer service, claims experience, and overall value—not just the number at the bottom of the quote.
Loyalty Is Convenient, But Review the Market Anyway
Staying with the same insurer can be convenient. You already have an account, payment information is established, and you know where to call.
But convenience shouldn't mean never checking your options.
An insurance review doesn't automatically mean switching companies. Sometimes the review confirms that your current provider remains competitive.
Other times, it may reveal another option worth considering.
Either way, having current information puts you in a stronger position.
Local Guidance Can Make the Review Easier
Insurance can become complicated quickly. Policy language isn't always written in the way ordinary consumers speak, and it can be difficult to know which changes matter most.
That's where an experienced Insurance Agency can be helpful.
Rather than simply handing you a quote, a good insurance professional can walk through your current policy, ask about recent changes, explain coverage options, and help you understand where reducing costs may be reasonable—and where cutting too deeply could leave you exposed.
For drivers searching for an Insurance Company near Inkster, Michigan, local guidance can also make the process more personal and convenient, particularly when you want to discuss your circumstances rather than simply enter information into an online quote form.
Sometimes the Best Result Isn't a Lower Premium
This is an important point that gets overlooked.
A successful policy review doesn't always end with a lower price.
Sometimes the review reveals that you are already getting a competitive rate.
Sometimes you discover a discount.
Sometimes you remove an unnecessary option.
And sometimes the review shows that you actually need more coverage.
That last outcome isn't necessarily bad news.
If your vehicle has increased in value, your household has changed, or your financial exposure has grown, discovering a coverage gap before an accident is far better than discovering it afterward.
The real win is making an informed decision.
A Policy Review Can Protect More Than Your Monthly Budget
Insurance is ultimately about managing financial risk.
Saving a few dollars each month is useful, but protecting yourself from a potentially devastating financial loss is the bigger objective.
That's why smart insurance reviews balance two questions:
"Am I paying too much?"
and
"Am I adequately protected?"
You need both questions.
Focusing only on price can lead to underinsurance. Focusing only on maximum coverage can mean paying for protections that don't fit your circumstances.
The sweet spot is a policy that provides meaningful protection at a price that fits your budget.
Make the Review an Annual Financial Habit
You don't have to wait for a major life event to review your insurance.
Set aside a little time each year before renewal. Have your current policy available and make a quick list of what's changed.
Then discuss those changes with your insurance professional.
It doesn't need to be complicated. A focused review can cover your vehicles, drivers, mileage, deductibles, coverage limits, discounts, optional protections, and overall premium.
That relatively small investment of time can reveal opportunities you might otherwise miss.
The Bottom Line
Insurance costs can change for many reasons, but that doesn't mean you should simply accept every renewal price without asking questions.
One thoughtful policy review can reveal a different story.
You may discover that your mileage has dropped, a new discount is available, an optional feature is no longer necessary, your deductible could be adjusted, or another insurer offers better value. Just as importantly, you may discover that your current coverage is exactly where it needs to be—or that certain protections should actually be increased.
The smartest approach isn't to chase the cheapest insurance policy.
It's to understand your policy well enough to know what you're paying for, why you're paying for it, and whether it still fits your life.
In 2026, that's what a meaningful insurance review should look like: less guesswork, fewer unnecessary expenses, and coverage that keeps pace with the person behind the wheel.



















Sign in to leave a comment.