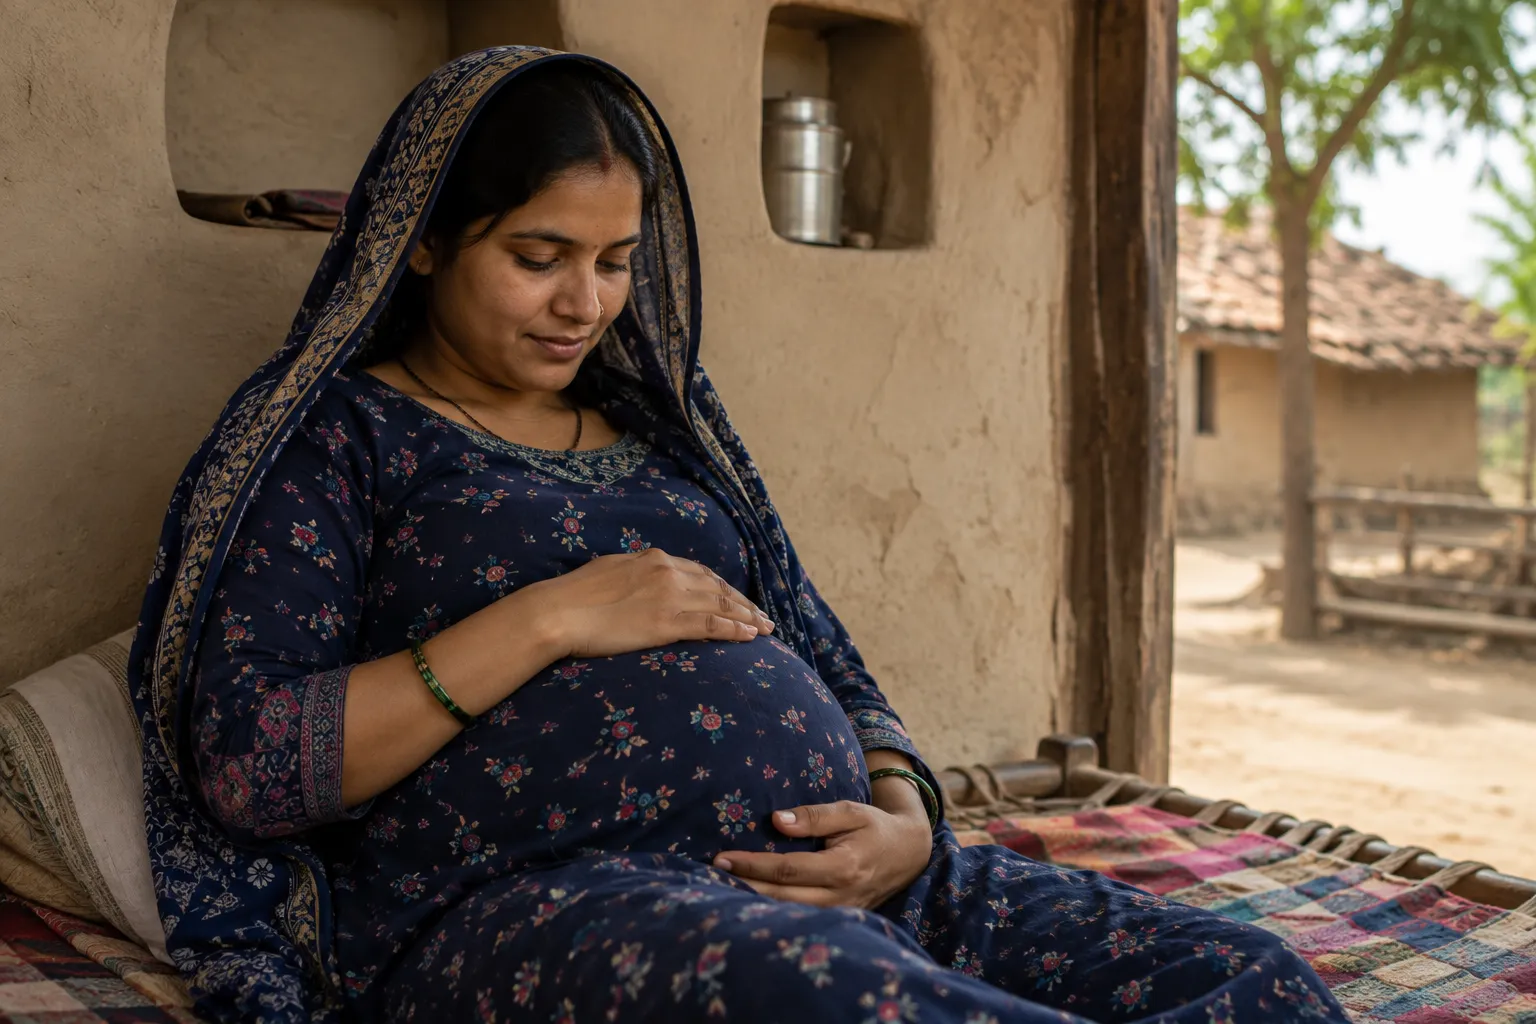
Pregnancy is usually treated as a temporary phase of healthcare, but complications during pregnancy can sometimes have implications that extend beyond delivery. Conditions such as gestational diabetes, pregnancy-induced hypertension, pre-eclampsia, premature delivery or complications requiring surgery may become part of a person's medical history.
This can raise an important financial planning question: can pregnancy complications affect the cost or availability of health insurance in the future?
The answer depends on the nature of the complication, whether it has resolved, the applicant's current health, medical history and the underwriting terms of the policy. A pregnancy-related complication does not automatically mean higher premiums. However, insurers may consider relevant medical information when assessing future applications or coverage.
Understanding this relationship can help women make better decisions about insurance before, during and after pregnancy.
Can Pregnancy Complications Affect Future Health Insurance?
A previous pregnancy complication may influence the underwriting assessment when a person applies for a new health insurance policy. Insurers generally evaluate the applicant's health profile based on disclosed medical history and the terms of the product.
The impact depends largely on whether the complication was temporary or has resulted in an ongoing medical condition.
For example, gestational diabetes often resolves after delivery, although some women may remain at increased risk of developing type 2 diabetes later. Similarly, pregnancy-related hypertension may disappear after childbirth but can warrant continued monitoring.
If a condition has completely resolved and there is no ongoing treatment or diagnosis, it may have less impact on future underwriting than a condition that continues after pregnancy.
Which Pregnancy Complications May Matter to Insurers?
Not every complication will affect future insurance pricing. Insurers may focus more closely on conditions that indicate an ongoing or increased risk of future healthcare requirements.
Gestational Diabetes
Gestational diabetes develops during pregnancy and commonly requires dietary changes, monitoring or medication. Although blood sugar levels may return to normal after delivery, some women may remain at higher risk of diabetes in the future.
When applying for a new policy, an insurer may consider previous gestational diabetes alongside current blood sugar levels, medical reports and any ongoing treatment.
Pregnancy-Induced Hypertension
High blood pressure during pregnancy may resolve after childbirth. However, persistent hypertension can become a long-term health concern.
If blood pressure remains elevated after delivery, it may be assessed as an ongoing medical condition rather than simply a past pregnancy complication.
Pre-Eclampsia
Pre-eclampsia involves high blood pressure and other complications during pregnancy and requires medical monitoring. A history of pre-eclampsia may be relevant during future underwriting, particularly if there are continuing cardiovascular or blood pressure concerns.
Caesarean Section and Surgical Complications
A caesarean section by itself does not necessarily indicate a higher long-term health risk. However, complications associated with surgery, prolonged hospitalisation or subsequent treatment may become relevant to an insurer's assessment.
The distinction between a routine procedure and a significant ongoing medical issue is therefore important.
Premature Delivery
Premature delivery may involve significant medical care for the mother or baby. Whether it affects the mother's future insurance assessment generally depends on the medical circumstances and whether there are continuing health concerns.
Does a Past Complication Automatically Increase the Premium?
No. A previous pregnancy complication does not automatically result in a higher premium.
Insurance underwriting considers an individual's overall risk rather than simply identifying whether a complication occurred during pregnancy.
Factors that may be relevant include:
- Current health status
- Age
- Medical history
- Existing conditions
- Ongoing medication
- Previous hospitalisation
- Test results
- Family medical history, where relevant to underwriting
- Lifestyle and other declared risk factors
- The type and extent of coverage requested
For example, a woman who experienced gestational diabetes during pregnancy but has normal blood sugar levels after delivery and requires no ongoing treatment may be assessed differently from someone who subsequently develops diabetes.
How Does Pregnancy Medical Insurance Differ From Regular Health Cover?
Pregnancy Medical Insurance generally refers to insurance benefits designed to cover eligible maternity-related expenses, subject to the specific policy terms.
Maternity benefits may include eligible expenses relating to pregnancy, childbirth and, in some policies, newborn care. Waiting periods are commonly relevant, making advance planning important for people who intend to start a family.
Regular health insurance, meanwhile, is designed to provide broader protection against eligible illnesses, injuries and hospitalisation. A maternity benefit should therefore not be viewed as a substitute for comprehensive health insurance.
Understanding the distinction is particularly important after a complicated pregnancy. The maternity episode may have ended, but any resulting health condition could continue to require medical care.
Can a Complication Lead to a Waiting Period?
A waiting period may apply when a condition is considered pre-existing under the policy's definition.
For instance, if a woman develops persistent hypertension following pregnancy and purchases a new policy after the condition has been diagnosed, the insurer may treat hypertension as a pre-existing condition depending on the relevant policy terms.
The waiting period does not necessarily mean that the entire health insurance policy becomes unavailable. It may instead affect claims related to the specified condition during the applicable period.
This is why applicants should read the policy's pre-existing disease provisions carefully rather than assuming that a past pregnancy complication will affect every aspect of their coverage.
Why Medical Disclosure Is Important After Pregnancy
Accurate disclosure is one of the most important aspects of buying health insurance after a complicated pregnancy.
Applicants should provide relevant information about previous diagnoses, hospitalisation, surgeries, medicines and ongoing treatment when required by the proposal form.
For example, if a woman was diagnosed with gestational diabetes and subsequently developed diabetes requiring regular medication, the later condition should not be treated as merely a historical pregnancy event.
Providing complete information allows the insurer to assess the application based on the available medical facts. It can also reduce the possibility of disputes during a future claim.
Can a Family Policy Be Affected?
A family health insurance policy can cover multiple members, subject to its eligibility and underwriting conditions. A pregnancy complication affecting one member does not necessarily mean that every family member will face higher premiums.
However, the insurer may assess the health profile of the individual being insured. The structure of the policy also matters.
A best mediclaim policy for family should therefore be evaluated based on more than the premium. Families should examine waiting periods, coverage limits, maternity benefits, pre-existing disease provisions, hospitalisation coverage and renewal terms.
For women planning future pregnancies, it can also be useful to understand whether maternity benefits have waiting periods and whether complications arising during pregnancy are subject to specific exclusions or limits.
How Can Women Reduce Future Insurance Uncertainty?
The best approach is to maintain continuous health insurance rather than waiting until a medical issue arises.
Buying cover when you are healthy can help establish long-term insurance continuity. Existing policies may also have provisions that differ from those applicable when purchasing a completely new policy after a medical condition has developed.
Maintaining medical records is equally useful. Reports showing that a pregnancy-related condition has resolved can provide relevant evidence during future underwriting.
Women should also attend recommended post-pregnancy health checks. Monitoring blood pressure, blood sugar and other relevant health indicators can help identify whether a pregnancy complication has genuinely resolved or requires continued management.
What Should You Check Before Buying or Renewing Cover?
Pre-Existing Disease Definition
Read how the policy defines a pre-existing disease and understand how previously diagnosed conditions are treated.
Waiting Periods
Check the duration of waiting periods applicable to pre-existing conditions and maternity benefits.
Maternity Benefits
If another pregnancy is planned, review eligibility, waiting periods, coverage limits and exclusions associated with maternity treatment.
Hospitalisation Coverage
Examine room-rent conditions, applicable sub-limits, day-care treatment and other restrictions that could affect future claims.
Renewal Provisions
Long-term continuity is valuable because a policy renewed over several years can provide financial protection without requiring the insured to start the underwriting process from scratch for every renewal, subject to applicable regulations and policy conditions.
Coverage Adequacy
A policy should reflect current healthcare costs and the family's financial responsibilities. The Best Health Insurance Plans In India should be compared on coverage and policy terms rather than premium alone.
Choosing the Right Policy After a Complicated Pregnancy
When comparing policies after pregnancy, it is useful to separate temporary pregnancy-related events from ongoing medical conditions.
For example, a woman who had pre-eclampsia but has normal blood pressure after delivery may have a different insurance profile from someone who continues to require antihypertensive medication.
The Best Health Insurance Plans In India for one person may therefore not be the most appropriate choice for another. Individual medical history, age, family requirements, sum insured, exclusions and waiting periods should all be considered.
When evaluating options, including products from Niva Bupa, applicants should read the relevant policy wording carefully and understand how existing or previous medical conditions are treated before purchasing cover.
Can Premiums Change Over Time?
Health insurance premiums can change for several reasons, and a previous pregnancy complication is only one potential consideration when a new policy is underwritten.
Age, product pricing, medical risk, coverage level and other applicable factors can influence premiums. A past pregnancy complication may become less relevant if it was temporary and the individual has remained healthy after recovery.
Conversely, if the complication has contributed to a continuing medical condition, that condition may remain relevant during future applications.
This is why maintaining good medical records and obtaining appropriate follow-up care can be valuable from both health and financial planning perspectives.
Conclusion
Pregnancy complications can sometimes influence future health insurance underwriting, but they do not automatically lead to higher premiums or make coverage unavailable.
The key consideration is whether the complication has resolved or resulted in an ongoing medical condition. Gestational diabetes, pregnancy-related hypertension, pre-eclampsia and significant surgical complications may receive closer attention when an insurer evaluates a person's health profile.
Women should disclose relevant medical information accurately, understand pre-existing disease provisions and review waiting periods before purchasing or changing cover. Maintaining continuous insurance and keeping post-pregnancy medical records can also support more informed financial planning.
Ultimately, the effect of a pregnancy complication on future insurance depends on the individual's current health and the specific policy terms. Comparing coverage carefully and understanding how medical history is assessed can help women secure appropriate protection for their future healthcare needs.










Sign in to leave a comment.