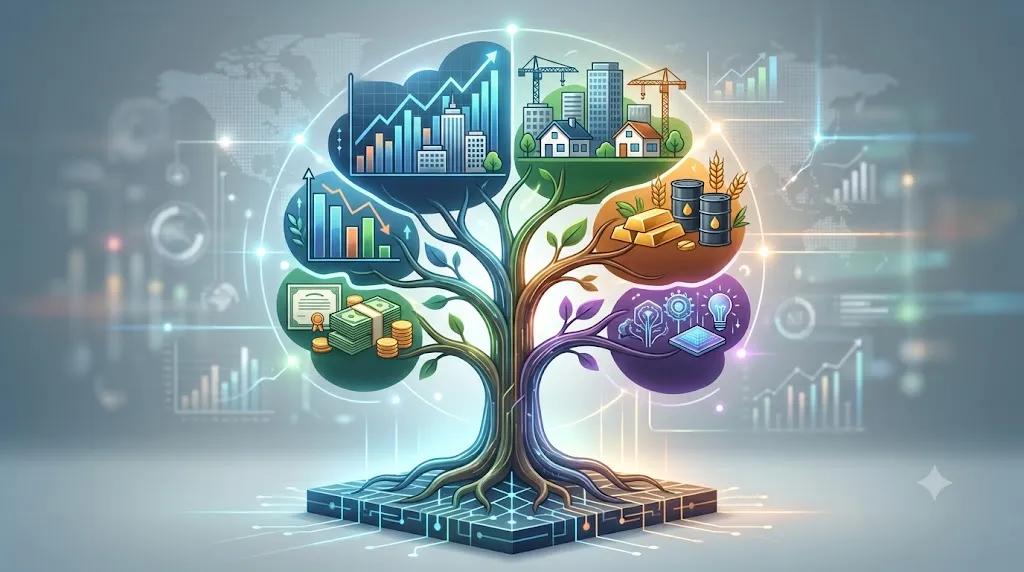

You've probably seen this play out, maybe even lived it. Someone hears about a "sure thing" stock, puts most of their savings into it, and for a while it feels smart. Then the stock has one bad quarter, and so does their entire portfolio.
Demat account opening is where this really begins. It's your first real step into the market. What happens after that, how you fill the account, decides whether you end up with something that can survive a bad day, or a portfolio that feels every single dip.
What Is Portfolio Diversification (and Why It Matters)
Portfolio diversification just means not putting every rupee in one place. Spread your money across different kinds of investments, and when one of them falls, the others can hold their ground or even climb.
There are two kinds of risk to keep in mind. Systematic risk hits the whole market at once, think interest rate hikes or a global slowdown, and no amount of diversification can shield you from that. Unsystematic risk is different. It belongs to one company or one sector, and this is exactly what diversification is built to soften.
Picture ₹1 lakh sitting entirely in one mid-cap stock. One bad quarter from that company, and your whole ₹1 lakh feels it. Now spread that same ₹1 lakh across five or six unrelated investments. Suddenly one company's bad quarter barely dents the total.
Step 1: Demat Account Opening, Your Investment Gateway
You can't buy a single share, mutual fund unit or bond in electronic form without a demat account. Think of it as a locker for your investments, the same way a bank account is a locker for your cash.
Demat account opening in India follows SEBI's KYC rules, and there are six details every account needs on file: your name, address, a PAN card linked to Aadhaar, a working mobile number, an email ID and your income range. Most brokers now handle this entirely online through e-KYC and a quick video verification call, so you can realistically finish this from your phone in a day.
If you're starting small, ask your broker about a Basic Services Demat Account. SEBI built this option specifically to keep annual maintenance charges low for investors with modest holdings.
Opening the account is step one, though, not the finish line. What you put inside it, and how you spread that out, is what decides whether you're diversified or just holding one bet dressed up differently.
The Building Blocks: Asset Classes to Diversify Across
Real asset allocation means drawing from more than one bucket. Equity, whether that's large, mid or small-cap stocks or equity mutual funds, is your growth engine over five years or longer. Debt and bonds pay fixed interest and keep things steady when equity gets choppy. Mutual funds and SIPs pool your money with everyone else's and let a professional spread it across stocks or bonds, so you don't have to pick individual names yourself. Gold, through an ETF or a sovereign gold bond, tends to move differently from equity and cushions you when markets fall. REITs give you a small, optional taste of real estate without buying property outright.
No single asset class wins every year. That's not a flaw, it's the entire point of building a diversified investment portfolio.
A Sample Diversified Portfolio for a First-Time Indian Investor
Say you have ₹50,000 to put to work. Here is one way to split it, purely as an example, not a recommendation: ₹25,000 (50%) into equity mutual funds through a monthly SIP, ₹12,500 (25%) into debt mutual funds, ₹7,500 (15%) into a gold ETF or sovereign gold bond, and ₹5,000 (10%) kept liquid for emergencies.
If you're 25 with decades ahead of you, you might tilt this further toward equity. Closer to retirement, you'd probably flip it toward debt instead. Your age, your goals and how much market movement you can stomach at night should decide the mix, not a formula copied off the internet.
Common Mistakes Beginners Make
- Going all-in on one stock or sector because a tip sounded convincing at the time
- Chasing whatever's trending on social media instead of sticking to a plan you set for yourself
- Skipping debt entirely because it "grows too slowly," right up until equity has a rough year and debt turns out to be the only thing that held
- Treating a demat account like a trading toy, buying and selling on impulse, when the whole idea was to invest with a horizon
How Often to Review and Rebalance Your Portfolio
Check your portfolio every six to twelve months. Not every day, that's a habit that does more harm than good.
Rebalance once an asset class drifts more than 5 to 10 percentage points from where you started. If equity has grown from 50% to 65% of your portfolio, sell a slice and move it back into debt or gold to restore your original split.
Your demat and trading account statements already show you exactly how your holdings have shifted, so this review takes minutes, not hours.
A balanced XI beats a team of stars who all play the same position, every time. Get your demat account opening sorted, then build a portfolio that can absorb a bad over without losing the match.
Investments in securities are subject to market risks. This article is for educational purposes only and is not investment advice.




















Sign in to leave a comment.