

For many UK homeowners, remortgaging is less about switching lenders and more about protecting their finances from rising costs. When a current deal is coming to an end, finding the best remortgage rates UK lenders are offering can make a genuine difference to monthly outgoings. But rates alone rarely tell the full story. Understanding how lenders price their deals, what affects eligibility, and which costs sit alongside the headline figure all shape whether a remortgage is actually the right move. This article explains what homeowners should look at before comparing deals, so the decision is based on the full picture rather than a single number.
Understanding Remortgaging
Remortgaging means replacing an existing mortgage with a new one, either with the same lender or a different one. Homeowners typically remortgage for one of a few reasons: their current deal is ending, they want to release some of the equity in their home, or they simply want better terms than their existing arrangement offers.
The process involves an application, an assessment of affordability, and usually a property valuation. Unlike a first-time mortgage, the borrower already has an established property and, in most cases, a repayment history that lenders will assess. This can work in the homeowner's favour, but it doesn't guarantee approval or a particular interest rate.
Why Remortgaging Matters to Homeowners
Many homeowners assume their mortgage payments will stay broadly similar once their initial deal ends. In reality, moving from a fixed rate onto a lender's standard variable rate can increase monthly payments considerably, sometimes by a noticeable margin. This is one of the main reasons homeowners look into the best remortgage rates UK lenders currently offer before their existing deal expires.
Reviewing options in advance also gives homeowners more room to plan. Rather than reacting to a sudden increase in payments, they can compare products, understand their borrowing position, and make a considered decision rather than a rushed one.
Key Factors to Consider
Several elements influence which remortgage deals are realistically available to a homeowner, and what they will cost overall:
- The interest rate itself, and whether it is fixed or variable
- Loan-to-value, based on the current property value and outstanding balance
- The remaining mortgage term
- Product fees and any arrangement charges
- Early repayment charges on the existing deal
- Affordability, based on income and existing financial commitments
- Credit profile and repayment history
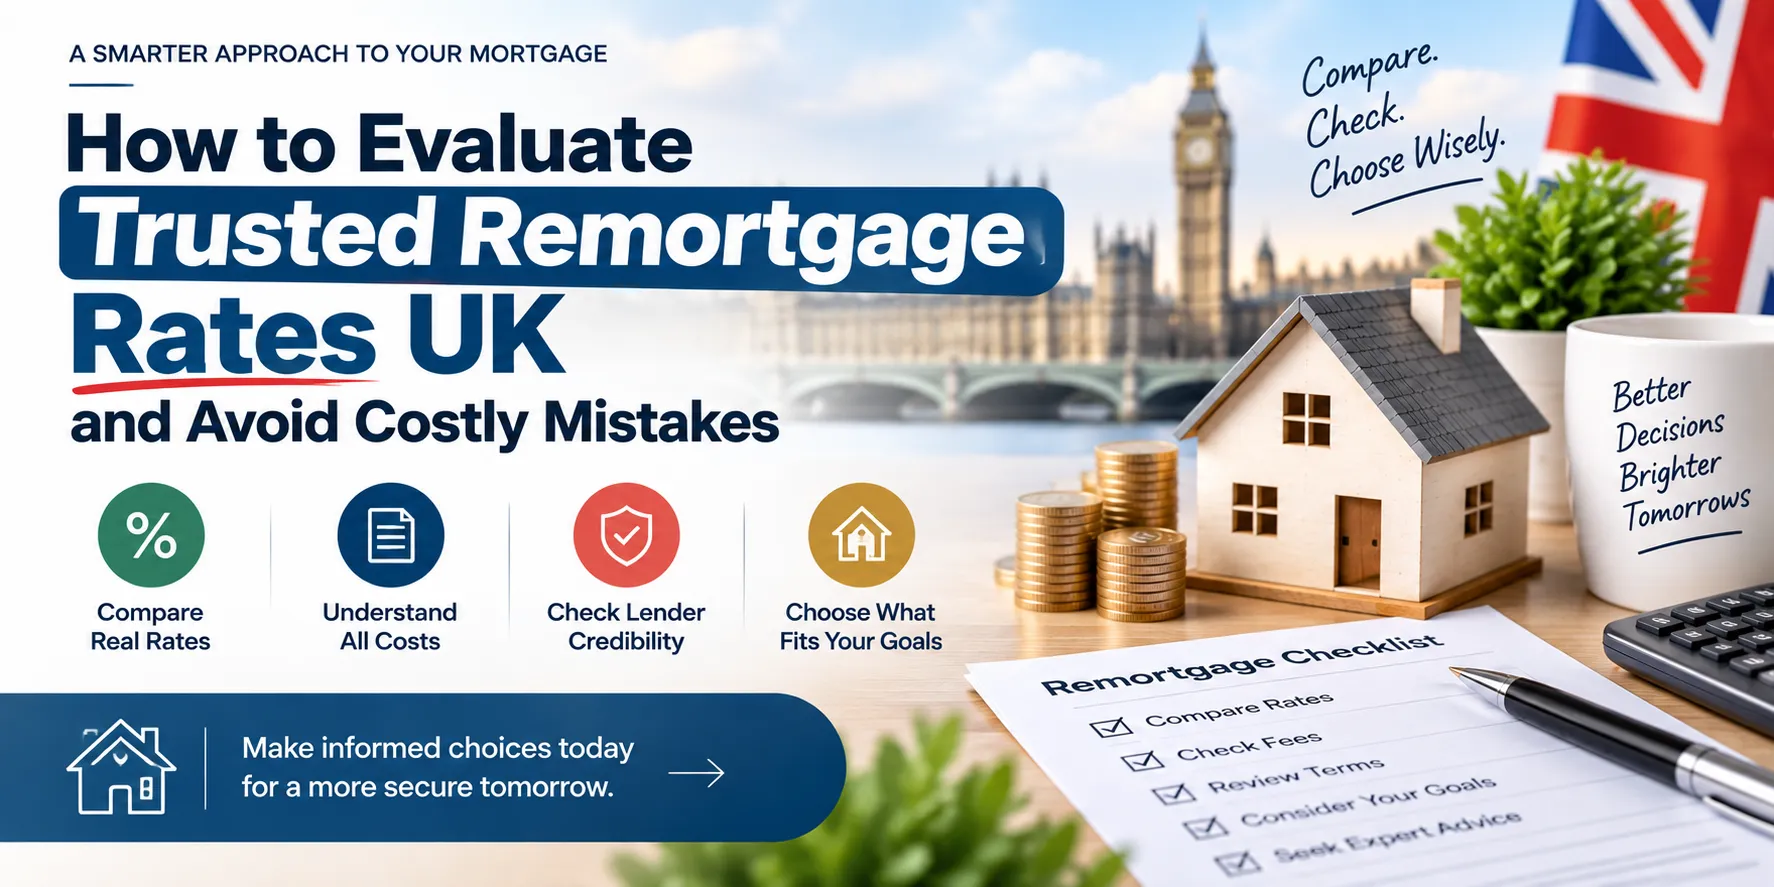
A lower rate attached to a high fee is not automatically cheaper than a slightly higher rate with no fee. This is why comparing the overall cost of a deal, rather than the rate in isolation, matters more than it might first appear.
Understanding Remortgage Deals in the UK
When comparing remortgage deals UK lenders present, it helps to look beyond the interest rate shown at the top of a comparison table. Two deals with similar rates can carry very different total costs once fees, incentives, and conditions are factored in.
Some deals include free valuations or contributions towards legal fees, which can offset a slightly higher rate. Others carry higher arrangement fees that only make sense for larger mortgage balances, where the fee is spread across a bigger loan. Homeowners with smaller outstanding balances may find that a fee-free deal, even at a marginally higher rate, works out cheaper overall.
It's also worth checking whether a deal is portable, in case a home move is likely during the mortgage term, and what happens once the initial period ends, since most deals revert to a lender's standard variable rate afterwards.
Remortgaging to Release Equity
Some homeowners choose to remortgage to release equity, using the difference between their home's current value and their outstanding mortgage balance to access additional funds. This might be used for home improvements, consolidating other borrowing, or supporting a family member, among other reasons.
Releasing equity increases the overall mortgage balance, which usually means higher monthly repayments or a longer repayment term, or both. It can also affect the loan-to-value ratio, which in turn can influence which rates a lender is willing to offer. Equity release through remortgaging isn't inherently good or bad; it depends on the homeowner's wider financial position, what the funds are needed for, and whether the additional borrowing is manageable over the mortgage term. It's a decision worth thinking through carefully rather than treating as a straightforward way to access cash.
What Happens After a Fixed Mortgage Term?
Once a fixed-rate period ends, most mortgages move onto the lender's standard variable rate unless the homeowner arranges a new deal beforehand. Standard variable rates are typically higher than fixed-rate products, which is why many homeowners choose to remortgage after fixed term rather than let their mortgage roll onto this default rate.
Lenders usually allow homeowners to secure a new deal a few months before their current one ends, often without immediate financial commitment until the new rate takes effect. This window gives borrowers time to compare options and avoid an unplanned jump in payments. Missing this period doesn't mean losing the ability to remortgage, but it can mean a period of higher payments before a new deal is arranged.
Choosing Professional Remortgage Guidance
Comparing mortgage products independently is possible, but the range of deals, fees, and lender criteria can make it difficult to judge which option genuinely suits a particular set of circumstances. This is where a mortgage adviser can help, by reviewing a homeowner's full financial picture and identifying options that might not be immediately obvious from a comparison website.
Winstanley Mortgage Services works with homeowners across the UK to help them understand their remortgage options in plain terms, without assuming that the lowest advertised rate is always the right fit. For homeowners weighing up their choices, finding the best remortgage rates UK lenders offer often comes down to comparing fees and loan-to-value alongside the rate itself, not just the headline figure.
Common Remortgaging Mistakes to Avoid
A number of avoidable mistakes can end up costing homeowners more than necessary:
- Waiting until the existing deal has already ended before looking at options
- Focusing only on the headline interest rate
- Overlooking arrangement fees, valuation fees, or legal costs
- Ignoring early repayment charges on the current mortgage
- Assuming the lowest rate is always the cheapest overall deal
- Not checking affordability against current income and outgoings
- Failing to compare the total cost of a deal across its full term
- Making decisions based on assumptions rather than checking current mortgage terms directly
Avoiding these mistakes usually comes down to starting the process early and comparing deals properly, rather than reacting under time pressure.
Final Considerations
Finding suitable remortgage rates involves weighing up more than the number advertised by a lender. Fees, loan-to-value, the remaining mortgage term, and personal financial circumstances all play a part in whether a deal genuinely represents good value. Homeowners considering equity release, or facing the end of a fixed term, benefit from reviewing their options with enough time to compare properly rather than under pressure.
Working out the best remortgage rates UK homeowners can access isn't only about finding the lowest number on a comparison site. It means understanding the full cost of a deal, including fees and terms, and how that fits an individual's circumstances. Starting the process early, and speaking with an adviser where needed, gives homeowners a clearer basis for their decision. Winstanley Mortgage Services provides remortgage guidance for homeowners looking to understand their options before committing to a new deal.





















Sign in to leave a comment.