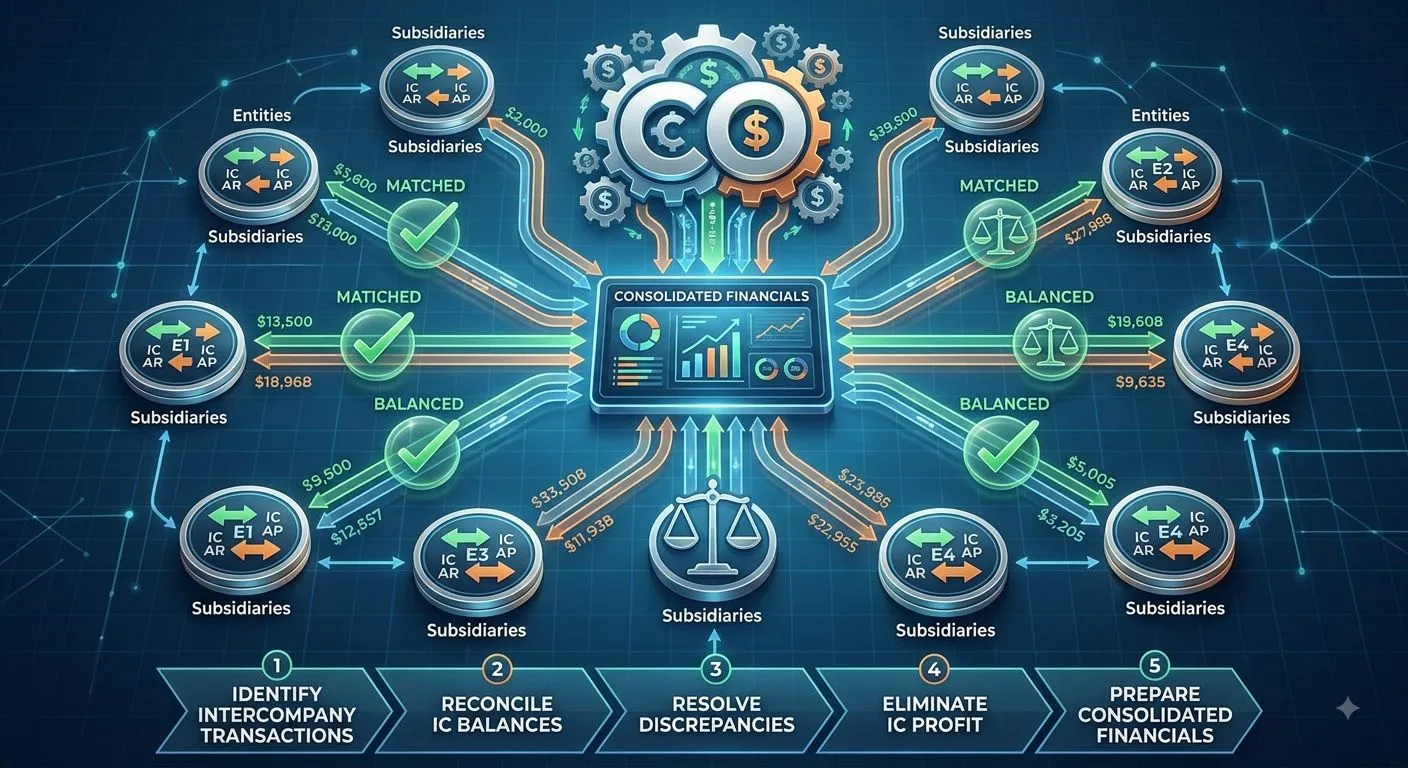
Intercompany balances can appear accurate within individual entities and still create significant problems during group consolidation. A receivable recorded by one subsidiary may not match the corresponding payable in another because of timing, currency conversion, missing invoices, incorrect counterparty codes, or inconsistent account classification. If these differences remain unresolved, finance teams may face residual elimination balances, late adjustments, and delays during group close. Intercompany reconciliation addresses these issues before consolidation by comparing reciprocal transactions, tracing mismatches to source records, and correcting accounting differences. This article explains which balances require reconciliation, why mismatches occur, how to reconcile them systematically, and how finance teams can prepare intercompany accounts for elimination and consolidated reporting.
Why Intercompany Balances Must Be Reconciled Before Consolidation
Intercompany reconciliation confirms that transactions recorded between entities agree before those balances are eliminated from consolidated financial statements. Differences should be identified at the entity level rather than discovered after consolidation begins.
How unmatched intercompany balances affect consolidated financial statements
Unmatched balances can leave residual receivables, payables, revenue, expenses, loans, or other intragroup amounts after elimination. These residuals may distort consolidated assets, liabilities, income, expenses, and group profitability.
Why reconciliation should occur before elimination entries are posted
Elimination assumes reciprocal transactions have already been validated. Reconciliation first establishes whether both entities recorded the same economic event consistently. Elimination can then remove the confirmed intragroup effect rather than masking an unresolved accounting difference.
How unresolved differences can delay the group close
Unresolved differences require finance teams to return to entity records, contact counterparties, retrieve evidence, determine the correct accounting treatment, and post corrections. If this work begins during consolidation, it competes directly with close deadlines.
Why entity-level accuracy does not guarantee consolidated accuracy
Each entity can have internally balanced books while its reciprocal transactions disagree with another entity. A subsidiary may correctly record a $100,000 receivable based on its records while the counterparty records only $95,000 as a payable. Consolidation exposes the $5,000 difference.
What Is Intercompany Balance Reconciliation?
Intercompany balance reconciliation is the process of comparing reciprocal transactions and balances recorded by entities within the same group to confirm that corresponding records agree before consolidation.
Definition of intercompany balance reconciliation
The process compares amounts recorded between related entities and investigates differences in value, timing, currency, classification, counterparty, or accounting period.
Purpose of comparing balances between related entities
The purpose is to confirm that both sides of an intragroup transaction are complete, correctly classified, supported, and recorded in the appropriate period before group reporting.
How reciprocal intercompany balances should correspond
An intercompany receivable recorded by Entity A should correspond with an intercompany payable recorded by Entity B. Similarly, revenue recorded by one entity should correspond with the related expense or asset treatment recorded by the counterparty, subject to the underlying transaction.
Difference between intercompany reconciliation and intercompany elimination
Reconciliation identifies and resolves inconsistencies between entities. Elimination removes confirmed intragroup balances and transactions from consolidated financial statements. Reconciliation therefore precedes elimination.
This distinction also connects intercompany activity with broader general ledger reconciliation, where GL balances are checked against supporting records and transaction activity.
Which Intercompany Balances Need to Be Reconciled Before Consolidation?
Finance teams should identify every material reciprocal balance and transaction that could affect consolidation or elimination. The scope extends beyond intercompany receivables and payables.
Intercompany receivables and payables
Amounts due from one group entity should correspond with amounts due to that entity in the counterparty's books. Differences may arise from invoices, payments, credit notes, or cut-off timing.
Intercompany revenue and expenses
Service charges, royalties, commissions, rent, and other intragroup transactions should be compared so related income and expense treatments can be identified before elimination.
Intercompany loans and interest
Principal balances, accrued interest, repayments, and interest income or expense should agree with loan agreements and counterparty records.
Management fees and shared service charges
Corporate services, IT expenses, administrative costs, and centralized functions allocated between entities require consistent amounts, periods, and allocation treatment.
Intercompany inventory transactions
Inventory transferred or sold between entities requires reconciliation of the underlying sale, purchase, settlement, and any related unrealized profit requiring consolidation treatment.
Fixed asset transfers between entities
Asset transfers can affect asset cost, accumulated depreciation, disposal entries, depreciation expense, and intercompany gains or losses.
Dividends and other intragroup transactions
Dividends, capital movements, reimbursements, and other intragroup activity should also be identified and validated before consolidation.
Why Do Intercompany Balances Fail to Match?
Intercompany differences often arise because separate entities process the same economic event independently. Different systems, calendars, currencies, account structures, and posting procedures create several opportunities for mismatches.
One entity records a transaction that the counterparty has not recorded
Entity A may issue and record an invoice before Entity B receives or processes it. This creates a recorded receivable without the corresponding payable.
Transactions are posted in different accounting periods
A transaction dated August 31 by one entity may be posted on September 1 by the counterparty. The transaction is valid, but the reporting-period difference creates a reconciliation break.
Entities use different foreign exchange rates
Entities operating with different functional currencies may translate the same transaction using different rates or dates, producing differences even when the original transaction amount agrees.
Amounts or account classifications differ between entities
One entity may record a service charge as management fee revenue while the counterparty classifies it under another expense account. Incorrect amounts, taxes, or allocations can create further differences.
Intercompany invoices and credits are recorded differently
Credit notes, reversals, disputed invoices, partial settlements, and adjustments may be processed by one entity before the corresponding entry reaches the other.
Entity and counterparty identifiers are incorrect
Incorrect entity codes can prevent reciprocal transactions from being paired. The amount may be correct while the counterparty attribution is wrong.
Transactions are posted after reconciliation cut-off
Late postings can alter balances after an entity has completed its initial reconciliation, creating differences between previously confirmed balances and final consolidation data.
ERP and data transfer issues create incomplete records
Failed interfaces, mapping errors, incomplete uploads, or inconsistent reference structures can cause transactions to appear in one financial system but not another.
What Records Are Needed to Reconcile Intercompany Balances?
Reliable reconciliation requires evidence that explains both sides of each intercompany relationship. The outline identifies ledger records, schedules, transaction documents, currency information, and counterparty confirmations as the primary sources.
Entity trial balances and general ledger activity
Trial balances establish reported balances, while detailed GL activity shows the transactions that created them. Finance teams should compare entity, counterparty, account, currency, period, and transaction-level information.
Intercompany receivable and payable schedules
These schedules provide the open-item detail needed to compare amounts owed between entities and isolate invoices, payments, credits, and adjustments causing differences.
Invoices, credit notes, and supporting documents
Source documents establish transaction purpose, amount, date, counterparty, currency, and contractual basis. They are particularly useful where ledger descriptions alone cannot explain a mismatch.
Loan agreements and interest schedules
For intragroup financing, teams need principal schedules, interest calculations, repayment records, applicable rates, and agreement terms to verify reciprocal accounting.
Intercompany transaction reports
Transaction-level reports allow finance teams to compare activity across entity pairs instead of relying solely on ending balances.
Foreign exchange rates and currency translation records
Currency records help separate genuine accounting mismatches from differences created through transaction conversion or group reporting translation.
Counterparty confirmations and reconciliation schedules
Formal confirmations establish what each entity believes it owes or is owed. Differences can then be isolated and assigned for investigation.
How to Reconcile Intercompany Balances Before Consolidation
A structured reconciliation sequence moves from data collection and counterparty identification to matching, exception investigation, correction, and final confirmation.
Collect intercompany balances from every reporting entity
Start by extracting relevant GL balances, intercompany schedules, subledger records, and transaction details for the reporting period.
Identify each transaction by entity and counterparty
Every transaction should carry reliable originating-entity and counterparty identifiers. Without consistent identifiers, reciprocal matching across a large group becomes difficult.
Group reciprocal balances by transaction type
Separate receivables and payables, revenue and expenses, loans and interest, inventory transfers, fixed asset transactions, and other categories. This makes differences easier to interpret.
Compare receivables with corresponding payables
Compare Entity A's amount due from Entity B with Entity B's amount due to Entity A. Investigate differences at invoice, credit, payment, and adjustment level rather than forcing the ending balances to agree.
Match intercompany revenue with corresponding expenses
Compare intragroup revenue against the accounting treatment recorded by the counterparty and identify missing, differently classified, or period-shifted transactions.
Compare loans, interest, and other financing balances
Confirm principal, repayments, accrued interest, interest income, interest expense, currency treatment, and contractual terms between lender and borrower entities.
Identify unmatched transactions and balance differences
Separate confirmed matches from exceptions. Exceptions should retain transaction references, counterparty details, value, age, supporting evidence, and investigation status.
Investigate the reason behind each material difference
Trace material exceptions to source records and determine whether the cause is timing, missing postings, currency treatment, mapping, classification, or incorrect accounting.
Post approved corrections before consolidation
Once the correct treatment is established, post the required adjustment through the appropriate entity with supporting evidence and approval. Defined account reconciliation controls help maintain independent review, documented adjustments, and consistent treatment.
Confirm reciprocal balances are ready for elimination
After corrections are posted, rerun the comparison. Reciprocal balances should agree or have clearly documented residual differences before they enter the consolidation process.
How to Match Intercompany Transactions Across Entities
Transaction-level matching provides stronger evidence than comparing ending balances alone. The matching process should consider identifiers, references, amounts, currencies, dates, and transaction relationships.
Match transactions using counterparty identifiers
Counterparty IDs establish which entities represent the two sides of a transaction and prevent amounts from being matched against the wrong group company.
Compare invoice and document references
Invoice numbers, credit note references, loan identifiers, payment references, and other document IDs can establish direct relationships between reciprocal entries.
Use transaction amount and currency
Amounts should be compared in the original transaction currency where possible before translation effects are investigated separately.
Compare transaction and posting dates
Different invoice, recognition, settlement, and posting dates can explain apparent mismatches and help isolate genuine cut-off differences.
Account for one-to-many and many-to-one relationships
A single intercompany payment may settle several invoices, while multiple payments may settle one balance. Matching logic should therefore support grouped transaction relationships.
Separate exact matches from transactions requiring investigation
Confirmed reciprocal transactions can be cleared from the active review population. Uncertain or incomplete matches should remain visible until finance teams establish their accounting treatment.
How to Investigate Intercompany Reconciliation Differences
Once matching isolates exceptions, finance teams need to establish which records are correct and what correction is required.
Trace unmatched balances to transaction-level records
Start with the unmatched amount and trace it to invoices, journals, payments, subledger entries, contracts, or other originating records.
Determine which entity recorded the transaction correctly
Compare both accounting entries against the underlying economic event and supporting documentation. Balance agreement should never be created by adjusting the entity that happens to be easier to change.
Check whether the counterparty transaction is missing
Confirm whether the corresponding invoice, payable, receivable, credit, payment, or journal was received and recorded by the other entity.
Review account and entity mappings
Incorrect GL mappings or counterparty codes can make properly recorded transactions appear unmatched or cause incorrect elimination treatment.
Compare posting dates and accounting periods
Check whether both entities recognized the transaction in the same reporting period. A cut-off difference may require an adjustment depending on group accounting policy.
Review supporting evidence from both entities
Evidence should establish transaction purpose, amount, date, currency, counterparty, approval, and accounting treatment.
Assign responsibility for correcting the difference
Every unresolved item should have a responsible entity or finance owner, expected action, and resolution date. This prevents differences from remaining open simply because ownership is unclear.
How to Handle Timing and Cut-Off Differences Between Entities
Timing differences require separate treatment because a legitimate transaction can still produce an intercompany mismatch if counterparties recognize it in different periods.
Identify transactions recorded in different accounting periods
Compare transaction, invoice, receipt, posting, and settlement dates to determine whether the mismatch results from period timing.
Compare entity close calendars and posting cut-offs
Different close schedules can create recurring mismatches. Group finance should establish common cut-off expectations so entities know which transactions belong in the reporting period.
Separate genuine timing differences from missing transactions
A difference should be classified as timing only when evidence shows that the reciprocal transaction exists and is expected to clear. Missing transactions require investigation rather than a timing label.
Document transactions expected to clear in the following period
Valid timing items should include the amount, counterparty, cause, expected clearing date, and supporting record so reviewers can verify subsequent resolution.
Post cut-off adjustments where accounting policy requires them
Where a transaction belongs in the current reporting period, the appropriate entity may need to record an accrual, payable, receivable, or other approved adjustment.
Monitor timing differences that repeatedly cross reporting periods
Repeated timing explanations can indicate late invoicing, inconsistent cut-offs, delayed interfaces, or weak entity coordination. Recurring items should therefore be investigated at their source rather than carried forward indefinitely.
Conclusion: Reconcile Before the Consolidation Clock Starts
Intercompany reconciliation should be completed before consolidation becomes dependent on unresolved entity-level differences. Matching reciprocal balances earlier gives finance teams time to investigate missing transactions, correct account or counterparty mappings, resolve currency and cut-off differences, and document material exceptions before elimination entries are processed.
For organizations managing intercompany activity across multiple entities, currencies, ERPs, and high transaction volumes, automated reconciliation software can support transaction matching, exception identification, unresolved difference tracking, and supporting evidence management. This helps finance teams enter consolidation with clearer intercompany positions and fewer unresolved items competing with group close deadlines.














Sign in to leave a comment.