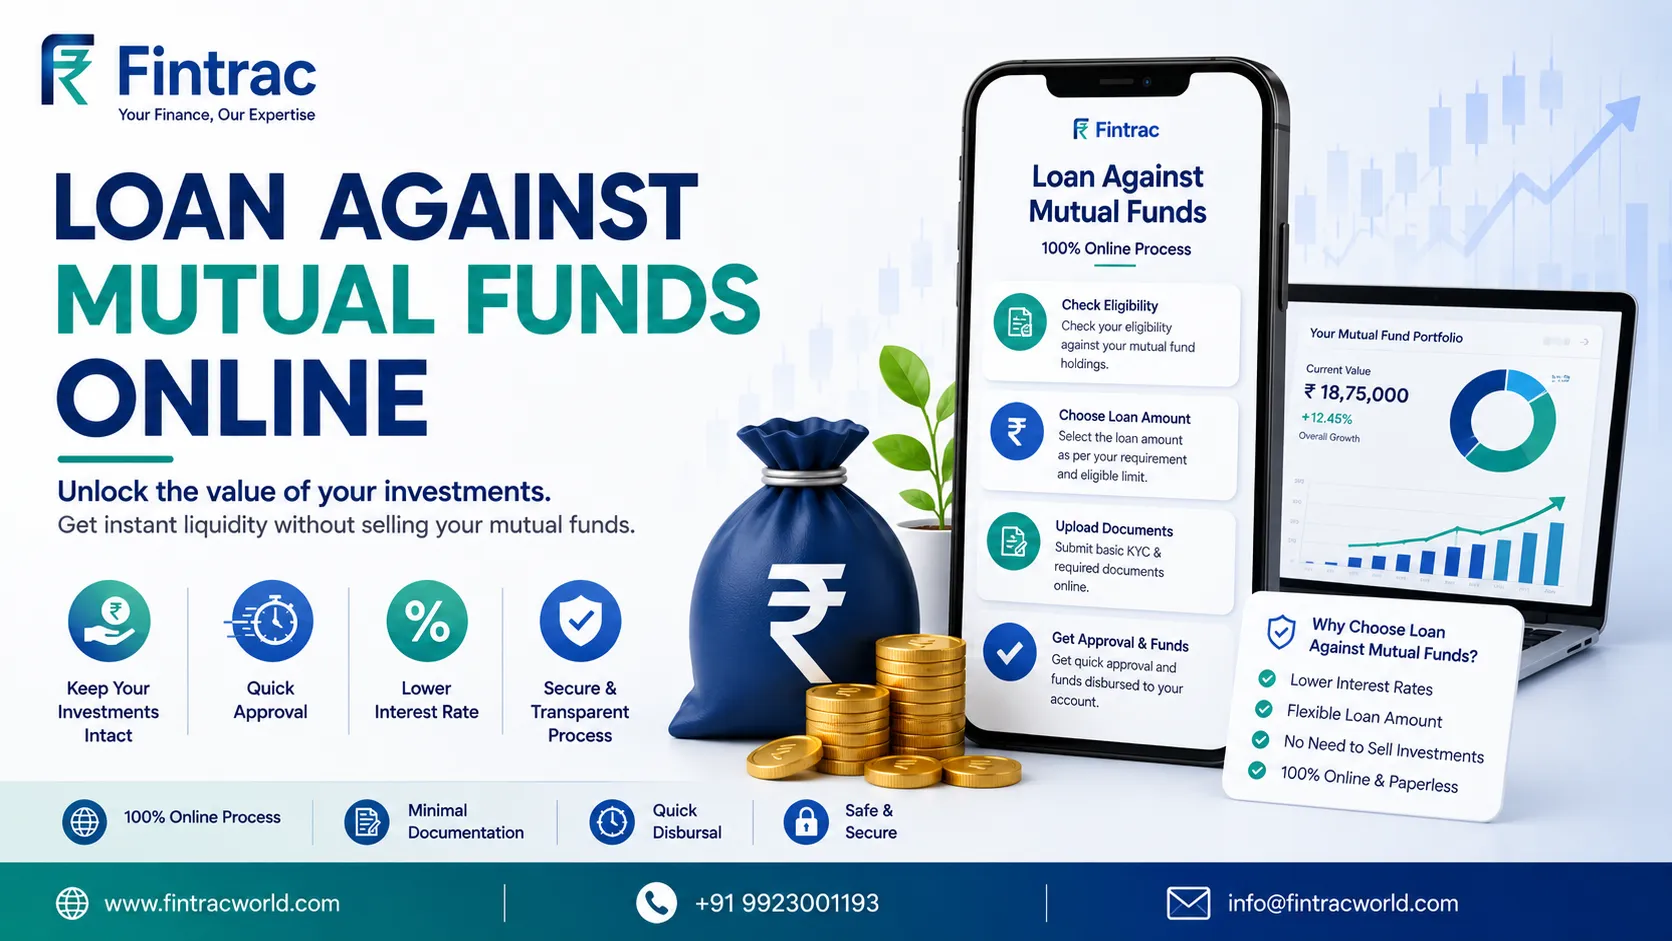

Financial needs can arise unexpectedly, even when your money is invested for long-term goals. If you have investments in mutual funds and need temporary access to funds, selling your units may not always be the first option you want to consider. A loan against mutual funds online can provide an alternative by allowing eligible investors to use their mutual fund holdings as collateral.
With digital lending services, eligible borrowers may be able to complete much of the application process online. Some lenders offer paperless applications and digital pledge or lien-marking facilities. However, eligibility, loan limits, interest rates, processing time and other conditions vary between lenders.
What Is a Loan Against Mutual Funds Online?
A loan against mutual funds is a secured borrowing facility where eligible mutual fund units are pledged to a lender as collateral. The investor does not necessarily need to redeem the units to access funds.
The online version of the facility allows eligible borrowers to complete the application digitally. Depending on the lender, the process may involve online verification, selection of eligible mutual fund units, digital consent, lien marking and loan activation. For example, HDFC Bank currently describes its digital facility as a 100% digital process, while ICICI Bank also provides a digital application route for eligible customers.
How Does an Online Loan Against Mutual Funds Work?
The process is generally completed in a few stages.
1. Check Your Eligibility
First, check whether your mutual fund holdings qualify for the lender's facility. Not every mutual fund scheme may be accepted. Eligibility can depend on the type of fund, ownership, KYC status, account relationship and lender-specific criteria.
2. Select the Mutual Fund Units
After eligibility is confirmed, you may be able to select the mutual fund units that you want to pledge. The lender determines the amount that can be made available based on the value of eligible holdings and the applicable loan-to-value ratio.
3. Complete Online Verification
The lender may ask for identity, bank account and investment-related information. Some digital products can use information already available through the lender's systems or registered transfer agents.
4. Pledge the Investments
The selected units are pledged or lien-marked in favour of the lender. The mutual fund investment remains associated with the investor, but it serves as security for the borrowing.
5. Access the Approved Funds
Once the required digital formalities are completed, the approved credit facility can be activated or the funds can be made available according to the lender's process.
Can You Apply Without Visiting a Branch?
In many cases, yes. Several financial institutions now provide digital application options.
For example, HDFC Bank states that its digital loan against mutual funds can be applied for online and describes the process as paperless. Zerodha Capital also states that its loan-against-securities application process is entirely online. However, an online application does not mean that every applicant will automatically qualify. The lender's eligibility requirements and approved security list still apply.
What Are the Benefits of a Loan Against Mutual Funds Online?
Convenient Application
One of the main advantages is convenience. Digital applications can reduce the need for physical paperwork and branch visits, depending on the lender.
Access Funds Without Immediate Redemption
Instead of selling eligible mutual fund units, investors can potentially use them as collateral to access liquidity.
Flexible Credit Structure
Some lenders offer overdraft-style facilities where interest is charged on the amount actually utilised. ICICI Bank, for example, states that interest is charged on the utilised amount and the period for which it is used.
Faster Processing
Digital verification and online pledge processes can make the overall borrowing journey quicker than traditional paper-based processes. Actual processing time varies by lender and application.
Continue Holding Investments
The borrower can generally continue to hold the pledged investments, subject to the lender's terms. The units remain subject to the pledge or lien until the applicable obligations are cleared.
How Much Can You Borrow?
The available loan amount depends on the value of eligible mutual fund holdings and the lender's applicable loan-to-value ratio. For example, ICICI Bank currently states that eligible borrowers can obtain up to 70% of NAV for equity mutual funds and up to 80% for debt mutual funds under its digital facility, subject to its conditions.
Other lenders may use different LTV limits. Therefore, borrowers should check the current terms applicable to their specific mutual fund holdings rather than assuming that the same percentage applies everywhere.
What About Interest Rates?
The interest rate is an important part of the total borrowing cost. Rates can vary according to the lender, borrower profile, loan amount, type of mutual fund and other applicable factors.
For instance, HDFC Bank currently displays a digital loan-against-mutual-funds rate starting from 10.75%–12.50% per annum, while ICICI Bank currently lists 10.75%–11.75% per annum for its facility. These are lender-specific published rates and can change over time.
Borrowers should compare the complete cost rather than selecting a facility solely because it advertises a particular interest rate.
Documents and Requirements
Requirements differ between lenders. Depending on the facility, an applicant may need:
- PAN and KYC details
- Bank account information
- Mutual fund holding details
- Eligible mutual fund units
- Required digital authorisations
- Other information requested during verification
Some digital facilities may require minimal or no physical paperwork. For example, HDFC Bank states that its digital facility does not require physical documentation, while other lenders may have different requirements.
Important Things to Check Before Applying
Before choosing a loan against mutual funds online, consider the following:
- Whether your mutual fund scheme is eligible
- Maximum loan amount available
- Applicable LTV ratio
- Interest rate
- Processing charges
- Renewal or service charges
- Prepayment conditions
- Repayment structure
- What happens if the mutual fund value falls
- Conditions for releasing the pledge
Mutual fund values can fluctuate with market conditions. Therefore, borrowers should understand how a fall in the collateral value may affect the credit facility.
Financial Information from Fintracworld
Fintracworld provides information on financial topics to help readers understand different borrowing and investment-related concepts. When researching a loan against mutual funds online, users can compare eligibility, interest rates, digital application procedures and repayment conditions before selecting a suitable option.
The latest product details should always be checked with the respective lender because rates, fees, eligibility criteria and digital processes may change.
Online Loan vs Selling Mutual Fund Units
Selling mutual fund units and borrowing against them are two different approaches.
When units are redeemed, the investment is reduced or exited to generate cash. With a loan against mutual funds, eligible units are instead used as collateral while the investor may continue holding them.
Neither option is automatically better for every situation. The right choice depends on the amount required, repayment capacity, investment objectives, borrowing cost and the terms available.
Choosing the Right Digital Lending Option
When comparing online facilities, look beyond speed and convenience. A suitable option should have terms that you understand and can comfortably manage.
Compare:
- Interest rate
- Loan-to-value ratio
- Processing fees
- Minimum and maximum loan amount
- Repayment flexibility
- Eligible mutual fund schemes
- Collateral-related conditions
- Prepayment and closure terms
Taking a few minutes to compare these factors can help avoid unexpected costs later.
Conclusion
A loan against mutual funds online can offer a convenient way for eligible investors to access liquidity without immediately redeeming their mutual fund investments. Digital application processes can make borrowing more convenient by reducing paperwork and allowing several formalities to be completed online.
Borrowers should compare interest rates, fees, LTV limits, repayment terms and collateral requirements before proceeding. Since mutual fund values can fluctuate, it is equally important to understand the lender's conditions if the value of pledged units changes. For readers looking for clear financial information, Fintracworld can help explain important concepts and factors to consider when evaluating different borrowing options.
Frequently Asked Questions
1. Can I apply for a loan against mutual funds online?
Yes, some lenders provide completely or largely digital application processes. The exact procedure depends on the lender and the eligibility of your mutual fund holdings.
2. Do I need to sell my mutual funds to get the loan?
Generally, the purpose of this facility is to use eligible mutual fund units as collateral rather than immediately redeeming them.
3. How much loan can I get against my mutual funds?
The loan amount depends on the value and type of eligible mutual fund holdings and the lender's applicable LTV ratio.
4. Is an online mutual fund loan available for every mutual fund?
No. Lenders typically maintain eligibility criteria and approved lists of mutual fund schemes or categories.
5. What should I check before taking an online loan?
Review the interest rate, processing charges, LTV ratio, repayment terms, eligible securities, collateral conditions and any applicable prepayment or renewal charges.






Sign in to leave a comment.