
The insurance industry has always adapted to new forms of fraud, but generative artificial intelligence is changing the game faster than many traditional controls can keep up. For U.S. property and casualty insurers, the growing availability of synthetic images, altered videos, cloned voices, and AI-generated documents is creating a new challenge: determining whether digital evidence can still be trusted.
This emerging threat, often described as P&C deepfakes, goes beyond manipulated photographs. Fraudsters can potentially create or modify evidence used in auto, homeowners, commercial property, and liability claims, making digital verification an increasingly important part of the claims process.
Why P&C Deepfakes Are Different
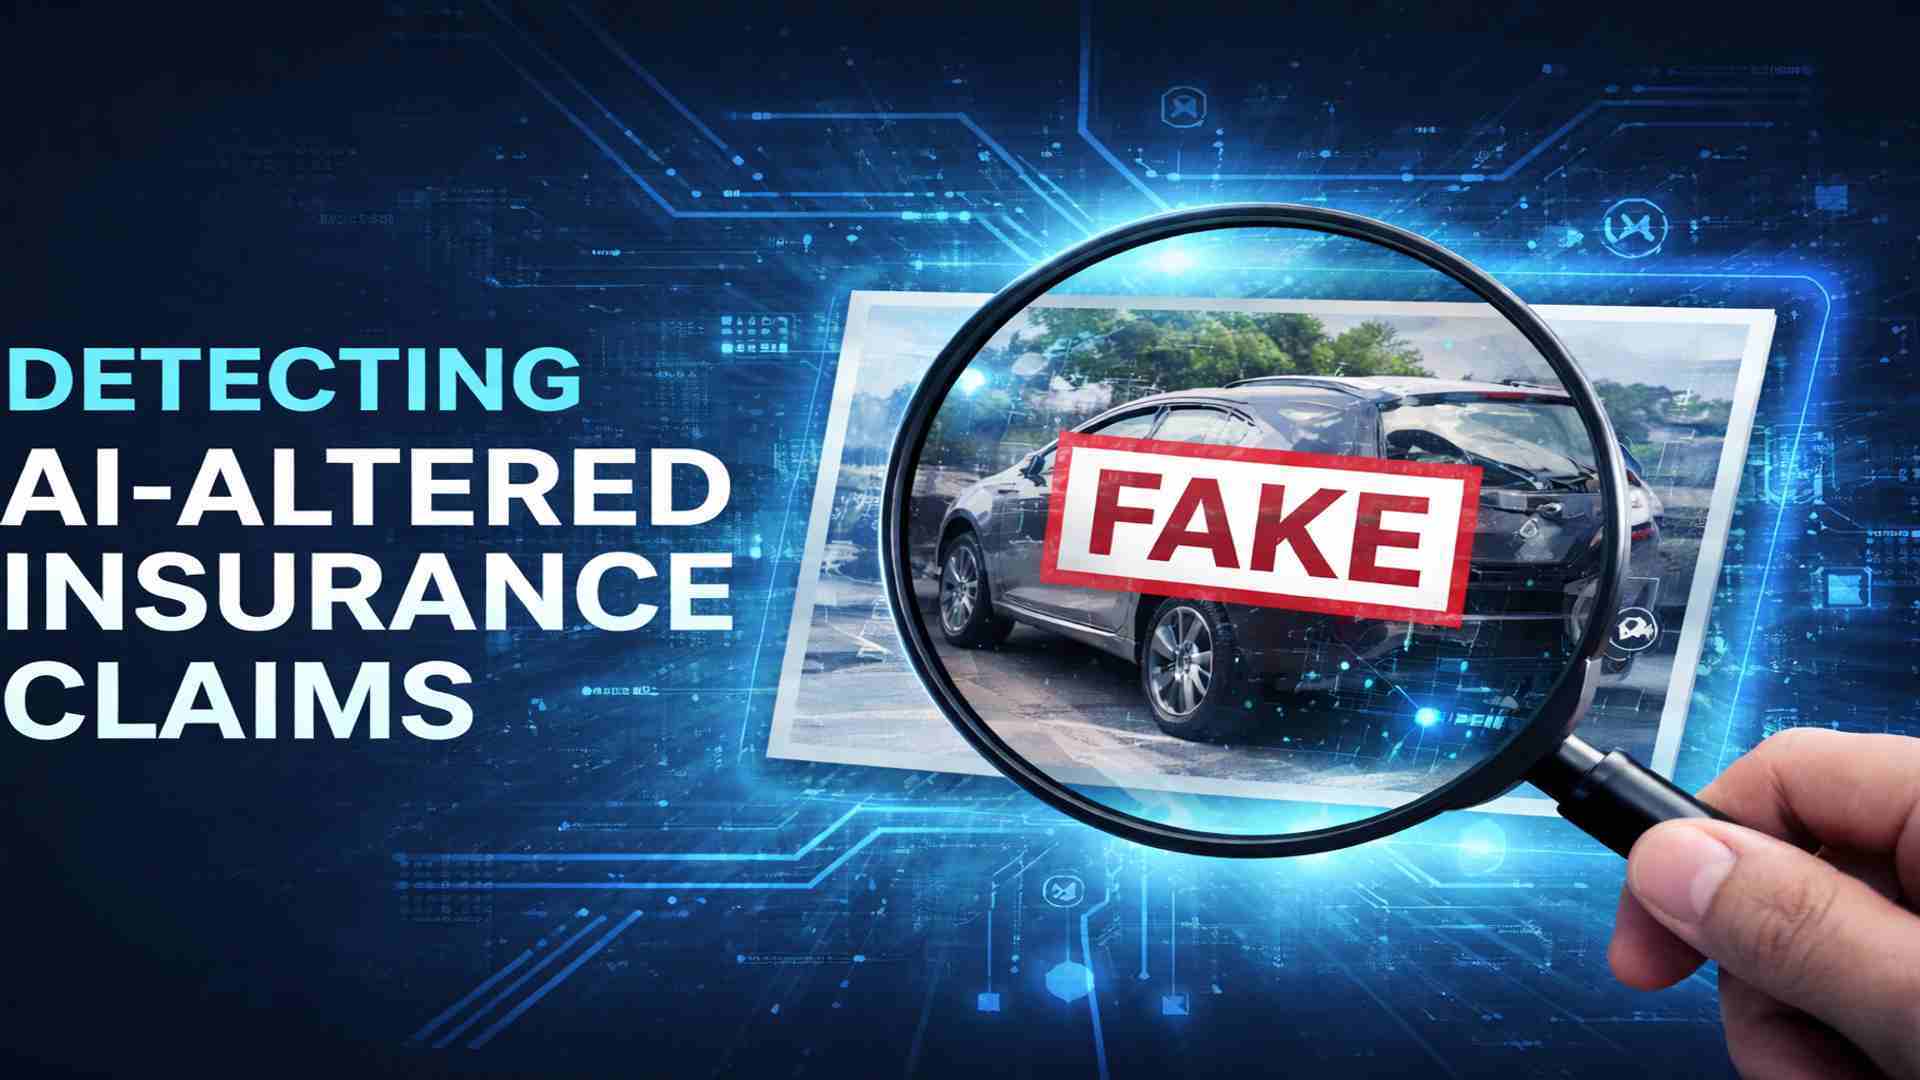
Traditional claims fraud often involved exaggerating legitimate damage, staging accidents, submitting duplicate claims, or falsifying documents. Generative AI adds another layer because it can make fabricated evidence look convincing without requiring advanced technical skills.
For example, a fraudulent claimant could submit an altered vehicle image showing damage that did not occur, modify a property photograph to make storm damage appear more severe, or create a synthetic document that resembles a legitimate contractor estimate.
Voice cloning creates another concern. A criminal may attempt to imitate a policyholder, employee, witness, or vendor during a phone interaction. Deepfake identity fraud is already recognized as a growing AI-enabled risk, while insurers are increasingly using AI themselves for claims handling and fraud detection.
The Bigger Problem Is Not Just Fake Images
One of the most important new insights for claims teams is that P&C deepfakes should not be treated as an image-only problem.
A suspicious claim may contain several individually believable pieces of evidence. The photograph may look legitimate. The invoice may appear professionally prepared. The claimant's explanation may sound reasonable. But when these elements are analyzed together, inconsistencies can emerge.
This makes cross-validation increasingly valuable.
Claims systems can compare submitted media with metadata, previous claims, policy information, repair estimates, location data, and historical patterns. Image similarity technology can also help identify photographs that have appeared in previous submissions, even when they have been resized or slightly modified.
The goal is not simply to ask, “Is this image fake?” Instead, insurers can ask, “Does all available evidence tell the same story?”
Moving Fraud Detection Closer to FNOL
For U.S. insurers, the first notice of loss (FNOL) is becoming a critical opportunity to identify suspicious digital evidence.
AI-powered systems can analyze uploaded photographs, documents, and other files when they enter the claims workflow. Signals such as unusual metadata, image inconsistencies, duplicate media, document anomalies, or mismatches between the claimant's narrative and submitted evidence can contribute to an overall risk assessment.
The Insurance Information Institute notes that AI and machine learning are increasingly being used to identify suspicious claims and risk indicators earlier in the claims lifecycle.
This approach can help SIU teams prioritize investigations rather than manually reviewing every claim with the same level of scrutiny.
AI Needs Governance Alongside Detection
There is another side to the story. Insurers are not only defending against AI-generated fraud; they are also adopting AI for underwriting, pricing, claims, and fraud detection.
That creates a need for responsible AI governance. The National Association of Insurance Commissioners has emphasized that existing insurance laws and regulatory obligations still apply when insurers use AI or third-party models. In 2026, the NAIC also introduced an AI Systems Evaluation Tool as part of its evolving oversight framework.
For insurers, effective fraud technology therefore needs more than detection accuracy. Auditability, human oversight, explain ability, data quality, and appropriate escalation processes are becoming equally important.
The Future of P&C Claims Is Evidence Intelligence
P&C deepfakes are likely to become more sophisticated as generative AI improves. But insurers have an opportunity to respond by combining media forensics, behavioral analytics, document intelligence, network analysis, and human investigation.
For SimpleSolve Inc, the broader opportunity is clear: modern claims technology should help insurers evaluate evidence faster while supporting smarter fraud detection and better decision-making.
The future is not about trusting every digital file—or automatically rejecting anything unusual. It is about building claims workflows capable of connecting multiple signals, identifying inconsistencies early, and giving adjusters and SIU professionals the intelligence they need to investigate with confidence.





















Sign in to leave a comment.