
The fastest way to misunderstand plant-based protein in 2026 is to treat it as a single category. It is not. Pea isolate in a ready-to-drink shake, tofu in a weeknight stir-fry, mycoprotein in a frozen entrée, soy concentrate in a burger, and a lentil-pumpkin seed blend in a pasta sauce all solve different problems. That distinction matters now because the hype cycle has broken. Sales momentum has cooled in some headline-grabbing meat analogues, ingredient companies have shifted toward functionality and cost control, and shoppers have become less forgiving about texture, sodium, ingredient lists, and price. According to The Guardian’s March 2026 reporting on dairy milk’s comeback amid the protein boom, some consumers have moved back toward dairy-based protein products, especially where value and familiarity win.
That does not mean plant-based protein has failed. It means the category is maturing, and mature categories reward products that do one job well. If your goal is muscle support, the answer may be soy or a blended powder with a credible amino acid profile. If your goal is replacing ground meat in chili, textured pea or soy may outperform premium burgers on both cost and cooking flexibility. If your goal is family cooking, beans, tofu, tempeh, edamame, and fortified soy yogurt often beat ultra-processed replicas on nutrition per dollar. Readers who want a parallel consumer view can compare this analysis with Plant-Based Protein Alternatives Review That Actually Holds Up and Plant-Based Protein Alternatives Review: What Truly Delivers.
The category is no longer being judged on novelty. It is being judged on repeat purchase, protein quality, price, and whether people actually want to cook with it twice a week.
My thesis is straightforward: the best plant-based protein alternatives in 2026 are not necessarily the most engineered or the most marketed. They are the ones that balance protein density, digestibility, taste, culinary usefulness, and cost. That narrows the field considerably.
How the category moved from disruption story to performance test
A few years ago, plant-based protein alternatives were sold as a broad cultural correction: better for the planet, better for animals, and increasingly good enough to displace meat and dairy at scale. That promise was partly real and partly overextended. The early commercial wins came from products that delivered an immediate behavioral shortcut. Burgers looked like burgers. Oat milk foamed. Vegan nuggets fit the freezer routine. But scale exposed the harder truth: consumers do not buy categories; they buy meals, habits, and macros.
Research on acceptance patterns helps explain the reset. Nature’s overview of consumer acceptance of plant-based meat alternatives points to familiar barriers: taste, texture, price, cultural habits, and skepticism about processing. Those frictions were always present. They were merely masked for a while by novelty and heavy retail placement. Once inflation, higher interest rates, and pantry fatigue entered the picture, shoppers became more selective. A product had to justify itself against chicken thighs, Greek yogurt, eggs, canned tuna, or plain old beans.
At the same time, ingredient makers started talking less about replacing whole categories and more about functionality. That shift is visible in FoodNavigator’s 2025 coverage of plant-based protein trends, which noted that while meat alternatives cooled, protein ingredients found growth in bakery, snacks, beverages, and hybrid formulations. That is a more sober commercial logic. Protein is not only a center-of-plate story. It is also an emulsifier, a texture builder, a satiety signal, and a formulation tool.
There is a second change, and it is more practical than ideological. Consumers have become better at reading labels. They compare grams of protein per serving. They notice sodium. They ask whether a 10-ingredient burger that costs significantly more than beef or chicken is really the best answer for Tuesday dinner. This is why foundational foods have regained credibility. Tofu did not need a rebrand. Tempeh did not need a celebrity launch. Lentils have quietly outperformed many venture-backed claims simply by being cheap, versatile, and nutritionally coherent.
The market’s correction has been healthy. It separates products built for headlines from products built for households.
What to judge in a serious plant-based protein alternatives review
Most reviews fail because they compare unlike products as if they were interchangeable. A protein powder should not be judged by the same criteria as a burger patty, and a refrigerated tofu block should not be scored like a shelf-stable snack bar. A useful review framework starts with use case, then moves to nutrition, then to sensory performance, then to cost.
The first screen is protein quality and quantity. Not every plant protein source offers the same amino acid profile, and not every product uses enough protein to matter. Soy remains one of the strongest all-around options because it is a complete protein and appears in multiple workable forms: tofu, tempeh, edamame, soy milk, soy isolate, and textured soy protein. Pea protein has become the workhorse of modern formulation because it is relatively neutral, scalable, and allergen-friendly compared with soy for some consumers, though manufacturers often blend it with rice or other proteins to improve texture and amino acid balance.
The second screen is culinary fit. A protein can look good on paper and still fail in the pan. Tofu rewards technique: pressing, marinating, starching, roasting, and high-heat searing all change the result. Tempeh brings a firmer bite and a fermented note that some cooks love and others mask with glazes. Seitan offers impressive chew and high protein density, but it is unsuitable for people avoiding gluten. Mycoprotein performs well in certain prepared foods because its fibrous structure approximates meat more naturally than some plant isolates do.
Third comes formulation discipline. Long ingredient lists are not automatically bad; food science exists for a reason. But there is a difference between strategic formulation and compensating for weak fundamentals. If a burger relies on heavy sodium, saturated fat from coconut oil, and aggressive flavor systems to mimic beef, the product may still be useful, but it should not be mistaken for a nutritional upgrade by default.
- Protein density: How many grams of protein does a realistic serving provide?
- Amino acid completeness: Is it complete on its own, or improved through blending?
- Texture performance: Does it hold up in grilling, baking, sautéing, or blending?
- Digestibility: Does the product cause common complaints such as chalkiness or bloating?
- Price per serving: Is it competitive with eggs, dairy, poultry, legumes, or canned fish?
- Ingredient logic: Are additives solving a real technical problem, or merely patching over weaknesses?
For beginners, a practical on-ramp still matters. That is where How to Get Started With Plant-Based Protein Alternatives is useful as a companion read, especially for shoppers moving from curiosity to routine meal planning.
The products that still earn their place in a 2026 kitchen
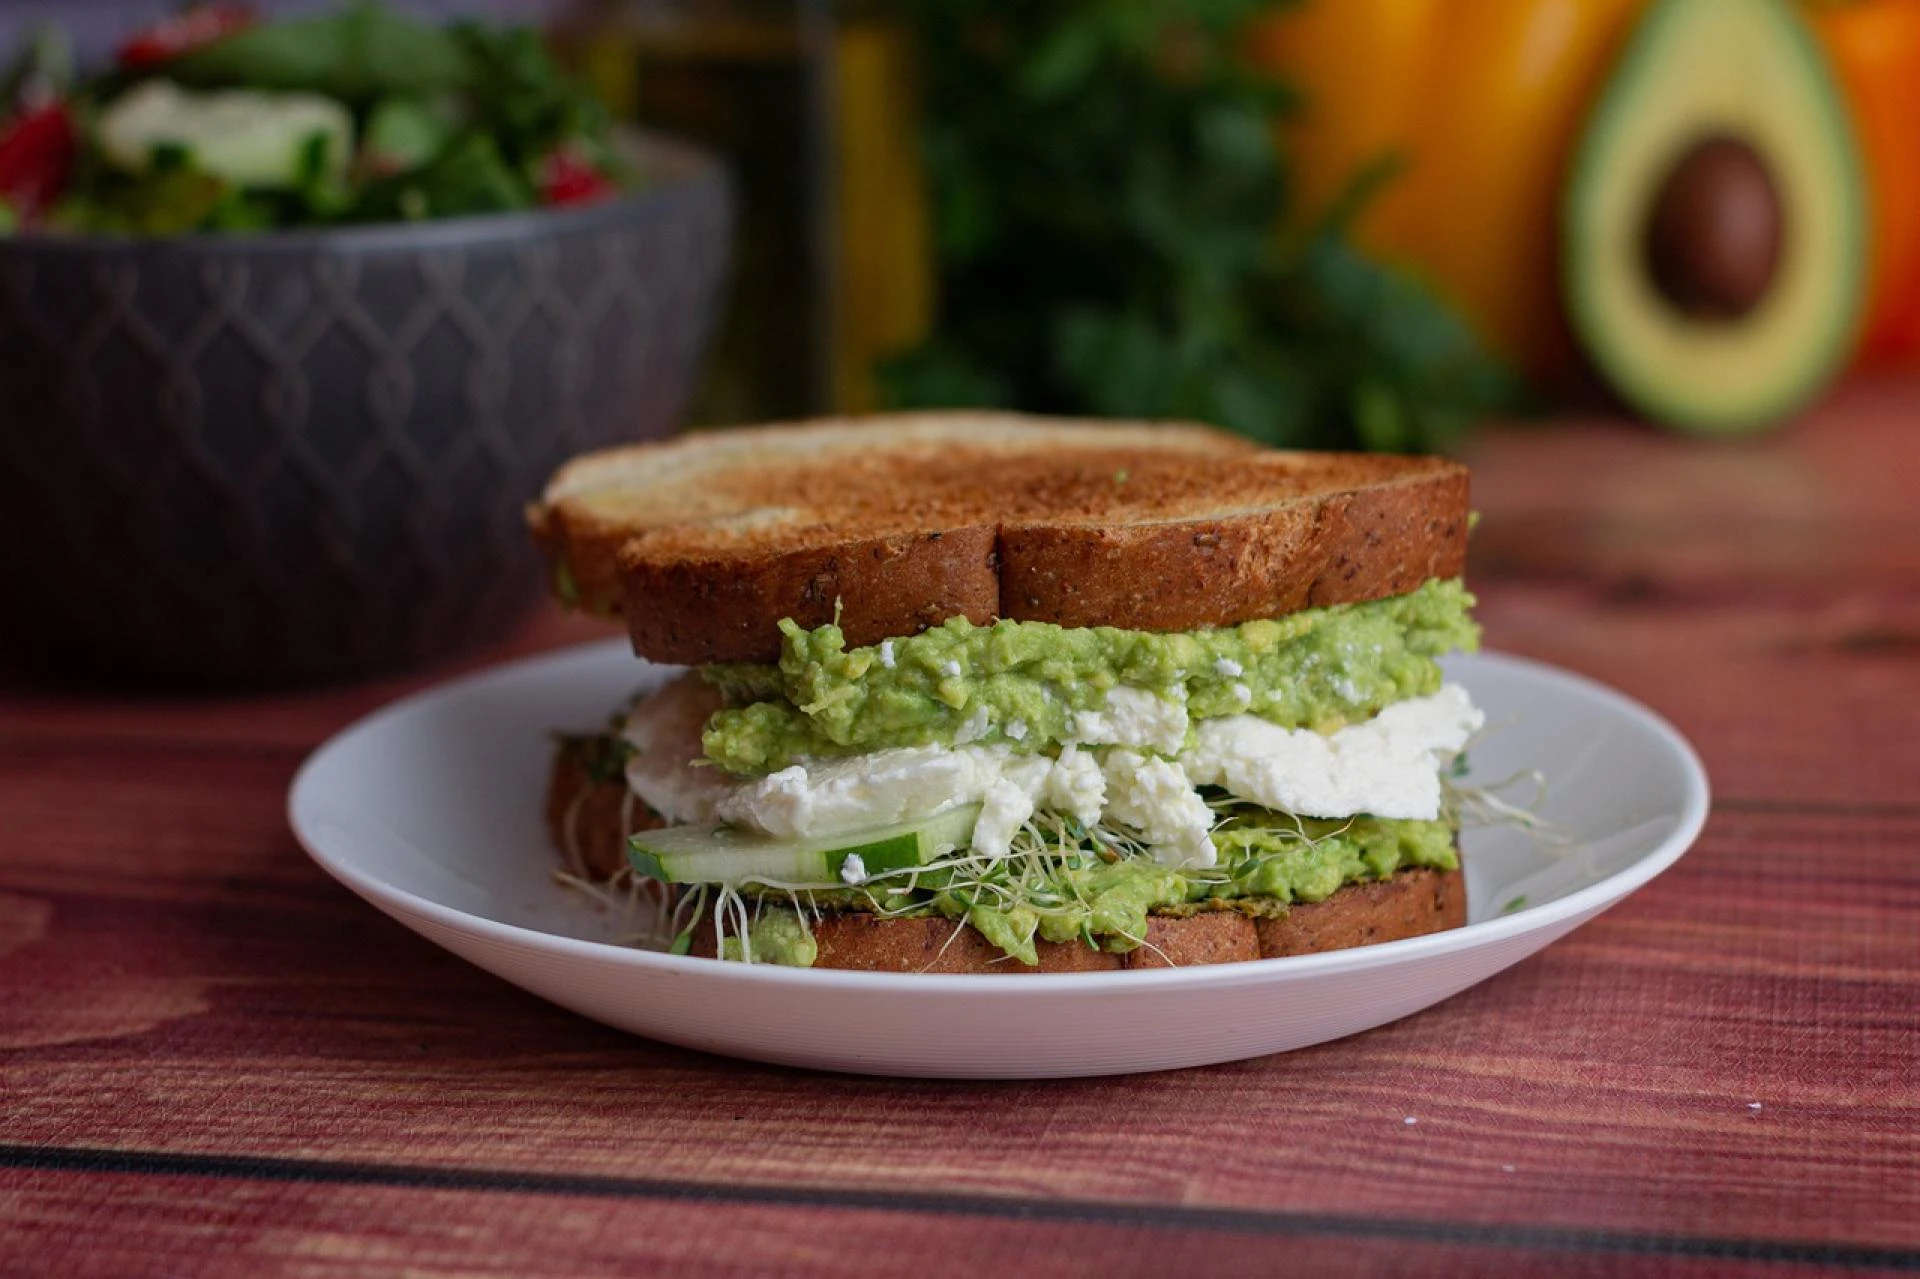
If I were reducing the field to reliable winners, I would start with foods rather than branded simulations. Tofu remains the most underrated protein alternative in Western retail, largely because many people still cook it poorly. Extra-firm tofu can crisp, braise, scramble, grill, and blend into sauces. Silken tofu can thicken dressings, desserts, and creamy soups while adding protein without the sweetness many protein powders bring. Tempeh deserves a close second place because it offers a firmer structure and a savory profile that works especially well in sandwiches, grain bowls, and glazed sheet-pan meals.
Legumes are next. Lentils, chickpeas, black beans, and split peas are not glamorous, but they remain the strongest value proposition in the category. Their protein numbers per serving may be lower than isolates, yet they bring fiber, minerals, and satiety in a way many engineered products do not. For home cooks, they also integrate naturally into cuisines that already understand them: dals, stews, ragùs, patties, salads, curries, and spreads. If your benchmark is “what will I actually eat three times this month,” legumes score higher than many frozen analogues.
Then there are concentrated ingredients. Pea and soy protein powders have a clear role for athletes, busy professionals, older adults trying to maintain muscle mass, and anyone struggling to hit protein targets through meals alone. A practical consumer summary from Wellbeing Magazine on MSN emphasizes convenience and family use, and that framing is sensible. Powders are not a lifestyle identity; they are a tool. The best ones blend cleanly, avoid excessive sweetener aftertaste, and disclose the protein source clearly.
Where I am more cautious is in premium imitation meats that promise a one-to-one beef experience. Some are technically impressive. Fewer are compelling enough on price and nutrition to become staples. They can still be useful as transition products, restaurant menu options, or occasional convenience foods. But their strongest competitors are no longer beef alone. They are seasoned lentils, marinated tofu, and hybrid meals that mix vegetables, mushrooms, grains, and a smaller amount of animal or plant protein for better cost and flavor balance.
- Best all-purpose protein: extra-firm tofu
- Best whole-food value: lentils and chickpeas
- Best high-protein fermented option: tempeh
- Best meat-like texture for cooking: seitan, where gluten is not an issue
- Best convenience tool: pea-soy blended protein powder
- Best for freezer meals: mycoprotein or well-formulated soy-based pieces
That ranking will not satisfy brand loyalists, but it reflects how real kitchens work. Utility beats spectacle.
Where the weak spots remain: taste, sodium, cost, and overprocessing
The category’s critics are not wrong about everything. Taste still breaks many products. Plant proteins can carry grassy, beany, bitter, or dusty notes, especially in powders and bars. Texture can veer from mushy to rubbery. Fat systems used to create juiciness can leave a waxy mouthfeel once the product cools. And because many meat alternatives are trying to replicate a very specific sensory target, they can become overengineered in the process.
Sodium is the most common nutritional compromise. A plant-based sausage or burger may deliver respectable protein, but it can also push sodium levels high enough to matter if the rest of the meal is processed too. Saturated fat is another watchpoint, particularly in products that rely on coconut oil for richness. None of this makes the products unusable. It simply means consumers should stop assuming that “plant-based” automatically means “healthier.” Sometimes it does. Sometimes it plainly does not.
Cost is the bigger structural issue. According to The Guardian’s 2026 reporting, part of dairy’s renewed appeal has been the straightforward protein-value equation. Shoppers compare grams per dollar. When plant-based milk is low in protein and priced above dairy, the proposition weakens unless the buyer prioritizes lactose avoidance, ethics, or taste. The same logic applies to burgers and ready meals. If a product costs more, it needs to outperform on convenience, flavor, or health. Too many do not.
There is also the trust problem. Consumers increasingly ask whether a product is built from ingredients they recognize and whether those ingredients are there for a clear reason. This does not require moral panic about processing. Bread is processed. Yogurt is processed. Tofu is processed. The better question is whether processing improves the food’s function without creating a nutritional tradeoff that undermines the point of buying it.
- Products with 8–15 grams of protein per serving can still underperform if serving sizes are small or price is high.
- Meat analogues often improve texture but may carry higher sodium than whole-food alternatives.
- Plant milks vary sharply; oat milk is often lower in protein than soy milk unless fortified or blended.
- Powders solve convenience but can fail on taste if sweeteners, gums, or flavor masking are poorly handled.
A more durable standard is simple: if the product cannot win on either nutrition, flavor, convenience, or value, it will not survive the next pantry audit.
What changed recently, and why 2026 feels more disciplined
The most important 2026 development is not a single blockbuster launch. It is the industry’s change in tone. Companies that once centered disruption narratives are now talking about margin discipline, formulation improvements, ingredient functionality, and channel strategy. The broad market story also looks more segmented. According to a Yahoo Finance summary of a 2026 protein alternatives market research report, major players including ADM, Kerry, Ingredion, Axiom Foods, Beyond Meat, and Impossible remain part of the competitive map, but the opportunity extends well beyond retail burger shelves into ingredients, foodservice, and specialized nutrition.
That segmentation matters because some of the category’s strongest opportunities are no longer the most visible ones. Bakery enrichment, high-protein snacks, ready-to-mix beverages, school nutrition, and clinical or active-lifestyle products all reward protein systems that behave reliably in manufacturing. FoodNavigator’s reporting on functionality growth captured this pivot well: ingredient suppliers are increasingly focused on solubility, emulsification, water binding, and sensory performance, not just category rhetoric.
Another shift is the rise of blended strategies. Manufacturers are combining plant proteins with fibers, starches, fungi-based inputs, or even smaller amounts of animal protein to improve taste and economics. For consumers, hybrid cooking is becoming normal too. A pot of bolognese made with mushrooms, lentils, and a modest amount of meat can outperform a premium imitation mince on flavor and cost while still reducing animal protein substantially. Purists may object, but households tend to choose what is workable.
Retailers have also become less patient. Shelf space is tighter, and repeat purchase is under closer scrutiny. The result is healthier pressure on product quality. If a plant-based item survives now, it is more likely because it earned its place. Readers interested in the market side should also see Plant-Based Protein Alternatives Review: Trends, Science, and Market Leaders, which complements the consumer lens with a broader category map.
2026 is the year the market stopped asking whether plant protein could be trendy and started asking whether it could be operationally excellent.
A practical buying guide by use case, not ideology
The cleanest way to buy well is to ignore category labels and shop by job-to-be-done. If you need a breakfast protein anchor, soy yogurt, tofu scramble, high-protein soy milk, or a measured scoop of powder in a smoothie will usually deliver more reliably than oat milk and granola alone. If you need lunch portability, roasted edamame, hummus with seeded crackers, tempeh sandwiches, or bean-based salads often travel better than fragile meat analogues. Dinner is where texture matters most, so this is where tofu, tempeh, seitan, and mycoprotein can justify themselves.
For athletes or older adults, the threshold question is whether total daily protein intake is being met. If not, powder is often the least complicated fix. Look for a formula that clearly states protein grams per serving, source material, and sweetener system. Blends can be useful, especially pea and rice, but soy remains a strong benchmark because of its amino acid profile. If digestibility is an issue, trying smaller servings or different formulations is often more useful than abandoning the category entirely.
For families, the answer is usually simpler than marketing suggests. Build around foods that can appear in multiple meals with minimal waste. A block of tofu can become stir-fry, tacos, and a blended pasta sauce. Lentils can become soup, sloppy joes, and salad. Tempeh can move from grain bowls to sandwiches. The more forms a protein can take, the better its household economics.
- Choose soy milk over lower-protein plant milks when protein is the main goal.
- Use tofu or tempeh for weeknight dinners where cooking method can create texture.
- Keep lentils and chickpeas as the low-cost base for batch cooking.
- Reserve premium burgers and sausages for convenience or social occasions, not as nutritional defaults.
- Add protein powder only when meals alone are not meeting practical needs.
This is also where many shoppers benefit from a reality check: the best plant-based protein plan is rarely all one thing. It is a portfolio.
The bottom line: plant-based protein is better when it stops pretending to be magic
After the noise clears, the category looks stronger for being narrower. The winners are easier to identify now. Soy remains foundational. Tofu and tempeh are still among the best protein alternatives available, full stop. Legumes remain unmatched on value and versatility. Seitan is excellent for texture if gluten is not a concern. Powders are useful tools, especially for convenience and targeted intake. Premium imitation meats still have a role, but that role is more limited than early marketing implied.
The key insight from 2026 is that plant-based protein should be reviewed as a set of practical solutions, not a moral referendum and not a tech spectacle. According to Nature’s discussion of consumer acceptance, taste and familiarity still decide adoption. According to FoodNavigator, ingredient functionality is where much of the serious innovation has moved. According to The Guardian, dairy’s protein boom has exposed weak value propositions in some plant-based alternatives. Put together, those signals point to a category that is no longer protected by aspiration alone.
That is good news for informed buyers. It means the best choices are increasingly obvious: buy proteins that fit your cooking style, deliver enough protein to matter, and do not ask you to overlook weak flavor or inflated pricing. If a product helps you cook more often, eat more satisfyingly, and hit your nutrition targets without drama, it belongs in the cart. If not, no amount of branding will rescue it.
Plant-based protein still works. It just works best when judged like any other serious food purchase: by evidence, by usefulness, and by whether it earns a second buy.














Sign in to leave a comment.