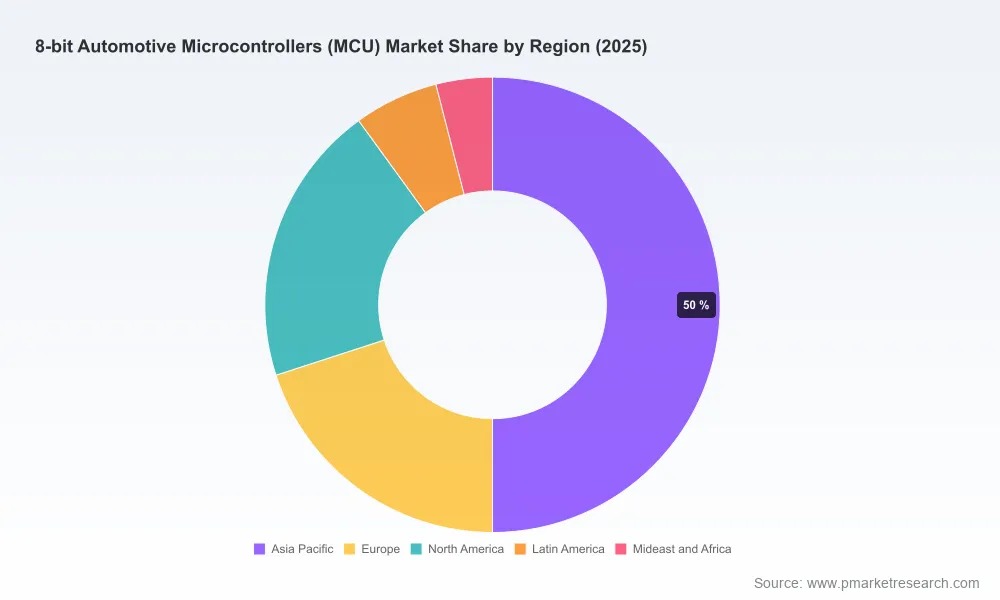

Strategic Intelligence for the 2026 Automotive Supply Chain: Inside the 8-bit MCU Market Research
Why 8-bit Architecture Remains Indispensable in an Era of High-Performance Computing
The automotive electronics landscape is frequently dominated by headlines around domain controllers, centralized compute architectures, and artificial intelligence-enabled processors. Yet beneath these high-profile transformation narratives, the industrial reality of vehicle assembly continues to rely heavily on a mature, cost-effective, and highly resilient layer of embedded control: 8-bit automotive microcontrollers. For strategic planners, procurement leaders, and technology investment committees, dismissing this segment as legacy would be a costly oversight. Our latest market research into the 8-bit Automotive Microcontrollers sector is designed to cut through the hype and deliver a structured, forward-looking intelligence framework tailored precisely for 2026 decision-making.
8-bit Automotive Microcontrollers (MCU) Market
Over the historical observation window spanning 2020 through 2025, the global market for these specialized devices demonstrated a steady, predictable growth trajectory. By the close of 2025, the sector had reached a revenue baseline of 850 million USD. Looking ahead across our 2026 to 2032 forecast horizon, the market is projected to advance at a compound annual growth rate of 2.5 percent, culminating in a market size near the one billion USD threshold by 2032. While these headline figures may appear measured compared to the explosive growth curves of advanced driver-assistance computing, they represent exactly the kind of stable, long-cycle reliability that automotive OEMs, Tier 1 suppliers, and component distributors require when mapping multi-year sourcing strategies and capacity investments.
8-bit Automotive Microcontrollers (MCU) Market
The 2026 Decision-Making Imperative: Navigating Supply Stability, Localization, and Certification Bottlenecks
The strategic value of this research is anchored in the unique market conditions observed as we entered 2026. After several years of pronounced volatility across semiconductor supply chains, lead times for microcontroller units have largely normalized. Automotive-grade device production has stabilized, allowing procurement teams to shift their focus from crisis management toward long-term contractual planning, inventory optimization, and supplier diversification. However, normalization does not equate to simplification. Geopolitical dynamics continue to accelerate the localization of automotive MCU production, including 8-bit variants, particularly across Asia as regional original equipment manufacturer supply chains seek greater autonomy and reduced cross-border dependency. For companies managing global sourcing portfolios, understanding where production is concentrating, how regional qualification requirements diverge, and which suppliers are expanding localized capacity is no longer a tactical concern; it is a structural competitive necessity.
8-bit Automotive Microcontrollers (MCU) Market
Simultaneously, regulatory and certification frameworks have matured into decisive gatekeepers for market access. 8-bit automotive MCUs commonly require AEC-Q100 Grade 0 qualification to guarantee reliable operation across extreme temperature ranges spanning from minus 40 degrees Celsius to 150 degrees Celsius, alongside ISO 26262 functional safety compliance for ASIL B applications. These standards are not mere technical checkboxes; they shape product roadmaps, influence design-in decisions, affect validation timelines, and ultimately determine which suppliers can credibly serve safety-critical vehicle functions. Our analysis maps how these compliance requirements interact with supply continuity, pricing structures, and architectural design choices, providing decision-makers with a realistic picture of regulatory exposure and certification-led procurement risk.
What the Report Delivers: A Working Intelligence Framework for Engineering, Procurement, and Commercial Strategy
This research has been designed as a practical asset rather than a static data compilation. It integrates historical performance analysis, forward-looking projections, segmentation intelligence, and competitive profiling into a unified decision-support structure. Readers will find detailed breakdowns that clarify how memory architecture type influences adoption patterns, how application domains dictate volume and qualification intensity, and how geographic concentration shapes regional sourcing strategies. The report examines the evolving balance between Flash-based and ROM or OTP-based device families, analyzing how each architecture aligns with distinct cost, flexibility, and performance requirements across vehicle subsystems. Application-level analysis dissects market activity across body electronics control, chassis and safety implementations, and powertrain and auxiliary functions, revealing where volume demand concentrates and where qualification complexity creates higher barriers to entry.
Beyond aggregate segmentation, the report provides an operational view of competitive concentration. The market remains structurally consolidated, with the top three players commanding a combined share of 68.5 percent and the top five collectively accounting for 82.4 percent. Such concentration has direct implications for pricing power, supply resilience, lead-time reliability, and negotiation leverage. Our strategic commentary explores how this structure affects supplier relationship management, how incumbent positioning influences design-in inertia, and where challenger or niche players may still create value through specialized features, packaging efficiency, or targeted regional service models.
Competitive Arena: How Leading Manufacturers Shape the Trajectory of 8-bit Automotive Control
The 8-bit automotive MCU competitive landscape is defined by a group of established semiconductor manufacturers, each leveraging distinct technology lineages, regional manufacturing footprints, and automotive qualification capabilities. Microchip Technology, headquartered in Chandler, Arizona, has built a recognized presence around AEC-Q100 Grade 0 certified PIC and AVR 8-bit MCU families. Its offerings are structured to support automotive communication requirements such as CAN and CAN FD, integrate functional safety capabilities aligned with ISO 26262 ASIL B expectations, and sustain high-temperature operation up to 150 degrees Celsius. These attributes position Microchip’s portfolio for body electronics, human-machine interface, and sensor-related applications where reliability and communication robustness are paramount.
STMicroelectronics, based in Geneva, Switzerland, continues to reinforce its stance in the segment through its STM8AF and STM8AL series, which emphasize high reliability, embedded data EEPROM, operation up to 150 degrees Celsius, and support for LIN, CAN, and low-power modes. These devices are oriented toward automotive body and powertrain applications where endurance, low-power efficiency, and established ecosystem support matter. Into 2026, STMicroelectronics has maintained active support for these series, supported by enhanced package options and expanded ecosystem tooling, a signal that mature 8-bit lines remain strategically relevant rather than being allowed to quietly phase out.
NXP Semiconductors, headquartered in Eindhoven, Netherlands, brings a legacy-rich portfolio built around S08 and earlier HC05, HC08, and HC11 families. With automotive qualification and CAN support, these offerings are positioned for cost-effective automotive and industrial control use cases where proven architecture and broad application familiarity reduce integration risk. Silicon Laboratories, based in Austin, Texas, takes a different value proposition, emphasizing integration density and package efficiency through its C8051F52x and C8051F5xx automotive-grade series. With features such as 12-bit analog-to-digital conversion and small-footprint packaging, these devices are suited to industrial and automotive sensor and control applications where space and signal processing capability must be balanced carefully.
Renesas Electronics, headquartered in Tokyo, Japan, contributes through its RL78 family, which spans 8-bit and 16-bit low-power architectures with automotive qualification. Its relevance in the 8-bit discussion stems from body control, lighting, and sensor applications where power efficiency and thermal performance align closely with subsystem design priorities. Infineon Technologies, based in Neubiberg, Germany, rounds out the competitive set through its XC800 A-family 8-bit automotive MCUs, designed for demanding applications where established qualification heritage and application breadth support continued deployment.
Recent developments in early 2026 underscore how these companies are managing their 8-bit lines in a transitioning market. STMicroelectronics has continued to signal ongoing availability and ecosystem enhancement for its STM8AF and STM8AL automotive series, reinforcing that mature product families can remain commercially supported when aligned with enduring application demand. Microchip Technology has drawn attention to its PIC18-Q83 and PIC18-Q84 alongside AVR DA and DD families, highlighting continued relevance for automotive CAN FD and touch applications backed by functional safety certifications. These moves illustrate a broader pattern: leading players are not simply defending legacy revenue; they are actively aligning 8-bit offerings with evolving communication protocols, user-interface expectations, and safety-certification demands.
Market Dynamics and Structural Forces Shaping 2026 and Beyond
The behavior of the 8-bit automotive MCU market is shaped by interacting forces that extend well beyond raw unit demand. At the regulatory level, qualification and functional safety expectations now act as structural filters. AEC-Q100 Grade 0 reliability requirements and ISO 26262 ASIL B alignment define the operational envelope within which suppliers must compete. For OEMs and Tier 1 integrators, these standards influence component selection not only through performance criteria but also through validation confidence, long-term availability assurance, and documented safety-case support. Products that can demonstrate robust qualification histories and clearly mapped functional safety coverage gain a distinct advantage in design-in negotiations, especially when vehicle programs move into later implementation phases with limited tolerance for re-qualification cycles.
At the supply chain level, the normalization of MCU lead times in 2026 has reframed how organizations approach inventory planning and contract structures. Automotive-grade devices are now maintaining stable production, which allows procurement teams to evaluate total cost of ownership more holistically rather than reacting purely to scarcity-driven pricing. Yet stability also exposes the importance of supplier-level resilience. Regional concentration, manufacturing footprint strategy, and logistics continuity all influence how smoothly a program can scale from prototype to volume production. The market analysis in this report connects these operational realities to broader procurement strategy, helping organizations weigh localization benefits against supplier diversification needs.
At the geopolitical level, the push toward regional production localization is a defining trend for the near term. In Asia, in particular, automotive MCU production including 8-bit variants is increasingly being shaped by regional OEM supply chain strategies that prioritize proximity, reduced exposure to transboundary disruptions, and greater control over qualification and logistics pathways. This shift does not simply redistribute capacity; it alters sourcing logic, changes the relative attractiveness of different supplier bases, and introduces new considerations for multinational programs that must coordinate design standards, production locations, and part-number continuity across regions. The report examines these dynamics without oversimplifying them, offering a structured view of how localization pressures may influence supplier selection and regional sourcing architecture over the forecast period.
Why This Research Matters Now: From Fragmented Intelligence to Coordinated Action
For many organizations, the challenge in 2026 is not a lack of available information but an excess of fragmented, low-context data. Market narratives often jump between high-level semiconductor growth themes and isolated product announcements without connecting them to sourcing implications, qualification pathways, or competitive position. This report is built to close that gap. It translates macro-level growth projections into decision-relevant context, links application-level demand patterns to procurement and engineering priorities, and situates competitive moves within the broader regulatory and supply-chain environment. That combination allows teams to make more coherent choices about supplier engagement, design-in timing, inventory posture, and regional sourcing strategy.
The base-year context of 2025 and the forecast horizon stretching through 2032 give the analysis a practical temporal anchor. Decision-makers can use the historical trend line to validate assumptions about stability and maturity, while the forward projections support scenario planning for capacity investment, program launches, and long-cycle component commitments. The currency-standardized revenue framework and consistent measurement units provide a common language across engineering, purchasing, and executive teams, reducing the risk that strategic discussions drift into incompatible assumptions.
How to Use This Intelligence for Competitive Advantage
The report is structured to support multiple internal use cases without requiring the reader to reconstruct the strategic logic from raw tables. Procurement and supply chain leaders can use the segmentation and concentration analysis to assess supplier reliance, evaluate regional sourcing alternatives, and plan for qualification-linked continuity risks. Engineering and program management teams can use the application and type-level discussion to align subsystem architecture choices with cost, integration, and reliability constraints. Commercial and market strategy teams can use the competitive profiles and recent development timelines to anticipate where incumbents are reinforcing support, where specialized feature differentiation is emerging, and where localized production shifts may alter negotiation dynamics.
Because the market is concentrated and the qualification bar is high, competitive advantage in this segment often comes from timing, documentation confidence, and supplier relationship depth rather than from dramatic product differentiation alone. Organizations that combine clear visibility into market structure with disciplined supplier management and forward-looking program planning are better positioned to secure design wins, avoid late-stage qualification surprises, and maintain continuity as regional supply strategies evolve. This research is intended to provide the visibility layer that makes such discipline possible.
Mapping the Road Ahead: Where to Focus as 2026 Unfolds
As the market moves deeper into the forecast period, several strategic questions will become increasingly central. How will localized production in Asia reshape supplier comparisons for regional programs? How will CAN FD adoption, functional safety documentation expectations, and high-temperature reliability requirements influence design-in choices across body electronics, chassis and safety, and powertrain applications? How will Flash-based and ROM or OTP-based device families continue to divide the market between flexibility, memory architecture, and cost considerations? And how should organizations interpret the stable growth profile of this segment when allocating attention and investment across a broader portfolio of automotive electronics components?
These are precisely the questions our full research is built to address. The introduction above highlights the analytical lens and the strategic framework, while the complete report provides the detailed segmentation breakdowns, competitive profiling, regional and application-level context, and forward-looking scenario structure needed for execution. To move from high-level direction to actionable market intelligence, organizations should review the full publication, where the data, analysis, and strategic interpretation are presented together in a consolidated format designed for direct application in 2026 planning cycles.
The 8-bit automotive MCU market may not command the same spectacle as advanced compute platforms, but its stability, qualification depth, and embedded role in vehicle subsystems make it a critical piece of the automotive supply chain. Understanding where it is heading, who controls its structure, and how regulatory and geopolitical forces are reshaping access is essential for sound strategy in 2026 and beyond. Our research offers that understanding in a form built for decision-makers who need clarity, continuity, and competitive context rather than surface-level trend summaries.
For detailed analysis of this topic, please visit the official page:8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com













Sign in to leave a comment.