
Navigating Growth and Transformation in the Global Automotive Air Filter Housing Market
The automotive air filter housing market stands at a critical inflection point as the industry balances mechanical reliability with the demands of electrification, stricter emissions regimes, and material innovation. In a sector where airflow management directly influences engine longevity, particulate control, and overall system efficiency, the air filter housing has evolved from a passive enclosure into an integrated functional component. As OEMs, Tier 1 suppliers, and aftermarket distributors recalibrate their strategies for the coming years, a clear, evidence-based view of market trajectories is essential. Our newly released Worldwide Automotive Air Filter Housing Market study provides precisely that lens, translating multi-year performance data and forward-looking forecasts into actionable intelligence for 2026 decision-making.
Why 2026 Is a Defining Moment for Strategic Planning
Market history offers both reassurance and caution. Between 2020 and 2025, global revenue for automotive air filter housings moved through a series of expansion and consolidation phases, reflecting production cycles, regional demand shifts, and supply chain adjustments. The trajectory over that period underscores how sensitive this component category is to broader automotive output, fleet refresh rates, and regulatory pressure on air intake cleanliness. Looking ahead, our forecast window through 2032 maps a steady growth path with a compound annual growth rate of 3.48 percent. This is not a narrative of explosive disruption; rather, it is a story of disciplined expansion, where incremental gains in vehicle parc, powertrain diversification, and functional integration compound over time.
For executives planning 2026 capex, sourcing, and product roadmaps, the value of a structured forecast lies in its ability to separate signal from noise. Short-term fluctuations can obscure longer-term directional shifts, especially in a market where production volumes, material choices, and regional mix interact in complex ways. The study frames the market size in USD millions across a historical baseline and a forward period, giving strategy teams a common reference for scenario planning. Instead of treating growth as a single headline figure, the analysis decomposes momentum into the drivers that actually matter: vehicle type mix, material adoption, regional demand centers, and the intensifying focus on filtration efficiency under tightening emission standards.
What the Market Size Trajectory Tells Us
The reported market size across recent years illustrates how demand has matured while remaining sensitive to macro conditions. From a baseline in 2020, revenue climbed through subsequent years, with a temporary contraction followed by renewed expansion into 2024 and 2025. The forecast period then projects a continued upward trend, with incremental year-over-year movement that reflects both volume recovery and value growth.Notably, the near-term projection for 2026 shows a measured adjustment before the market resumes a more pronounced ascent in the latter half of the decade. This pattern is exactly the kind of nuance that strategic planning requires: it prevents overcommitment to linear growth assumptions while highlighting where structural tailwinds are likely to reassert themselves.
Throughout the forecast horizon, the market is expected to surpass the 2,000 million threshold in the coming years, signaling a durable expansion phase. The growth is underpinned by sustained demand for replacement and service parts, ongoing model year introductions across passenger and commercial vehicles, and the continued need for housings that meet both functional and regulatory expectations. At the same time, the analysis remains grounded in the reality that raw material pricing, component standardization, and regional manufacturing footprints will shape margin structures and competitive positioning. By presenting the numbers in a coherent time series, the study enables planners to align procurement cycles, capacity decisions, and commercial offers with the rhythm of market expansion rather than reacting to isolated data points.
Worldwide Automotive Air Filter Housing Market
Segment Architecture Without the Fog of Over-Simplification
A market of this scale cannot be understood through a single lens. The study organizes demand across three analytical dimensions that matter most to suppliers and buyers: geography, material, and vehicle type. Each dimension carries distinct implications for product design, logistics, pricing, and go-to-market execution.
- Regionally, the analysis maps where demand is concentrated and how growth is distributed across major automotive ecosystems. Rather than presenting a flat global average, the report differentiates regional dynamics so that teams can assess which markets are likely to drive volume, which are evolving faster in terms of specification upgrades, and where aftermarket penetration offers the strongest incremental opportunity. This is especially relevant for organizations deciding how to allocate sales coverage, inventory positioning, and localized product support.
- By material, the market reflects a clear tilt toward plastic and composite constructions, a trend aligned with lightweighting objectives, cost efficiency, and the ability to integrate multiple functions into a single housing. At the same time, metal solutions retain a role where durability, thermal characteristics, or specific performance requirements dictate their use. The report examines how material selection influences total cost, supply resilience, and the pace at which advanced polymers are being adopted to meet weight and performance targets.
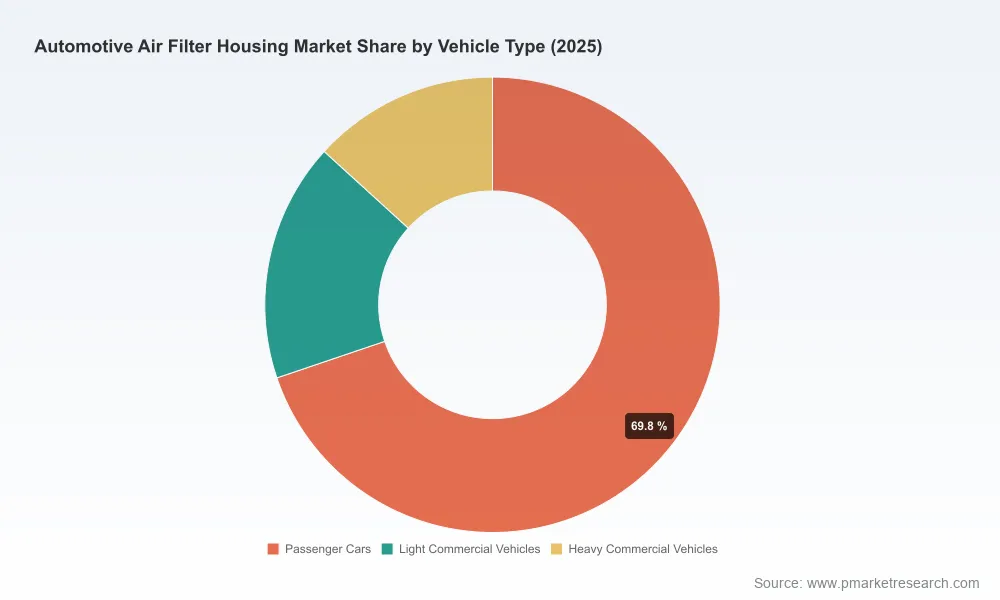
- By vehicle type, demand is assessed across passenger cars, light commercial vehicles, and heavy commercial vehicles. Each segment imposes different requirements on airflow control, filtration efficiency, service intervals, and environmental exposure. The study frames these differences in terms of product relevance and commercial opportunity, allowing stakeholders to prioritize development and commercial efforts where specification sensitivity and volume align.
Crucially, the report avoids the temptation to oversimplify by highlighting isolated percentage breakdowns or standalone monetary figures for each sub-segment in a way that could mislead without context. Instead, it weaves segmentation into a narrative about where value is created and how competitive advantage is won. This approach is designed for decision-makers who need to understand structural dynamics, not just static splits. The complete segmentation detail, including region-by-region and application-level quantification, is available in the full report for teams that require granular inputs for modeling and forecasting.
Competitive Positioning in a Consolidating Landscape
The competitive environment is characterized by a core group of established filtration and automotive technology players, with meaningful concentration among the largest participants. The market’s top three share approximately 38.4 percent of revenue, while the top five account for roughly 56.15 percent, indicating a landscape where scale, application breadth, and system-level integration matter. In such a setting, differentiation rarely comes from housing geometry alone. It increasingly depends on how well a supplier can combine filtration performance, airflow optimization, functional integration, and supply reliability across multiple vehicle platforms.
Several companies define the current center of gravity. MANN+HUMMEL continues to position itself as a global filtration specialist with complete air cleaner systems and housings spanning passenger cars, commercial vehicles, and a wide engine range, while also emphasizing functional integrations such as acoustics, water separation, and styling elements. In mid-2025, the company continued to promote advanced air cleaner systems with functional integrations for modern powertrains, reinforcing a focus on efficiency enhancements linked to sustainable transportation. MAHLE GmbH complements this landscape with air cleaner systems and housings designed around high filtration efficiency, precise air flow measurement for engine control, minimized pressure loss, and support for reduced emissions and fuel consumption.
Automotive Cabin Air Filter Market
Donaldson Company, Inc. brings a broad filtration technology footprint, supplying engine air intake systems, air cleaner housings, and assemblies across on-highway, off-road, and industrial automotive applications, with extensive OEM and aftermarket offerings. Freudenberg Filtration Technologies contributes deep expertise in filter media and automotive air filtration solutions, targeting engine protection for passenger and commercial vehicles. Robert Bosch GmbH enters the space as a wideband automotive technology supplier, integrating filtration components and air filter housings into engine management systems across diverse vehicle platforms. Röchling Automotive’s specialization in plastic air intake systems and air box housings adds another dimension, combining intake and piping functions to optimize airflow, fuel efficiency, and engine performance in automotive and motorcycle applications. Hengst SE rounds out this group with filtration solutions that emphasize high performance and integration in engine air filter housings and modules.
What ties these players together is not merely product presence, but the strategic intent behind it. As emission norms tighten and engines become more sensitive to particulate ingress, the housing becomes part of a broader system-level value proposition. Suppliers that can deliver consistent filtration efficiency, predictable airflow behavior, and packaging flexibility gain leverage in both OEM programs and service channels. The study examines these competitive dynamics in depth, mapping capability sets, application coverage, and recent moves that signal where each participant is trying to create differentiation. The objective is to help buyers and competitors alike read the market not as a list of names, but as a network of strategic priorities.
Regulatory and Material Forces Shaping Demand
No analysis of this market is complete without acknowledging the external forces that affect product requirements and cost structures. Stringent global emission standards for new motor vehicles, including heavy-duty engines, continue to drive requirements for effective air intake filtration and housing designs that support reduced particulate matter and improved engine control accuracy. These regulatory expectations raise the bar for filtration performance and push manufacturers to ensure that housings contribute to consistent, controlled airflow under real-world conditions.
At the same time, technical expectations for filtration efficiency remain demanding. Engine air filtration systems must achieve high efficiency, with traditional cellulose media commonly targeting around 99.9 percent at 2 to 5 µm particles, in order to meet performance expectations under tightening vehicle emission norms. This level of performance is not achieved by the filter element alone; the housing plays a supporting role in sealing, flow uniformity, service access, and integration with sensors and engine management logic. As a result, design decisions that once belonged primarily to mechanical packaging now carry direct consequences for compliance and durability.
On the materials side, automotive air filter housings predominantly utilize plastic and composite materials for lightweight construction and durability, with ongoing shifts toward advanced polymers to meet performance and weight reduction targets. This transition is sensible from a design perspective, but it also introduces cost volatility. Fluctuating prices of key raw materials such as polypropylene used in filter housings and related components impact production costs in the automotive filtration sector. For planning teams, this means that margin management and sourcing strategy are increasingly intertwined with material innovation. The study addresses these dynamics as part of its broader market assessment, helping readers understand how regulatory requirements, efficiency targets, and input costs interact to shape competitive outcomes.
What the Study Delivers for Operational and Commercial Teams
Beyond macro trends and competitive snapshots, the report is built around practical outputs that can be used immediately in planning cycles. It provides a structured view of market size over historical and forecast periods, contextualized by the drivers that explain movement rather than simply reporting it. Segmentation is presented through the lenses of region, material, and vehicle type so that teams can evaluate where demand is strongest, where specification upgrades are most likely, and where aftermarket and service-channel opportunities may grow. The concentration data offers a realistic perspective on market structure, helping both incumbents and new entrants understand the scale required to compete effectively and the value of system-level differentiation.
The study also translates recent developments into strategic reading. Continued product and systems-offering updates, such as the promotion of advanced air cleaner systems with functional integrations for modern powertrains, are interpreted not as isolated announcements but as indications of where suppliers are placing bets on efficiency, packaging, and sustainability. Similarly, the report situates raw material dynamics and regulatory pressure within a practical framework, enabling procurement, engineering, and commercial teams to assess risk and opportunity together rather than in isolation. For organizations that need to build business cases, prioritize SKUs, align regional plans, or evaluate partnership and sourcing options, the report is designed to reduce uncertainty and sharpen the basis for decision-making.
Using This Intelligence to Shape 2026 Decisions
The most valuable use of this research is not to memorize figures, but to embed them into a coherent strategy. For product planning, the forecast and segmentation help determine where to invest in housing designs that balance lightweighting, integration, and filtration support. For commercial strategy, the regional and vehicle-type perspective supports prioritization of OEM engagement, aftermarket distribution, and service-part portfolios. For competitive strategy, the concentration data and company profiles offer a basis for understanding where market share is being defended, where differentiation is emerging, and where consolidation pressure may intensify.
In practical terms, the study is meant to support three classes of decisions. First, it informs capacity and sourcing alignment by clarifying the pace and shape of demand growth. Second, it supports product and specification strategy by linking material choices and functional integration to market expectations. Third, it strengthens commercial positioning by clarifying how regulatory and efficiency requirements are reshaping buyer priorities. Taken together, these elements help organizations move from reactive adjustment to deliberate planning.
Getting the Full Picture
The Worldwide Automotive Air Filter Housing Market study is built for leaders who need market intelligence that is both rigorous and usable. The overview presented here captures the direction, structure, and strategic relevance of the market, but the complete analysis contains the deeper segmentation, competitive detail, and scenario-relevant inputs that make the difference between general awareness and actionable planning. For teams preparing 2026 roadmaps, evaluating opportunities, or recalibrating competitive assumptions, the full report offers the level of detail required to turn market insight into informed decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Air Filter Housing Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com























Sign in to leave a comment.