
Strategic Intelligence in a High-Value Precursor Market: Why the Worldwide Aluminum Dimethyl Isopropoxide Report Matters for 2026 Planning
As advanced manufacturing ecosystems accelerate their transition toward finer geometries, tighter process controls, and highly specialized material requirements, the choice of chemical precursors has become a decisive competitive variable. Aluminum Dimethyl Isopropoxide, long recognized as a critical organometallic precursor for thin-film deposition and catalytic processes, now sits at the intersection of semiconductor scaling, materials innovation, and supply chain reconfiguration. For executives, procurement leaders, and technology strategists, understanding where this market is heading is no longer optional. It is a core input to capital allocation, supplier qualification, and product roadmap decisions.
Worldwide Aluminum Dimethyl Isopropoxide Market
Our newly released Worldwide Aluminum Dimethyl Isopropoxide Market research was designed to meet that need. It offers a structured, data-grounded assessment of market size, growth trajectory, segmentation behavior, competitive positioning, and regulatory dynamics across the forecast horizon. Rather than presenting isolated figures, the study weaves together historical performance and forward-looking indicators to help organizations interpret the market signals that will shape 2026 and the years beyond.
Worldwide Aluminum Dimethyl Isopropoxide Market
This article provides a strategic preview of the report’s analytical framework and the operational questions it is built to answer. It highlights the macro trajectory, the forces reshaping demand and supply, the competitive structure that influences purchasing power, and the practical contents of the study that make it usable for immediate decision-making.
Worldwide Aluminum Dimethyl Isopropoxide Market
The Macro Trajectory: What the Numbers Reveal About Growth and Transition
Over the historical window from 2020 through 2025, the worldwide market for Aluminum Dimethyl Isopropoxide has moved through a period of steady expansion punctuated by structural shifts in end-use demand and production maturity. The reported revenue base for 2025 stands near 92.45 million USD, reflecting a cumulative climb from the 2020 baseline of 68.42 million USD. That progression is more than a simple annual increase; it marks the market’s transition from a niche specialty-chemical segment to a more established input channel within high-purity materials supply chains.
Looking forward, the forecast period from 2026 through 2032 points to continued expansion, with the market projected to reach approximately 102.48 million USD in 2026 and continue rising toward 140.11 million USD by 2032. The implied compound annual growth rate of 6.12 percent signals a market that is neither stagnant nor explosively speculative, but one advancing with durable, application-led momentum. For strategic planners, that kind of trajectory has practical consequences. It suggests that long-term supplier commitments, capacity planning, and R&D alignment should be calibrated for sustained demand rather than short-lived surges.
At the same time, the year-by-year forecast path does not imply a perfectly smooth ascent. Growth remains uneven across phases, reflecting the interplay of product qualification cycles, capital investment timing, and regional manufacturing dynamics. The report examines those inflection points in detail so that readers can distinguish between underlying structural growth and temporary fluctuations driven by procurement timing, inventory adjustments, or technology adoption lags.
Demand Architecture: Where Value Is Formed Across Application and Purity Segments
One of the most strategically important dimensions of this market is not simply how large it is, but how value is distributed across applications and purity grades. The report structures the segmentation analysis to show how demand concentrates in areas where precursor performance, consistency, and certification matter most.
In application terms, the market is led by Semiconductor Layer Deposition, which accounts for the largest share of demand at 58.67 percent. This concentration is consistent with the broader industry shift toward advanced deposition processes that require highly controllable precursor chemistry for dielectric films, barrier layers, and functional coatings. Catalyst for Polymerization follows at 20.97 percent, reflecting continued reliance on organoaluminum compounds in polymer synthesis and specialty chemical manufacturing. Glass and Ceramic Coatings represents a further 12.81 percent, underscoring the material’s role in surface engineering and functional finish applications. Rather than treating these applications as equivalent markets, the study maps their distinct purchasing behaviors, qualification durations, and growth sensitivities.
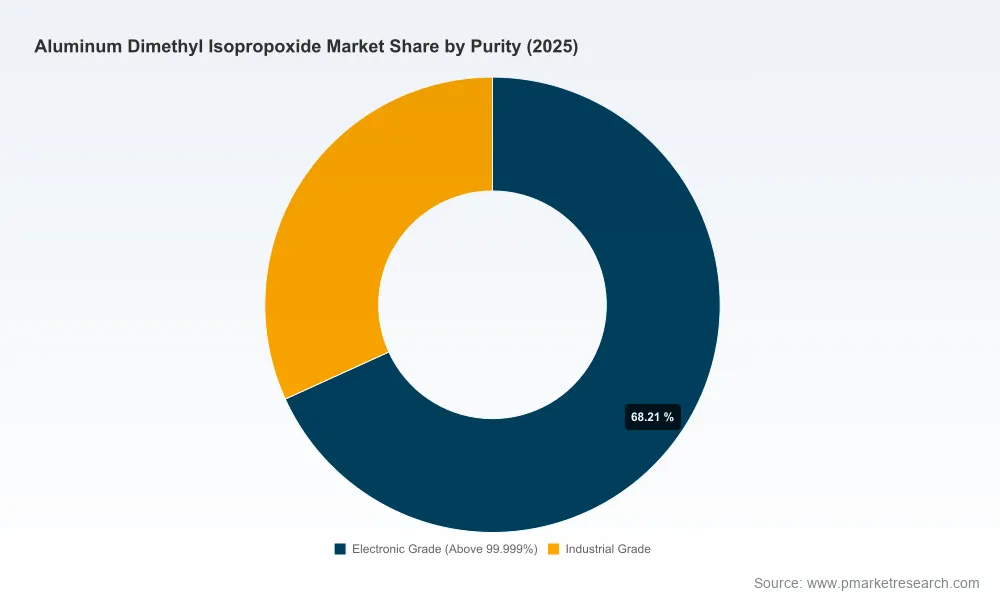
Purity segmentation adds another layer of strategic insight. Electronic Grade material, defined as above 99.999 percent purity, commands 63.06 percent of the market, while Industrial Grade accounts for 29.39 percent. This split highlights a critical reality: in high-value end uses, the premium is not just for volume but for repeatability, contamination control, and process compatibility. The analysis shows how purity requirements influence pricing logic, supplier selection, logistics constraints, and the cost of non-conformance. For organizations operating in or supplying to the electronics value chain, this is often the difference between a transaction-based purchasing relationship and a long-term technical partnership.
Regional distribution further refines the picture. Asia Pacific represents the largest regional share at 43.59 percent, followed by North America at 24.07 percent, Europe at 18.3 percent, and Rest of World at 6.49 percent. These proportions do more than locate demand; they indicate where supplier proximity, logistics resilience, and regional compliance frameworks matter most. The report uses this regional structure to explore how supply strategies differ across markets with distinct manufacturing density, import dependency, and regulatory expectations.
Competitive Structure and the Meaning of Concentration
The competitive landscape for Aluminum Dimethyl Isopropoxide is shaped by a combination of specialty manufacturing expertise, application-specific qualification requirements, and distribution reach. Market concentration remains notable, with the top three firms holding approximately 58.4 percent of the market and the top five firms reaching about 74.15 percent. That level of concentration has practical implications for pricing, availability, negotiation leverage, and supply continuity.
The study profiles leading participants whose activities illustrate the market’s different strategic models. Ereztech LLC operates as a specialty manufacturer and supplier of high-purity Aluminum Dimethyl Isopropoxide for ALD and MOCVD applications, with offerings that span research and commercial quantities. Strem Chemicals, Inc. supplies Dimethylaluminum i-propoxide in PURATREM grade for precursor use in atomic layer deposition and related processes, positioning itself around purity assurance and process readiness. American Elements functions as a global manufacturer and supplier of the compound in both commercial and research quantities, reflecting a broader portfolio approach. Dock Chemicals produces DMAliP as an aluminum precursor specifically for MOCVD and ALD applications, emphasizing the process-specific nature of the demand. Wonik Materials North America supplies dimer-form Dimethylaluminum isopropoxide for semiconductor and thin-film deposition processes, while Parchem Fine & Specialty Chemicals operates as a distributor supplying the compound worldwide within its specialty chemicals portfolio.
These profiles are not presented merely as a company list. They are used to illustrate how different business models compete on different axes: some through ultra-specialized precursor engineering, some through certified purity and reproducibility, some through global distribution capability, and some through application-adjacent technical support. For procurement and strategy teams, the report’s competitive analysis is designed to support supplier evaluation, second-source planning, and risk diversification decisions.
Because the market is concentrated, buyers often face a trade-off between supplier expertise and supply resilience. The study addresses that tension directly by mapping how qualification barriers, production scale, and geographic coverage shape the practical options available to buyers in different regions and application categories.
Regulatory, Safety, and Technical Dynamics That Redefine Procurement Risk
Market growth does not occur in a vacuum. In this segment, safety classification and handling requirements influence not only operational cost but also shipping feasibility, warehousing design, inventory planning, and supplier qualification scope. Aluminum Dimethyl Isopropoxide is classified as a highly flammable liquid and vapor with water-reactive properties, which means its transport and storage must align with specialized handling frameworks, including ADR/RID regulations. For multinational operations, these requirements create material differences in lead times, total cost of ownership, and acceptable supplier locations.
A related technical dynamic concerns the compound’s role as a nonpyrophoric alternative precursor to trimethylaluminum in plasma-enhanced atomic layer deposition of Al2O3 thin films. This positioning matters because it ties the market to evolving process preferences in deposition engineering. As manufacturers balance performance, safety, and process compatibility, precursor choice becomes a variable that can affect not just material spend but also process design and equipment utilization. The report situates these technical considerations within the broader commercial landscape so that readers can evaluate demand shifts with an understanding of why certain process routes gain traction over time.
Upstream feedstock relationships also shape market behavior. Trimethylaluminum serves as a primary upstream organoaluminum feedstock in the synthesis routes for dimethylaluminum isopropoxide. That link means the market is indirectly exposed to feedstock availability, pricing pressure, and process economics in adjacent organoaluminum chemistry. The study incorporates this dependency to help readers interpret cost trends and supply risk more accurately, rather than treating the product as an isolated commodity.
Report Contents: Practical Tools for 2026 Decision-Making
The full study is built to move beyond market description and into operational use. It is structured so that different functions within an organization can extract the intelligence they need without wading through undifferentiated data.
The report provides a comprehensive market sizing and forecast framework covering historical performance and the full forecast period through 2032. This framework is paired with segmentation analysis across region, purity, and application so that readers can interpret growth by the dimensions most relevant to their business. Rather than presenting segmentation as static percentages, the study explains how each segment behaves in terms of demand drivers, purchasing logic, and sensitivity to technical or regulatory changes.
A dedicated competitive section examines the major participants, their operating models, and the implications of market concentration for buyer strategy. This section is intended to support supplier benchmarking, sourcing strategy, and market-entry assessment. The report also covers the regulatory and safety context that influences handling, transport, and compliance costs, along with the upstream feedstock environment that affects production economics.
In addition to macro and competitive analysis, the study is designed to help answer practical questions such as:
- Where is demand growth most likely to concentrate over the forecast period, and what factors support that concentration?
- How do purity requirements change the economics of procurement and supplier qualification?
- Which regions present the strongest combination of demand scale, supply maturity, and logistical feasibility?
- What does market concentration imply for negotiation strategy and supply resilience?
- How do safety classifications and handling requirements alter total cost and sourcing options?
These questions are addressed through a combination of quantitative context and qualitative interpretation. The goal is to give readers a defensible basis for planning rather than a simple set of numbers to cite.
Strategic Takeaways for 2026 and Beyond
For organizations making decisions in 2026, the most valuable insight is that this market is expanding with discipline rather than volatility. A 6.12 percent compound annual growth rate over a multi-year horizon indicates that demand is being pulled by real application needs, especially in semiconductor-related deposition and related high-purity uses. At the same time, the concentration of value in Electronic Grade material and in the Semiconductor Layer Deposition application means that performance, consistency, and qualification capability remain the dominant differentiators.
The regional distribution reinforces the need for geography-aware sourcing strategies. With Asia Pacific, North America, and Europe representing the bulk of demand, supply strategies must account for local compliance expectations, logistics constraints, and the proximity of qualified suppliers. The presence of both manufacturers and distributors in the competitive set also means that buyers can choose between direct technical engagement and broader distribution-based flexibility depending on their volume, urgency, and qualification stage.
Finally, the regulatory and upstream feedstock context is a reminder that total cost and supply resilience extend well beyond unit price. Handling requirements, transport classification, and feedstock-linked production dynamics can materially influence availability and cost structure. The report integrates these factors so that planners can assess the market with a more complete view of risk and value.
Next Steps for Decision-Makers
This preview is intended to show the analytical depth and operational relevance of the Worldwide Aluminum Dimethyl Isopropoxide Market study, while leaving the detailed segmentation values, full regional breakdowns, and complete forecast series for the full report. Those deeper contents are where the strategic nuance lives: the exact market sizing path, the complete segmentation structure, the company-level competitive profiles, and the applied context that connects market behavior to procurement and planning choices.
For teams preparing sourcing strategies, capacity plans, supplier qualification pipelines, or technology roadmaps in 2026, the full report provides the structured intelligence needed to move from general market awareness to specific, actionable conclusions. It is designed to support decisions that require both confidence in the numbers and understanding of the forces behind them.
For detailed analysis of this topic, please visit the official page:Worldwide Aluminum Dimethyl Isopropoxide Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com






















Sign in to leave a comment.