
Executive Brief: Navigating the Simulation Business Mobile Game Market Through 2032
The global simulation business mobile game market stands at a pivotal inflection point, transitioning from a niche entertainment segment to a mainstream digital economy vehicle. As player behaviors evolve toward immersive, management-heavy experiences, developers and investors alike require a rigorous, data-backed framework to anticipate shifts in monetization, platform dependency, and competitive positioning. This research digest introduces PW Consulting’s latest Worldwide Simulation Business Mobile Game Market study, engineered specifically to equip enterprise decision-makers with actionable intelligence for 2026 strategy formulation.
Rather than offering a static snapshot, the analysis maps the sector from a 2020 historical baseline through a forecast window extending to 2032. The methodology synthesizes publisher disclosures, platform telemetry, regional consumption patterns, and monetization telemetry to establish a clear trajectory for revenue expansion. In an industry where infrastructure costs are rising, platform economies are consolidating, and player acquisition channels are fragmenting, such a longitudinal view is indispensable. The following sections outline the strategic architecture of the report, highlight the operational dimensions covered, and demonstrate how executives can translate these findings into capital allocation, product roadmapping, and market entry decisions.
Strategic Context: Why 2026 Demands a Forward-Looking Simulation Market Lens
Entering 2026, the simulation business mobile gaming landscape is shaped by converging technological, economic, and behavioral forces. Players increasingly seek persistent virtual economies, asynchronous multiplayer competition, and management mechanics that mirror real-world operational decision-making. Simultaneously, publishers face mounting pressure to optimize user acquisition costs, extend lifetime value through layered monetization, and maintain cross-platform compatibility without sacrificing session depth.
The market’s historical trajectory underscores this momentum. From approximately 10,540.25 million USD in 2020, sector revenue climbed steadily to 11,446.3 million USD in 2021 and 13,096.29 million USD by 2022, reflecting early adoption of mobile-first simulation loops and growing acceptance of free-to-play management titles. The subsequent years accelerated this expansion: 13,686.83 million USD in 2023, 15,860.48 million USD in 2024, and an estimated 17,620.0 million USD in 2025. As the base year closes, the forecast period projects continued scaling, reaching 19,908.94 million USD in 2026 and advancing to 36,767.28 million USD by 2032.
Worldwide Simulation Business Mobile Game Market
This growth curve is anchored by a compound annual growth rate of 11.08 percent across the 2026 to 2032 forecast window. Such a rate signals more than incremental expansion; it indicates structural demand across multiple player demographics and monetization layers. For enterprise planners, this trajectory suggests that simulation mobile titles are no longer experimental experiments but established revenue architectures requiring dedicated operational support, community management, and live-service economics. The report translates this macro momentum into scenario-ready frameworks, enabling leadership to align product pipelines with realistic demand windows rather than speculative peaks.
Market Architecture: Revenue Scale, Concentration, and Structural Shifts
Understanding how revenue distributes across the ecosystem is as critical as tracking headline growth. The analysis examines market concentration through the lens of top-tier publishers, revealing a moderately consolidated landscape where the top three participants command roughly 31.4 percent of total revenue, while the top five capture approximately 46.85 percent. This distribution pattern carries strategic implications: it confirms that room remains for agile studios, regional publishers, and niche genre specialists to capture meaningful share, yet it also underscores how established mobile operators leverage cross-title ecosystems, live-ops maturity, and proprietary analytics to sustain competitive moats.
Revenue architecture is further dissected across functional simulation categories. Farming and city-building experiences represent the largest operational block, reflecting sustained player appetite for spatial management, resource sequencing, and community-driven progression. Life and career simulation titles form the second pillar, leveraging identity-driven progression and role-based decision loops that resonate with audiences seeking personal agency within virtual economies. Restaurant and shop management simulations contribute a distinct but robust revenue stream, capitalizing on time-management mechanics, tiered upgrade systems, and social coordination features. Transport and logistics simulation titles, though comparatively smaller in absolute terms, demonstrate specialized demand among players who favor supply-chain optimization, route planning, and efficiency-driven gameplay loops.
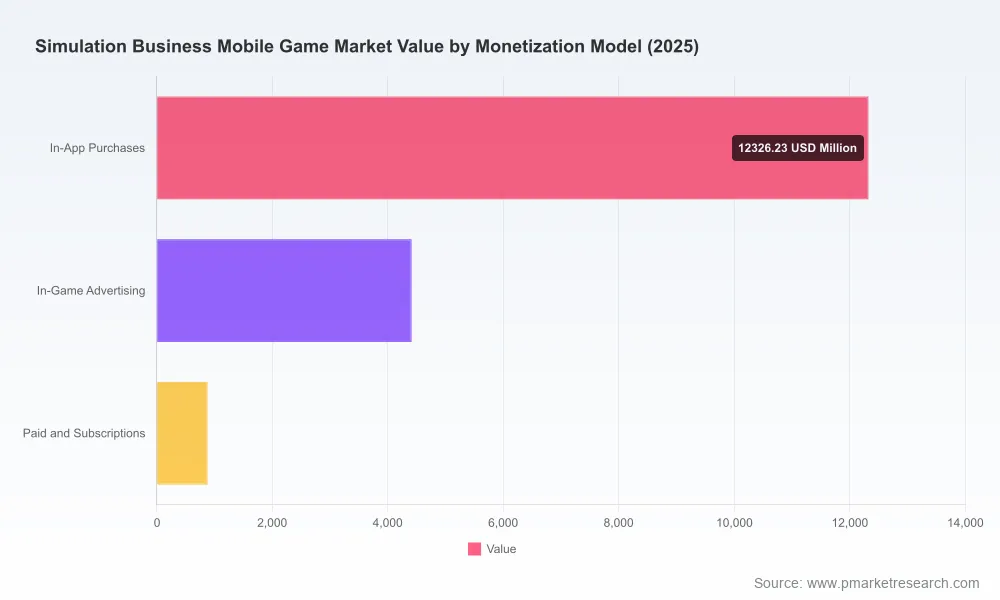
Monetization architecture is analyzed with equal granularity. In-app purchases constitute the dominant commercial engine, reflecting the sector’s reliance on progression acceleration, cosmetic customization, energy management, and premium feature gating. In-game advertising represents a complementary revenue layer, particularly effective in titles that balance session frequency with non-intrusive ad integration and rewarded formats. Paid and subscription models, while representing a smaller slice of total revenue, are highlighted as strategic differentiators in select premium or hybrid designs, offering predictable revenue streams and stronger player retention signals.
Regional revenue dispersion is also mapped without reducing the analysis to simplistic share percentages. The report examines consumption intensity, platform adoption rates, local payment behaviors, and localization effectiveness across major geographies, illustrating how simulation titles adapt to varying player expectations, device penetration patterns, and regulatory environments. By presenting these variables as interdependent drivers rather than isolated tabulations, the study equips strategists with a practical lens for evaluating market entry timing, content localization priorities, and distribution channel selection.
Inside the Report: Analytical Depth and Operational Utility
The study is structured for direct integration into corporate planning workflows. Beyond headline figures, it delivers a multi-layered operational blueprint designed to support portfolio reviews, investment memos, and product strategy sessions. Key content pillars include:
- Historical reconstruction and forecast methodology detailing data sources, validation steps, and scenario adjustments that govern the 2020 through 2032 revenue mapping.
- Segment-level demand analysis examining how simulation subtypes differ in session behavior, churn sensitivity, monetization elasticity, and content refresh cadence.
- Monetization performance frameworks comparing how in-app purchase depth, advertising fill quality, and subscription attachment rates influence lifetime value across title archetypes.
- Competitive positioning matrices linking publisher capabilities, studio scale, platform relationships, and live-service maturity to share retention patterns.
- Localization and distribution guides addressing app store dynamics, payment infrastructure variance, content approval pathways, and regional marketing spend efficiency.
- Risk and sensitivity considerations covering platform policy shifts, infrastructure cost exposure, user acquisition volatility, and retention pressure under changing session economics.
Each section is formatted for executive readability while retaining analytical rigor. Decision-makers can extract scenario inputs for financial modeling, clarify which simulation sub-genres align with target audience profiles, and identify where operational investment yields the highest probability of sustainable engagement. The report intentionally avoids superficial trend summaries; instead, it provides structured evaluation tools that can be adapted to internal dashboards, competitive review cycles, and portfolio prioritization exercises.
Competitive Landscape: Publisher Profiles, Positioning, and Strategic Implications
The market’s competitive fabric is shaped by a diverse set of operators, each pursuing distinct simulation positioning strategies. Electronic Arts, headquartered in Redwood City, California, maintains a recognizable footprint through titles such as The Sims FreePlay and SimCity BuildIt, combining city-building, management, and economic loops within mobile-first frameworks. Its operational emphasis illustrates how established franchises extend into mobile simulation by balancing brand recognition with continuous live-ops content delivery.
Tencent Games, based in Shenzhen, operates as a major publisher with broad reach across mobile simulation and tycoon-style experiences. Its portfolio strategy demonstrates how scale, cross-market distribution, and ecosystem integration can support simulation titles that rely on high-volume user engagement and layered in-app economies. NetEase Games, headquartered in Hangzhou, contributes additional depth to the mobile simulation ecosystem through titles incorporating simulation elements and management mechanics, reinforcing the importance of versatile development pipelines capable of serving multiple audience segments.
Smaller- and mid-scale studios also exert meaningful influence. NimbleBit, operating in the United States, develops casual mobile simulation and tycoon-style games with business management mechanics, showing how focused design, recognizable art direction, and streamlined progression can capture dedicated audiences without requiring massive live-ops budgets. Alawar, based in Novosibirsk, Russia, publishes simulation business mobile games with an emphasis on tycoon and management themes, highlighting how regional publishers can leverage specialized genre expertise and international distribution to sustain portfolio performance.
Digital-first and independent operators add further variety. Sim Companies functions as a dedicated mobile-accessible business simulation environment where players build and manage virtual companies within a dynamic economy, emphasizing competitive benchmarking, market pricing, and inter-player economic interaction. SomaSim, based in the United States, develops city-building and management simulation games with business elements available on mobile platforms, illustrating how narrative-adjacent management mechanics can coexist with operational depth. Playrix, with operations spanning Dublin and earlier Russian origins, is recognized for high-performing mobile simulation titles featuring strong management and tycoon elements, underscoring how polished progression systems and asynchronous social mechanics can drive broad commercial appeal.
Microsoft, headquartered in Redmond, Washington, supports simulation titles through its gaming and platform divisions, with business and management mechanics reaching mobile audiences via broader ecosystem connections. This presence reflects how platform holders can influence simulation market dynamics through cross-device accessibility, account integration, and distribution pathways that extend beyond standalone apps.
Taken together, these profiles reveal a market where competitive advantage depends on more than catalog size. Success increasingly correlates with content refresh discipline, monetization calibration, community retention design, and the ability to localize management loops without diluting core gameplay intent. The report translates these observations into actionable positioning guidance, helping strategists anticipate where consolidation pressure may intensify, which studio types are best suited for niche expansion, and how publisher relationships may shape distribution and monetization opportunities through 2032.
Macroeconomic and Infrastructure Signals Shaping Simulation Game Economics
Long-range forecasting in the simulation mobile game sector must account for external economic and infrastructure shifts that influence development costs, server economics, and platform service pricing. Recent industry signals point to a notable tightening in the underlying compute and energy environment. US investor-owned utilities have outlined substantial capital spending plans for grid infrastructure upgrades through 2030, responding in part to surging electricity demand from data centers supporting digital services, including mobile gaming ecosystems. Hyperscale providers are simultaneously planning extensive data center project spending for 2026 alone to sustain cloud compute capacity for services and applications. Alongside these investments, data center construction costs have climbed to a higher per-watt range, reflecting a significant increase relative to prior periods.
Worldwide Simulation Game Market
While these developments originate outside the game publishing value chain, they carry strategic relevance for simulation mobile game operators. Titles with persistent server-side economies, asynchronous multiplayer synchronization, cloud-based progression, and continuous analytics pipelines are exposed to infrastructure pricing dynamics that can affect live-ops budgets and scaling decisions. The report incorporates these background factors not as peripheral commentary, but as part of a broader operational risk assessment, helping strategists evaluate cost sensitivity, platform dependency, and architectural choices when planning long-duration simulation titles.
By connecting infrastructure trends to practical planning considerations, the study ensures that 2026 decision-makers do not treat revenue projections in isolation. Instead, they can weigh growth potential against operational cost trajectories, balance local-device and server-dependent design choices, and align product roadmaps with realistic service economics.
Applying the Findings: Strategic Applications for 2026 Decision-Making
The study is designed to support concrete organizational actions rather than abstract observations. For executive teams, the most immediate value lies in translating forecast cadence into planning discipline. Revenue expansion from the 2026 baseline to the 2032 horizon provides a quantitative backdrop for capacity planning, content investment sequencing, and monetization roadmap design. The concentration data clarifies how aggressively to pursue share gains versus defending existing positions, while segment and monetization breakdowns inform which simulation archetypes merit deeper development resources.
Game studios can use the analysis to refine genre positioning, evaluate whether farming, city-building, life simulation, shop management, or transport-logistics mechanics best match target audience behavior, and determine how to structure progression and monetization without overloading session economics. Publishers considering regional expansion can draw on the geographic consumption and localization discussion to prioritize markets where payment habits, device profiles, and player expectations align with their design strengths. Investors reviewing exposure to simulation mobile games can incorporate concentration metrics, publisher profiles, and infrastructure context into valuation and portfolio risk assessments. Platform and service providers can likewise use the report’s structural analysis to anticipate demand for cloud-backed simulation features, live-ops tooling, and analytics services that support management-heavy mobile titles.
Throughout, the study maintains a deliberate balance: it provides enough methodological transparency and market architecture to establish professional credibility, while reserving the most granular segmentation figures, regional detail tables, and company-level revenue estimates for the full dataset. This design reflects the practical reality that enterprise strategy requires context before commitment. Decision-makers gain the conceptual framework, comparative benchmarks, and strategic logic needed to ask the right questions before requesting the exact numbers that inform final budget allocations.
Conclusion: Positioning for the Next Phase of Simulation Mobile Growth
The worldwide simulation business mobile game market is entering a phase where scale, monetization discipline, and operational resilience must advance together. Historical revenue growth has already validated the segment’s commercial relevance, and the forecast horizon through 2032 suggests that management-oriented mobile experiences will remain central to player engagement strategies across multiple demographics. For organizations planning 2026 initiatives, the challenge is no longer whether simulation mobile games matter, but how to navigate their internal segmentation, competitive concentration, monetization complexity, and infrastructure-linked cost pressures with precision.
PW Consulting’s Worldwide Simulation Business Mobile Game Market research addresses that challenge by combining longitudinal market sizing, segment architecture, publisher profiling, and operational risk context into a single strategic reference. It is built for teams that need more than high-level trends: it offers a structured lens for portfolio design, market prioritization, and investment rationale. To access the complete segmentation breakdowns, extended regional detail, and full forecast tables that support end-to-end planning, consult the source market research page and integrate the full dataset into your 2026 decision framework.
For detailed analysis of this topic, please visit the official page: Worldwide Simulation Business Mobile Game Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com























Sign in to leave a comment.