
Navigating the Precision Frontier: Strategic Insights for the HD Map Market in 2026
Introduction: The Critical Role of High-Definition Mapping
The automotive industry is undergoing a seismic shift driven by the pursuit of higher levels of automation and connectivity. At the heart of this transformation lies the High-Definition (HD) Map Market, a foundational infrastructure that enables vehicles to perceive their environment with centimeter-level accuracy. Unlike traditional navigation maps, HD maps provide detailed geometric and semantic information essential for Advanced Driver Assistance Systems (ADAS) and autonomous driving functions. As we move into 2026, the demand for precise spatial data is no longer a future consideration but a present operational necessity for automotive manufacturers, mobility service providers, and infrastructure planners.
This industry insight serves as a precursor to our comprehensive market research report. It outlines the macroeconomic trajectory, competitive intensity, and operational complexities defining the sector. While we highlight the strategic landscape here, the full depth of quantitative analysis and segmentation data is reserved for the detailed study. Understanding the broad strokes is vital, but accessing the granular intelligence is what separates informed speculation from actionable strategy.
Macro Market Trajectory and Growth Indicators
The financial trajectory of the HD Map Market indicates robust expansion over the coming years. Our analysis tracks historical performance from 2020 through 2025 and projects forward momentum until 2032. In 2025, the market established a significant revenue baseline, reflecting accelerated adoption rates across key automotive sectors. Looking ahead to 2026, the market is poised to reach substantial valuation milestones, continuing a steep upward curve.
The compound annual growth rate (CAGR) observed during the forecast period underscores the velocity of this expansion. This growth is not linear; it is propelled by specific technological breakthroughs and regulatory mandates that are shifting HD mapping from a luxury add-on to a core component of vehicle architecture. Stakeholders must recognize that the value pool is expanding rapidly, creating both opportunities for revenue generation and risks for those who lag in integration capabilities. The report details these projections extensively, offering a clear view of the revenue landscape without exposing the specific sensitivity of segmented forecasts here.
Key Growth Drivers
Several underlying factors are fueling this market expansion. The primary driver remains the escalating deployment of autonomous driving technologies. As vehicles move toward higher SAE levels, the reliance on static map data to complement sensor suites becomes critical. HD maps reduce the computational load on onboard systems by providing prior knowledge of the road environment, lane markings, and traffic signs.
Additionally, regulatory frameworks are increasingly mandating data precision. Safety regulations require accurate speed limit information for Intelligent Speed Assistance (ISA) and General Safety Regulation 2 (GSR2) compliance. Furthermore, HD maps are instrumental in defining Operating Design Domains (ODDs) for automated driving activation. Without precise geofencing and road characteristic data, validating the safety perimeter of an autonomous system is nearly impossible. These regulatory pressures are converting HD mapping from an optional enhancement into a compliance requirement, thereby locking in demand across the industry.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a moderately concentrated landscape where key players hold significant influence. Our analysis indicates that the top three companies command a notable share of the market, while the top five consolidate further influence. This concentration suggests high barriers to entry, largely due to the capital intensity and technical expertise required to maintain global mapping coverage.
Three companies stand out as pivotal actors in this ecosystem, each pursuing distinct strategies to capture value.
- HERE Technologies, headquartered in Eindhoven, Netherlands, remains a dominant force with its HERE HD Live Map. They specialize in providing high-precision, real-time map tiles and layers tailored for ADAS and automated driving across both passenger and commercial vehicles. Their recent activity at CES 2026 highlighted a shift toward an AI-powered portfolio for software-defined vehicles, integrating advanced software for navigation and autonomy. This move signals a strategic pivot from static data provision to dynamic, AI-enhanced ecosystem services.
- Dynamic Map Platform (DMP), based in Livonia, Michigan, USA, competes on the basis of absolute accuracy. They provide automotive HD maps with accuracy under 15 cm RMSE, covering extensive mileage in North America and global 3D-mapped roads. Their focus includes software for e-Horizon and ODD support. Recent expansions in 2025 saw them cover over 950,000 miles in North America and complete coast-to-coast Canadian HD Map coverage. This geographical thickening demonstrates a strategy of deepening market penetration in key Western regions before further global scaling.
- Mapbox, located in San Francisco, California, USA, leverages its strengths in developer-friendly platforms to offer Autopilot Map and 3D Lanes navigation features. Their approach emphasizes precision data for in-car HD map capabilities supporting automated driving systems. Recent partnerships, including a notable collaboration with BMW Group for 3D Lanes and powering the next-generation navigation system in the Toyota RAV4, illustrate their strategy of embedding HD map technology directly into consumer vehicle ecosystems through OEM partnerships.
The competitive dynamics are not merely about coverage area but about the sophistication of the data layers and the integration ease for OEMs. The full report provides a deeper comparative analysis of these players, examining their technological moats and partnership networks in greater detail.
Segmentation and Operational Complexities
Understanding the market requires dissecting how value is delivered across different delivery models and use cases. The market is broadly segmented by delivery type and application focus.
Delivery Models: Cloud vs. Embedded
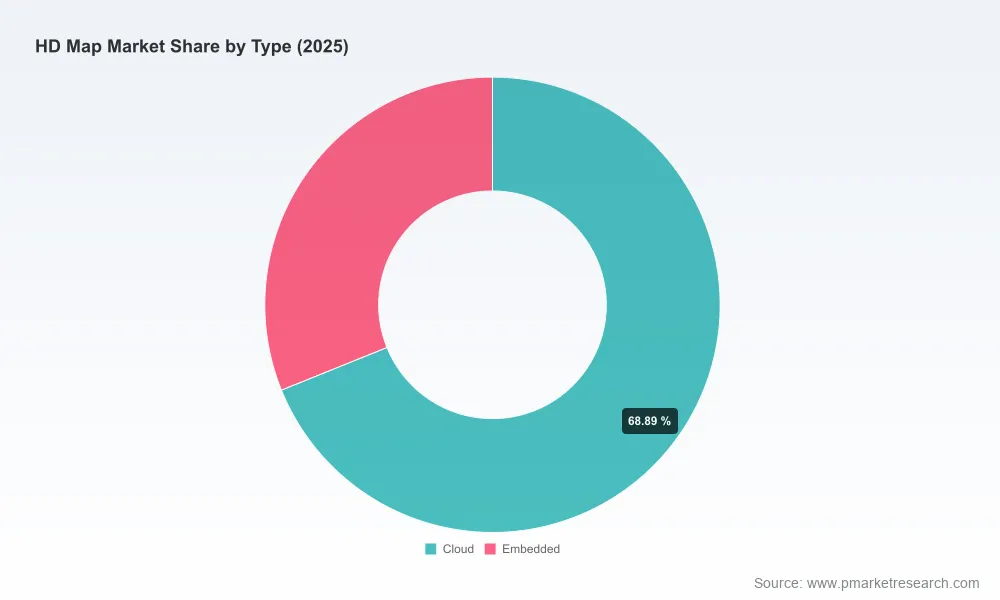
The bifurcation between Cloud-based and Embedded solutions represents a critical strategic fork. Cloud solutions offer flexibility and updateability, allowing vehicles to receive fresh map data without hardware constraints. Embedded solutions, however, provide latency advantages and offline reliability, which are crucial for safety-critical functions where connectivity cannot be guaranteed. The balance between these two models is shifting as edge computing capabilities within vehicles improve. Our research delves into the revenue split between these types to identify where the margin pools are migrating.
Application Focus
Autonomous Driving remains the primary value driver within the application segment. The requirement for reliable localization and path planning in self-driving scenarios consumes the majority of high-value map data demand. However, other applications such as advanced navigation and driver assistance are growing sub-segments that contribute to overall market health. The interplay between these applications dictates the type of data required—whether it is static lane geometry or dynamic traffic flow information.
Operational Barriers and Cost Structures
While the revenue potential is high, the cost structure of HD map creation presents significant hurdles. Producing these maps requires extensive personnel for manual labeling or high-performance computing equipment for running machine learning algorithms. This labor and compute intensity creates a high fixed-cost base for providers.
Furthermore, the physical infrastructure required for data collection is specialized. Production relies on professional data collection via Mobile Mapping System (MMS) vehicles equipped with high-end sensors including LiDAR, cameras, and GNSS-RTK. This equipment is often specialized imported equipment from North America and Europe, which can limit local adoption in other regions due to supply chain constraints and capital expenditure requirements. These operational realities create natural barriers to entry and influence the geographic distribution of service providers.
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in this space, the implications of the current market trajectory are clear. The convergence of regulatory pressure, technological capability, and market growth creates a narrow window for strategic positioning.
HD Map Market
Worldwide Hd Broadcasting Car Market
First, the reliance on imported equipment and specialized labor suggests that vertical integration or strong supply chain partnerships are necessary to maintain margin integrity. Companies cannot afford to treat data collection as a commodity service; it is a proprietary asset class.
Second, the recent product launches and expansions by key players indicate that the technology is maturing rapidly. The integration of AI-powered live maps and 3D lane features suggests that the next generation of vehicles will require data that is not only geometrically accurate but also semantically rich and dynamically updated. Firms that fail to update their data pipelines risk obsolescence.
Third, the concentration of market power among top players means that new entrants must find niche differentiation or target underserved geographies. The existing coverage in North America and Europe is deep, but global consistency remains a challenge. Opportunities may exist in regions where mapping density is lower, though the infrastructure costs must be weighed against potential revenue.
Conclusion: The Value of Deep Intelligence
The HD Map Market is at an inflection point where theoretical potential is converting into realized revenue. The growth rates observed from 2020 to 2032 suggest a sector that is fundamental to the future of mobility. However, navigating this market requires more than general trends. It requires detailed segmentation data, precise competitive benchmarking, and an understanding of the specific cost dynamics involved in map creation and maintenance.
This insight has outlined the strategic contours of the landscape, highlighting the major players, the regulatory drivers, and the operational challenges. Yet, the specific breakdown of regional revenue shares, detailed application splits, and exact market concentration metrics are critical for building a robust business case. These details are contained within our full market research report.
To make informed decisions for 2026 and beyond, stakeholders need access to the comprehensive dataset that underpins these observations. We invite you to access the complete study to retrieve the full intelligence required to navigate this high-precision market successfully. The macro view is essential, but the micro-data is where the competitive advantage lies.
For detailed analysis of this topic, please visit the official page: HD Map Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com























Sign in to leave a comment.