
Navigating the Emissions Compliance Horizon: Strategic Intelligence for the In-Situ CEMS Market
Executive Summary: The Imperative for Real-Time Data
In the rapidly evolving landscape of industrial environmental compliance, the ability to monitor emissions in real-time is no longer a luxury reserved for the most advanced facilities—it is a regulatory necessity and a strategic asset. As global standards tighten and the pressure to decarbonize intensifies, In-Situ Continuous Emissions Monitoring Systems (CEMS) have emerged as a critical technology for ensuring accuracy, reducing maintenance overhead, and facilitating immediate corrective actions. This article serves as a strategic overview of the current market trajectory and introduces the comprehensive intelligence contained within our latest market research study, designed to empower decision-makers through 2032.
The transition from extractive to in-situ monitoring represents a paradigm shift in how industries manage their environmental footprint. By analyzing the gas stream directly within the stack or duct, facilities can achieve faster response times and lower maintenance requirements compared to traditional extractive systems. This shift is driven by a convergence of stricter regulatory frameworks, technological advancements in laser and infrared spectroscopy, and a growing corporate commitment to transparency in emissions reporting. Understanding the nuances of this market is essential for stakeholders looking to capitalize on emerging opportunities or secure their operational compliance in a tightening regulatory environment.
Market Trajectory and Growth Dynamics
The financial scale of the In-Situ CEMS market underscores its significance within the broader industrial instrumentation sector. Based on historical data tracing back to 2020, the market has demonstrated consistent resilience and expansion. Starting from a baseline of approximately 785.45 million USD in 2020, the industry has navigated various economic and regulatory cycles to reach an estimated 1248.2 million USD in 2025. This growth trajectory is not merely a recovery from past fluctuations but indicates a structural demand increase driven by industrial modernization and compliance mandates.
Looking toward the forecast period extending through 2032, the outlook remains robust. The market is projected to reach 1336.36 million USD in 2026, accelerating towards a final valuation of 2394.7 million USD by the end of the forecast horizon. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 9.85 percent. Such a growth rate signals strong investor confidence and sustained capital expenditure from industrial end-users who prioritize long-term compliance stability over short-term cost savings. For strategic planners, this suggests that the sector offers viable opportunities for partnership, investment, and technology deployment well into the next decade.
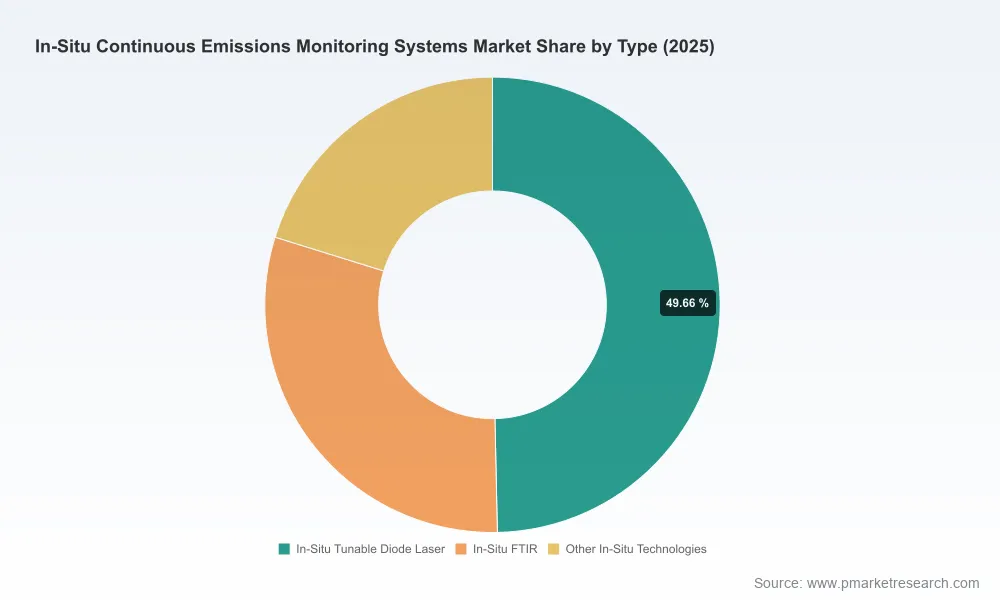
The demand is distributed across a diverse range of applications and technologies, reflecting the versatility of in-situ solutions. Industries such as Power Generation, Oil and Gas, and Chemicals and Petrochemicals remain significant contributors to the revenue pool, alongside growing adoption in Cement and Metals and Mining sectors. Similarly, technology preferences are split between established methods like In-Situ Tunable Diode Laser and In-Situ FTIR, alongside other emerging in-situ technologies. This diversification mitigates risk for technology providers and offers multiple pathways for integration depending on specific process conditions and gas compositions.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of specialized sensor manufacturers and large-scale industrial conglomerates. While the market shows a degree of concentration, with the top five players holding a significant share of the revenue, there remains ample space for innovation and niche specialization. The competitive environment is dynamic, with key players constantly evolving their product portfolios to meet rigorous certification standards and performance requirements.
Leading entities such as SICK AG and ABB Ltd continue to reinforce their positions through sustained investment in sensor technologies and cross-duct analyzer solutions. SICK AG, for instance, has recently reported increased sales and continued R&D investment in sensor solutions, highlighting a commitment to expanding their footprint in industrial emissions monitoring. Their product lines, including the GM32 and LS4000 series, are pivotal for real-time raw gas analysis. Similarly, ABB Ltd has been enhancing hybrid CEMS platforms with in-situ capabilities integrated with AI analytics, signaling a trend toward smarter, data-driven monitoring solutions that go beyond simple compliance to offer operational optimization.
Specialized firms like Protea Ltd and CODEL International Ltd play crucial roles in certifying and deploying specific analyzer technologies. Protea Ltd recently achieved NPLI CS Certification for their P2000 in-situ analyzer, a development that verifies compliance for emissions monitoring applications and strengthens their credibility in the UK and European markets. CODEL International focuses on the GCEM40 series, emphasizing low-maintenance multi-gas monitoring, which addresses a key pain point for facility managers regarding lifecycle costs.
In-Situ Continuous Emissions Monitoring Systems Market
On the broader industrial side, giants like Siemens AG and AMETEK Inc. provide in-situ gas analyzers as part of comprehensive CEMS solutions, often integrating these systems into larger automation and process control architectures. Teledyne Monitor Labs and Horiba Ltd also contribute significant expertise, offering hybrid and multi-component gas analysis solutions that cater to complex monitoring needs. The presence of these varied players ensures a competitive marketplace where pricing, performance, and support services are constantly benchmarked against one another.
Regulatory Catalysts and Industry Dynamics
Regulatory pressure remains the primary engine driving adoption rates for in-situ CEMS. In the United States, the U.S. EPA finalized updates in May 2024 to New Source Performance Standards for Electric Generating Units (EGUs), requiring PM CEMS compliance timelines of three years, with possible one-year extensions for MATS facilities. Such mandates create a definitive countdown for industrial operators to upgrade or install monitoring infrastructure, directly influencing procurement cycles and market demand.
Across the Atlantic, the EU Industrial Emissions Directive (IED) and national frameworks mandate continuous monitoring of air pollutants across key industrial sectors. These regulations support in-situ CEMS adoption by setting rigorous performance benchmarks that in-situ technologies are increasingly capable of meeting. Furthermore, in-situ CEMS techniques are certified under standards including EN 15267-3 MCERTS, EN 14181 QAL 1, and US EPA 40 CFR Part 60 and 75. Compliance with these standards is not optional; it is a prerequisite for market entry and operational legitimacy. Vendors who can navigate these certification landscapes effectively hold a distinct competitive advantage.
Continuous Emission Monitoring Systems (CEMS) Market
From an operational perspective, the advantages of in-situ systems over extractive counterparts are becoming increasingly apparent to facility engineers. These systems offer lower maintenance requirements and faster response times, making them ideal for space-constrained and dynamic industrial environments. As industries seek to minimize downtime and reduce the consumable costs associated with extractive sampling (such as pumps, filters, and reagents), the value proposition of in-situ technology strengthens. This operational efficiency complements the regulatory drivers, creating a dual incentive for adoption.
The Strategic Value of Comprehensive Market Intelligence
For executives, procurement officers, and investors, navigating this complex landscape requires more than just high-level growth figures. It demands a granular understanding of segmentation, competitive moves, and regulatory timelines. Our latest market research report provides a deep dive into these areas, offering the granularity needed to formulate robust strategies. The report details the specific revenue contributions of different regions and application segments, allowing stakeholders to identify high-growth pockets without exposing them to the risks of generalized market assumptions.
Beyond market sizing, the study analyzes the technological readiness and certification status of key products, helping buyers assess vendor reliability. It also tracks recent developments, such as certification updates and deployment enhancements, ensuring that strategic plans are based on the most current information available. Understanding the concentration of market power among top players helps in negotiating procurement contracts and assessing supply chain risks. Furthermore, the report contextualizes these business metrics against the backdrop of evolving environmental laws, ensuring that compliance strategies are future-proofed against upcoming regulatory changes.
The insights contained within this research are designed to support decision-making across multiple functions. For product managers, it highlights technology trends and gaps. For strategists, it maps the competitive terrain and identifies potential partnership opportunities. For financial analysts, it provides the revenue forecasts and market concentration data necessary to evaluate investment potential. By synthesizing historical data, current dynamics, and future projections, the report acts as a single source of truth for anyone involved in the In-Situ CEMS value chain.
Conclusion: Preparing for 2032 and Beyond
The In-Situ Continuous Emissions Monitoring Systems market is at an inflection point. With a projected valuation nearing 2.4 billion USD by 2032 and a steady CAGR of 9.85 percent, the sector is poised for significant transformation. The convergence of regulatory mandates, technological innovation, and operational efficiency demands creates a fertile ground for growth, but also raises the stakes for competitiveness. Companies that fail to adapt to these monitoring standards risk regulatory penalties and operational inefficiencies, while those that invest wisely can turn compliance into a competitive differentiator.
However, the specifics of where to invest, which technologies will dominate specific segments, and how regional regulations will shift require detailed analysis that goes beyond general market trends. The full scope of opportunity lies in the data granularity that only a dedicated market study can provide. To access the complete segmentation data, detailed company profiles, and comprehensive regulatory impact analysis, stakeholders are encouraged to explore the full report available on our portal. Equip your organization with the precise intelligence needed to navigate the emissions compliance landscape of the next decade.
For detailed analysis of this topic, please visit the official page: In-Situ Continuous Emissions Monitoring Systems Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com





















Sign in to leave a comment.