

Strategic Horizons in the Process Gas Compressor Market: A 2026 Decision Framework
Executive Summary: Navigating Growth Amid Regulatory Shifts
The process gas compressor market stands at a pivotal inflection point. As industrial operations confront tightening emissions mandates, supply chain recalibrations, and the accelerating deployment of decarbonization technologies, capital allocation decisions made in 2026 will define competitive positioning through the end of the decade. This market intelligence report provides a structured, data-rich assessment of the global process gas compressor landscape, translating historical performance and forward-looking projections into actionable strategic guidance for procurement leaders, engineering executives, and investment committees.
Drawing on a comprehensive historical baseline spanning 2020 through 2025 and a forecast horizon extending to 2032, the analysis captures both the resilience and the structural transformation underway in this specialized capital equipment sector. The global market, denominated in USD billions, has demonstrated steady upward momentum over the past half-decade, advancing from an estimated 5.97 billion in 2020 to 7.8 billion in 2025. Forward projections indicate continued expansion, with the market anticipated to reach 11.35 billion by 2032, reflecting a compound annual growth rate of 5.5 percent across the 2026 to 2032 forecast period. These aggregate trajectories establish the macro context within which segment-level dynamics, regional demand patterns, and competitive pressures must be evaluated.
This report does not merely restate growth figures. It dissects the operational, regulatory, and technological forces shaping procurement strategies, capacity planning, and vendor selection. By grounding quantitative projections in qualitative market reality, the analysis equips decision-makers with the analytical rigor required to navigate a market where performance specifications, compliance requirements, and total cost of ownership considerations increasingly converge.
Gas Compressors Market
Compressor Architecture and Application Landscape: The Performance-Compliance Nexus
Process gas compressors serve as critical enablers across a spectrum of industrial processes, where reliability, efficiency, and emissions performance directly influence operational continuity and regulatory standing. The market is delineated across multiple architectural types, each carrying distinct performance profiles, maintenance footprints, and suitability for specific operating regimes. Centrifugal designs, particularly integrally geared configurations, dominate applications demanding high throughput and oil-free delivery. Reciprocating compressors remain foundational in high-pressure and multi-service environments, while screw and rotary variants address niche throughput and compactness requirements. The analysis maps each architectural category against evolving performance benchmarks, service intervals, and lifecycle cost parameters, enabling buyers to align equipment selection with process-specific constraints rather than defaulting to legacy specifications.
Application-side demand is distributed across several core industrial verticals, with oil & gas operations representing the largest consumption pool, followed by chemical and petrochemical processing, industrial gas production, and power generation. Each vertical imposes distinct compression requirements, ranging from high-pressure hydrogen handling and boil-off gas management to midstream transmission and supercritical working-fluid injection. The report examines how application-specific operating conditions interact with emerging regulatory pressures, particularly around fugitive emission control and energy efficiency. Operators facing compliance deadlines are increasingly evaluating compressor platforms not solely on initial capital expenditure but on their capacity to reduce leakage, minimize maintenance-driven downtime, and integrate with emissions monitoring infrastructure.
Segment-level performance is further shaped by raw material availability and component supply dynamics. High-grade steels, engineered rotating parts, and precision sealing systems remain essential to manufacturing compressors that meet API standards and withstand aggressive process conditions. Ongoing supply chain constraints and price volatility in critical inputs have introduced procurement lead-time variability and cost-structure uncertainty. The report quantifies these pressures within the broader cost framework, offering scenario-based guidance for procurement teams balancing specification integrity against supply reliability.
Process Gas Compressor Market
Regulatory Acceleration and Technological Response
Regulatory intensity is reshaping the process gas compressor market at an accelerating pace. Government mandates targeting fugitive emission reduction, coupled with tightening EPA directives and the EU Industrial Emissions Directive, are incentivizing operators to prioritize oil-free and hermetically sealed compressor solutions. Methane emission reduction requirements under the U.S. EPA Methane Rule and the EU Methane Regulation are prompting operators to replace older, high-emission reciprocating units with cleaner, more efficient alternatives. These regulatory shifts are not isolated compliance events; they are structural drivers that influence equipment specification, retrofit timing, and capital replacement cycles.
Simultaneously, emissions control and energy efficiency mandates are exerting direct pressure on operating economics. Compressors that deliver lower leakage rates, reduced vibration and pulsation profiles, and improved thermodynamic efficiency are gaining preference in applications where continuous operation and emissions compliance are jointly mandated. The analysis examines how these regulatory dynamics intersect with total cost of ownership calculations, enabling organizations to evaluate whether retrofit investments, early replacement programs, or specification upgrades yield measurable compliance and efficiency gains over the equipment lifecycle.
Technological innovation is responding to these pressures with measurable momentum. Leading manufacturers are advancing integrally geared centrifugal platforms, API-compliant reciprocating designs, and high-pressure turbo-type compressors engineered for demanding decarbonization applications. Recent demonstration activity underscores this trajectory: in February 2026, IHI Corporation and IHI Rotating Machinery Engineering Co., Ltd. successfully completed a demonstration test of a new CO2 working-fluid process gas compressor achieving 20 MPaG discharge pressure using a geared, multi-shaft, multi-stage turbo-type configuration for supercritical CO2 injection into deep saline aquifers. This milestone advances the commercial viability of carbon capture, utilization, and storage deployment and illustrates how compressor technology is expanding beyond traditional industrial gas handling into next-generation decarbonization infrastructure.
Competitive Landscape: Differentiation Through Engineering Precision
The competitive structure of the process gas compressor market reflects a concentrated yet specialized vendor base, where engineering heritage, application-specific capability, and compliance performance distinguish leading participants. Market concentration indicators suggest that the top three vendors account for approximately 24.6 percent of aggregate market share, while the top five reach roughly 26.2 percent, indicating a landscape where niche leadership and application expertise matter as much as scale. The report profiles the strategic positioning of core market participants, examining how product architecture, sealing technology, and service ecosystems shape competitive differentiation.
Sundyne, headquartered in Arvada, Colorado, specializes in integrally geared centrifugal process gas compressors designed for midstream, downstream, and power generation applications. Its platform emphasis on pulsation- and vibration-free operation, oil-free process gas delivery, and zero-emission performance aligns directly with operator priorities around compliance, equipment longevity, and process integrity. The analysis evaluates how Sundyne's centrifugal focus positions it within high-throughput, oil-free demand segments and how its engineering approach maps to replacement cycles driven by emissions mandates.
Burckhardt Compression, based in Winterthur, Switzerland, manufactures horizontal and vertical reciprocating process gas compressors compliant with API 618 standards. Its portfolio targets refinery gas compression, boil-off gas management, hydrogen compression, and petrochemical applications, supported by advanced sealing technology designed to reduce leakage and enhance reliability. The report examines Burckhardt's reciprocating strength in high-pressure, multi-service environments and assesses how its sealing and compliance capabilities intersect with operator replacement decisions influenced by methane and fugitive emission regulations.
IHI Corporation, headquartered in Tokyo, Japan, develops and manufactures turbo-type process gas compressors, including geared multi-stage models engineered for high-pressure applications in carbon capture, utilization, and storage, LNG terminals, and air separation units. IHI's recent demonstration of a high-discharge-pressure CO2 compressor highlights its trajectory into supercritical working-fluid applications and positions it at the intersection of compressor engineering and decarbonization infrastructure. The analysis explores how IHI's turbo-type capabilities and high-pressure engineering expertise create differentiation in emerging CCUS and LNG-related demand pools.
Beyond these core participants, the competitive landscape includes a broader set of regional and application-focused suppliers. The report maps vendor positioning across type and application segments, identifying where scale advantages, technology specialization, and service network depth create durable competitive advantages, and where pricing pressure, specification convergence, or supply chain constraints compress margins.
Regional Demand Patterns and Capacity Deployment Priorities
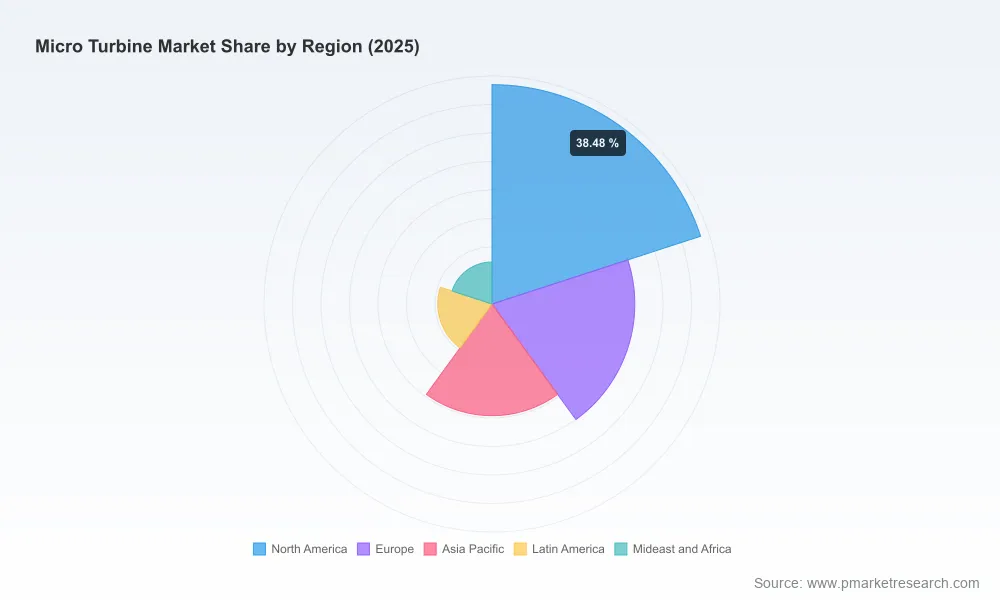
Geographic demand distribution reflects the intersection of industrial activity, regulatory intensity, and capital investment cycles. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct compression demand profiles shaped by local energy infrastructure, petrochemical expansion, power generation needs, and industrial gas consumption. The analysis examines regional demand drivers without reducing them to static share percentages, instead emphasizing how regulatory timelines, project pipelines, and supply chain localization strategies influence procurement pacing and vendor selection in each geography.
In markets where emissions mandates are advancing rapidly, replacement and upgrade activity is accelerating, creating demand for low-emission, oil-free, and hermetic solutions. In regions with expanding midstream and petrochemical capacity, throughput-driven centrifugal and reciprocating demand remains prominent. In industrial gas and power generation contexts, reliability, efficiency, and service availability weigh heavily in procurement decisions. The report connects these regional dynamics to vendor strategy, highlighting where localized service capability, lead-time predictability, and compliance-aligned specification support become decisive competitive factors.
Report Architecture: What Decision-Makers Will Find Inside
This market research is structured to translate complex sector dynamics into operational decision support. The report integrates quantitative market sizing, segmented analysis, competitive profiling, and regulatory mapping into a cohesive framework designed for strategic planning, procurement optimization, and investment evaluation. Key components include:
- Historical market performance tracing from 2020 through 2025, establishing baseline growth patterns and cyclical behavior across architectural types, application verticals, and regional markets.
- Forward-looking projections through 2032, anchored to a 5.5 percent compound annual growth rate, with scenario-aware commentary on how regulatory acceleration, supply chain conditions, and technology adoption may influence trajectory.
- Segment-level analysis across compressor types and end-use applications, mapping performance characteristics, compliance alignment, and replacement-cycle implications without exposing granular share internals that are reserved for full-report subscribers.
- Competitive profiling of core market participants, including product architecture emphasis, application fit, sealing and emissions performance, and recent development activity that signals strategic direction.
- Regulatory and supply chain context, detailing how emissions mandates, energy efficiency requirements, and raw material constraints interact with procurement timing, specification choices, and total cost of ownership.
- Decision-support frameworks that connect market data to capital planning, vendor evaluation, and retrofit-versus-replacement trade-offs under varying compliance and operational scenarios.
The report is designed for use by engineering leaders, procurement and supply chain executives, asset managers, and strategy teams who require a balanced view of market growth, competitive positioning, and regulatory risk. By integrating macro trajectory with segment-level dynamics and vendor-specific capability mapping, the analysis supports decisions that are both commercially disciplined and compliance-aware.
Strategic Takeaways for 2026 Planning
Several conclusions emerge clearly for organizations planning capital deployment, procurement strategy, and technology roadmapping in 2026. First, regulatory momentum around fugitive emissions and methane reduction is no longer a peripheral compliance issue; it is a primary driver of equipment specification, replacement timing, and vendor evaluation. Second, the growing preference for oil-free, hermetic, and low-vibration compressor platforms reflects a broader shift toward performance characteristics that reduce leakage, improve continuity, and align with emissions reporting requirements. Third, supply chain variability in high-grade materials and critical components introduces procurement risk that must be managed through lead-time planning, specification flexibility, and supplier diversification. Fourth, emerging decarbonization applications, including supercritical CO2 injection and CCUS infrastructure, are expanding the functional scope of process gas compressors and creating demand for high-pressure, multi-stage turbo-type solutions.
For decision-makers, the strategic implication is clear: the process gas compressor market is becoming more specification-sensitive, more compliance-driven, and more technology-diverse. Evaluating vendors on compliance performance, sealing integrity, vibration and pulsation control, and service responsiveness is increasingly as important as evaluating upfront capital cost. Aligning replacement cycles with regulatory timelines and emissions targets can reduce operational risk while improving long-term efficiency. And positioning procurement strategy to account for material availability and lead-time variability can protect project schedules and specification consistency.
Accessing the Full Intelligence Suite
This overview establishes the strategic context and analytical rigor underpinning the full Process Gas Compressor Market research. While the discussion above outlines market trajectory, regulatory drivers, competitive differentiation, and decision-support structure, the complete report provides the granular segmentation data, regional breakdowns, application-level performance mapping, and vendor share analysis required for detailed capital planning and procurement execution. Readers seeking the full quantitative architecture, scenario commentary, and vendor evaluation matrices are encouraged to access the source report to obtain the complete intelligence suite.
In a market where regulatory timelines, supply chain conditions, and technology evolution are reshaping procurement and investment decisions, precision intelligence is a strategic asset. This research is designed to provide that asset—grounded in historical performance, oriented toward 2026 planning realities, and structured to support decisions that balance compliance, efficiency, and commercial discipline through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Process Gas Compressor Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com
























Sign in to leave a comment.