
Navigating the Osteoarthritis Pain Market: Strategic Intelligence for 2026 Decision-Making
The Imperative for Precision Intelligence in Pain Management
Osteoarthritis remains one of the most pervasive chronic conditions globally, driving sustained demand for effective pain management solutions. As the healthcare landscape evolves through 2026 and beyond, pharmaceutical companies, investors, and strategic stakeholders require more than surface-level figures to navigate this complex therapeutic area. The market for drugs targeting osteoarthritis pain has demonstrated resilient growth over the past half-decade, reflecting both demographic shifts and advancing clinical paradigms. Understanding where capital should be deployed, which therapeutic categories are gaining traction, and how regulatory and reimbursement dynamics are reshaping competitive positioning demands a structured, data-rich analytical framework.
This market research publication serves as a comprehensive strategic compass for executives seeking to align product portfolios, investment theses, and market-entry strategies with the realities of a rapidly maturing landscape. By examining historical trajectories, forward-looking growth vectors, and the operational realities of key market participants, the report equips decision-makers with actionable clarity. Rather than offering generic industry commentary, it delivers granular, segmented intelligence designed to stress-test assumptions and uncover high-probability opportunities in the years ahead.
Macroeconomic Trajectory and Long-Term Growth Outlook
The market has followed a clear upward trajectory from 2020 through the base year of 2025, expanding from approximately 7.85 billion USD to over 11.15 billion USD. This historical expansion underscores the consistent clinical need for osteoarthritis pain interventions and the sustained commercial viability of established therapeutic modalities. Looking ahead, the forecast period from 2026 to 2032 projects continued, disciplined growth, with the market expected to surpass 16.5 billion USD by the terminal forecast year. The compound annual growth rate of 5.85 percent reflects a balanced expansion profile, neither overly speculative nor stagnating, indicating steady adoption curves, pipeline maturation, and incremental clinical uptake across multiple therapeutic classes.
Drugs for Osteoarthritis Pain Market
For strategic planners, this growth cadence carries several implications. First, it confirms that osteoarthritis pain management is not a cyclical commodity space but a therapeutic category with structural demand drivers, including aging populations, rising obesity prevalence, and shifting clinical preferences toward non-opioid interventions. Second, the moderate yet robust CAGR suggests that incremental market share gains, rather than speculative moonshot bets, will define success for most commercial players. Executives must therefore evaluate whether their product pipelines, pricing architectures, and distribution networks are optimized for sustained, compounding growth rather than short-lived surges.
Segmentation Dynamics: How Therapeutic Types and Administration Routes Shape Strategy
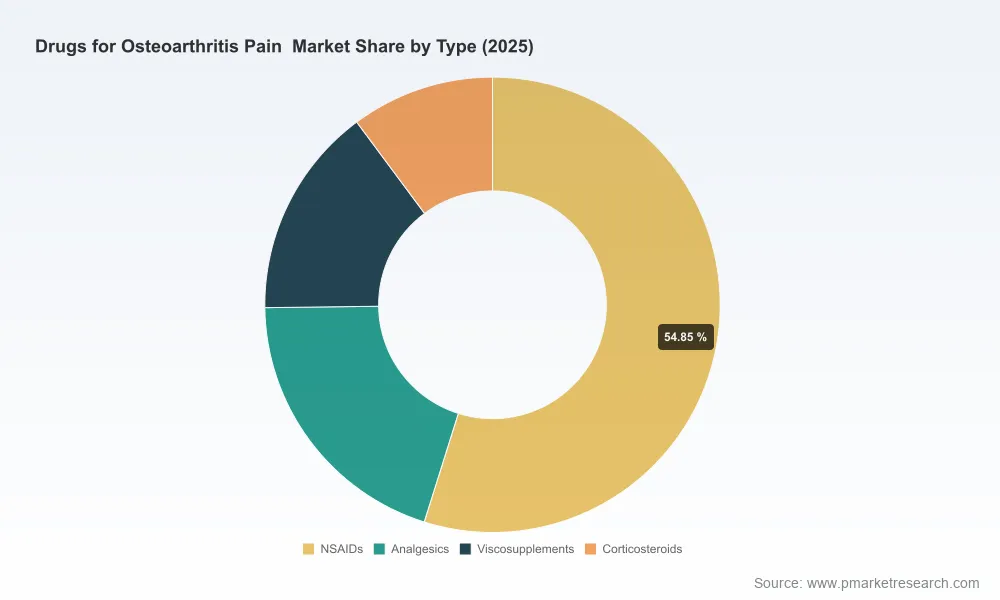
A disciplined analysis of the market requires a clear understanding of how therapeutic categories and delivery modalities distribute demand and influence commercial execution. The research dissects the market across multiple dimensions, revealing which therapeutic classes anchor volume and which administration routes align with evolving clinical preferences. Non-steroidal anti-inflammatory drugs continue to represent the most substantial share of therapeutic utilization, reflecting their established efficacy profiles, broad clinical familiarity, and extensive formulary inclusion. Alongside them, analgesics, viscosupplements, and corticosteroids each occupy distinct clinical niches, serving specific patient populations and care settings with varying reimbursement pathways and physician adoption curves.
Administration routes further complicate the commercial landscape. Oral delivery remains the dominant modality, benefiting from patient convenience, established prescribing habits, and scalable manufacturing. Parenteral interventions command a meaningful share, particularly where localized delivery or rapid onset is clinically prioritized. Topical formulations occupy a specialized but growing position, appealing to patients and providers seeking targeted symptom relief with reduced systemic exposure. Strategic planners should recognize that these segmentation layers are not merely descriptive; they determine manufacturing complexity, supply chain requirements, packaging strategies, and the pace at which new entrants can achieve commercial scale.
The report’s segmentation architecture also incorporates regional distribution patterns, providing decision-makers with a comparative view of how demand clusters across major geographic markets. Understanding these regional weightings is essential for companies calibrating export strategies, evaluating partnership opportunities, and modeling capacity utilization across manufacturing footprints. The depth of this geographic and therapeutic disaggregation allows stakeholders to map where incremental growth will likely materialize and which distribution channels will require reinforcement.
Competitive Landscape: Established Leaders and Emerging Innovation Vectors
The competitive environment is shaped by a mix of multinational pharmaceutical incumbents and specialized innovators pursuing differentiated mechanisms of action. Among the established participants, Pfizer Inc., Johnson & Johnson, GlaxoSmithKline plc, Bayer AG, Haleon plc, Eli Lilly and Company, AbbVie Inc., Merck & Co., Inc., Sanofi, and GSK plc each maintain distinct commercial footprints. Many of these organizations anchor their portfolios around well-known oral NSAIDs and analgesics, leveraging decades of clinical data, robust manufacturing infrastructure, and extensive physician relationships. Others have carved out specialized positions, such as acetaminophen-focused offerings or duloxetine-based pain management pathways, reflecting strategic diversification within the broader pain category.
Beyond these incumbent positions, the competitive narrative is increasingly influenced by regulatory designations and novel mechanism exploration. In August 2024, the FDA granted fast track designation to MM-II, a non-opioid liposomal product developed by Sun Pharma and Moebius Medical Limited for knee osteoarthritis pain. Shortly thereafter, in September 2024, Genascence Corporation received fast track designation for GNSC-001, a gene therapy approach targeting knee osteoarthritis pain. These developments signal a widening innovation frontier, where localized delivery systems and genetic modulation strategies are moving closer to formal regulatory evaluation. More recently, in January 2025, Levicept announced FDA acceptance of an IND application for LEVI-04, a neurotrophin inhibitor designed for osteoarthritis knee pain. Collectively, these milestones illustrate how pipeline diversity is expanding the strategic horizon for both investors and commercial teams evaluating long-term portfolio resilience.
Pain Management Drugs Market
Regulatory, Reimbursement, and Clinical Endpoint Dynamics
Regulatory clarity and reimbursement architecture increasingly dictate commercial viability in osteoarthritis pain management. In August 2024, the Centers for Medicare & Medicaid Services issued clinical endpoints guidance for knee osteoarthritis outcomes, incorporating pain subscales into regulatory review considerations. This guidance reinforces the importance of rigorous, standardized outcome measurement, particularly the WOMAC pain subscale, which the FDA validated in 2024 for assessing knee osteoarthritis interventions. For product developers, these endpoint expectations raise the bar for clinical trial design and shape the evidentiary thresholds required for market access and payer acceptance.
On the labeling and formulation front, the FDA approved updated labeling in 2024 for diclofenac products, including Zorvolex and Pennsaid, confirming efficacy in osteoarthritis pain management. Such regulatory affirmations help stabilize confidence in established therapeutic options while providing clarity for prescribers navigating treatment pathways. At the same time, reimbursement dynamics continue to influence real-world utilization. Manufacturer copay assistance programs for certain intra-articular corticosteroids illustrate how patient affordability mechanisms can shape adoption patterns, particularly for interventions that may otherwise face utilization friction due to cost-sharing structures.
Supply-side considerations also intersect with these dynamics. High molecular weight hyaluronate sourced from rooster combs remains a foundational input for approved viscosupplements used in knee osteoarthritis pain relief. This reliance on specific raw material sources highlights the importance of supply chain resilience, quality control, and continuity planning for manufacturers operating in injectable or biologic-adjacent segments. Strategic stakeholders must therefore evaluate not only clinical differentiation but also the operational feasibility of maintaining consistent product availability in regulated markets.
Report Scope: What Decision-Makers Will Find Inside
This market research publication is structured to support a wide range of strategic use cases, from portfolio prioritization and investment committee briefings to competitive benchmarking and market-entry evaluation. Rather than stopping at headline figures, the report integrates historical performance data, forward-looking forecasts, and a layered segmentation framework that maps therapeutic types, administration routes, and regional demand distributions. It also consolidates profiles of key market participants, recent regulatory and pipeline developments, and the operational context that surrounds raw material sourcing, reimbursement mechanisms, and clinical endpoint expectations.
The report’s methodology is designed for practical application. Executives can use it to benchmark internal growth assumptions, assess whether particular therapeutic categories are expanding or contracting relative to market averages, and identify which geographic or segment-level opportunities merit deeper due diligence. For commercial teams, the segmentation detail supports channel strategy, territory planning, and demand forecasting. For investment professionals, the combination of market sizing, competitive profiling, and recent regulatory milestones provides a structured basis for evaluating relative positioning and future value creation potential.
Strategic Implications for 2026 and Beyond
As organizations plan for the 2026 decision window, several strategic themes emerge from the market structure. First, sustained growth at a disciplined CAGR suggests that portfolio resilience will increasingly depend on disciplined segmentation rather than undifferentiated expansion. Companies that understand how oral, parenteral, and topical modalities interact with payer behavior, patient adherence, and physician preferences will be better positioned to allocate commercial resources efficiently.
Second, the presence of both large incumbent portfolios and emerging pipeline candidates with alternative mechanisms of action creates a dynamic competitive field. Fast track designations, IND acceptances, and updated labeling approvals are not isolated events; they signal shifting expectations around non-opioid options, localized delivery, and targeted modulation of pain pathways. Strategic planners should assess how these developments may influence formulary positioning, clinical prescribing inertia, and long-term competitive pressure across established categories.
Third, regulatory and reimbursement frameworks are moving toward greater standardization around clinically meaningful endpoints and outcome measurement. Organizations that invest early in robust evidence generation, real-world data collection, and patient affordability strategies will find it easier to navigate access hurdles and secure sustainable utilization patterns. At the same time, supply chain considerations for specialized inputs underscore the need for operational planning that extends beyond clinical differentiation alone.
Conclusion: Turning Market Intelligence into Actionable Advantage
The osteoarthritis pain market is not defined by a single product class or a narrow geographic opportunity. It is a multi-segment, multi-mechanism therapeutic landscape where historical demand, pipeline innovation, regulatory evolution, and reimbursement realities intersect. For executives operating in 2026, the difference between reactive positioning and proactive strategy lies in the quality of the intelligence guiding those choices.
This research publication offers a structured, data-rich foundation for that decision-making process. By combining comprehensive market sizing, segmentation analysis, competitor profiling, and regulatory context, it enables stakeholders to evaluate growth assumptions with greater confidence and identify where strategic investment will generate the strongest returns. The macro trajectory, segmentation dynamics, and competitive developments outlined here only begin to illuminate the full complexity of the landscape. For organizations ready to move from high-level awareness to detailed, actionable intelligence, the complete report provides the depth required to inform pricing, portfolio construction, market-entry timing, and long-term competitive planning.
For detailed analysis of this topic, please visit the official page: Drugs for Osteoarthritis Pain Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com




















Sign in to leave a comment.