
Navigating the New Audit Landscape: Strategic Imperatives for 2026 and Beyond
The worldwide auditing services market stands at a critical inflection point. As organizations confront a complex matrix of regulatory tightening, sustainability mandates, and rapid technological transformation, the role of auditing has evolved from a compliance exercise into a strategic enabler of trust, resilience, and operational transparency. Understanding the trajectory of this market is no longer a discretionary exercise for finance leaders and board members, it is a fundamental prerequisite for sound decision-making in 2026. Our latest Worldwide Auditing Services Market research provides a comprehensive, data-driven foundation for navigating this shifting terrain. The study maps historical momentum, forecasts near- and mid-term expansion, and unpacks the structural forces that will define competitive positioning over the forecast horizon. For executives responsible for capital allocation, risk oversight, and service procurement, this intelligence offers a clear lens through which to evaluate vendor selection, investment in internal audit capabilities, and alignment with emerging assurance standards. The following insights preview the strategic architecture of the full report, demonstrating why disciplined market intelligence is essential for enterprise decision-makers operating in an environment where audit quality directly correlates with stakeholder confidence and regulatory survival.
Worldwide Auditing Services Market
Market Trajectory and the Architecture of Growth
The auditing services sector has demonstrated remarkable resilience and steady expansion across the historical review window. Revenue scaled from 194.2 billion USD in 2020 to 216.1 billion USD in 2021, reflecting the immediate post-pandemic recalibration of financial reporting and assurance demands. The subsequent years reinforced this upward trajectory, with the market reaching 218.39 billion USD in 2022, climbing to 245.49 billion USD in 2023, and settling at 246.92 billion USD in 2024 as organizations absorbed new regulatory expectations and addressed lingering operational vulnerabilities. By 2025, the base year for our analysis, total market revenue reached 259.85 billion USD. This foundation sets the stage for a forecast period spanning 2026 through 2032, during which the market is projected to expand at a compound annual growth rate of 6.12 percent. The forward curve points to 276.75 billion USD in 2026, followed by progressive increases to 303.68 billion USD in 2027, 323.29 billion USD in 2028, 319.57 billion USD in 2029, 346.86 billion USD in 2030, 365.36 billion USD in 2031, and a terminal projection of 393.8 billion USD in 2032. The slight moderation observed in 2029 does not signal market contraction but rather reflects a natural recalibration within a maturing industry, where service pricing, client consolidation, and shifting procurement models introduce short-term elasticity before renewed expansion resumes. For enterprise planners, this trajectory carries clear implications. The sustained 6.12 percent growth rate indicates a market that is expanding faster than general economic output, driven by structural rather than cyclical forces. Budget committees and procurement leaders must therefore treat audit and assurance expenditures not as static overhead, but as dynamic investments subject to rising demand, evolving scope, and intensifying pricing competition. Organizations that fail to anticipate these trends risk underestimating total cost of assurance, misaligning internal capabilities, and ceding negotiating leverage to providers who themselves are recalibrating their service portfolios. This report translates the macro trajectory into actionable frameworks, enabling decision-makers to model budget scenarios, evaluate capacity requirements, and identify the service components that will command premium valuation in the coming years.
Worldwide Auditing Services Market
Structural Dimensions That Will Shape Enterprise Decisions
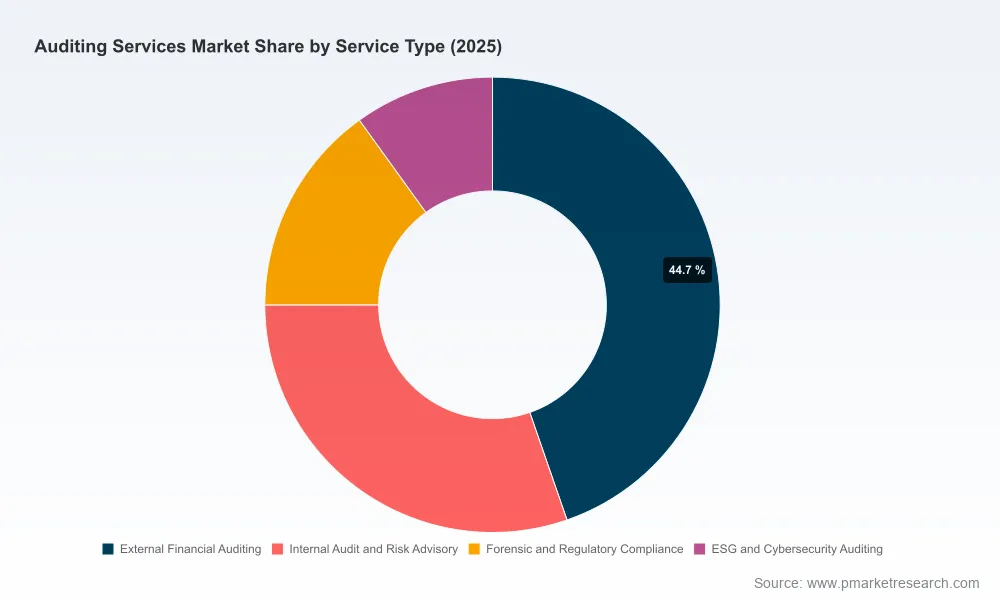
The global auditing market does not grow as a monolith. It fractures along multiple axes, each carrying distinct implications for sourcing strategy, risk posture, and capability investment. Our research decomposes the market across geographic regions, service typologies, and organizational scales, revealing where demand is concentrating and where competitive intensity is likely to escalate. The regional landscape reflects long-established demand centers alongside emerging growth corridors. North America commands a significant share of total revenue, anchored by mature regulatory frameworks, deep capital markets, and a concentration of multinational corporations with complex reporting requirements. Europe follows as a substantial contributor, shaped by evolving sustainability disclosure mandates, cross-border consolidation, and heightened scrutiny from supervisory authorities. Asia Pacific represents a dynamic expansion zone, where institutional maturation, digital financial infrastructure development, and growing mid-market sophistication are accelerating audit adoption. Latin America and the Middle East and Africa contribute meaningful but comparatively smaller revenue pools, each characterized by distinct regulatory rhythms, currency considerations, and local capacity constraints that influence service delivery models and pricing dynamics. By service type, the market organizes around four principal domains. External financial auditing remains the largest revenue component, reflecting the foundational requirement for independent assurance over financial statements across public and private entities. Internal audit and risk advisory forms a substantial second pillar, as enterprises increasingly rely on embedded assurance functions to evaluate controls, governance frameworks, and operational resilience. Forensic and regulatory compliance services capture growing demand from investigations, fraud prevention, and heightened enforcement environments. ESG and cybersecurity auditing, while the smallest segment by current revenue, is the fastest-evolving frontier, driven by mandatory sustainability reporting, data protection expectations, and board-level scrutiny of non-financial risk. By organization size, large enterprises account for the majority of market revenue, reflecting their complex reporting obligations, international operations, and higher audit fees driven by scale and scope. Small and medium enterprises collectively represent a sizable and expanding portion of demand, particularly as regulatory thresholds broaden, supply chain assurance requirements cascade to smaller suppliers, and digital audit tools lower the cost of engagement for leaner organizations. These structural dimensions matter because they directly inform procurement strategy. A multinational negotiating a multi-year assurance contract must understand which service lines are experiencing demand compression or expansion, which regions are seeing provider saturation, and how organizational size influences fee structures and service bundling. The full report isolates these variables and maps them against procurement scenarios, helping executives avoid the common pitfall of treating audit spend as a single line item rather than a portfolio of distinct services with divergent growth trajectories and competitive dynamics.
Worldwide Auditing Services Market
Forces Redefining Service Delivery and Competitive Positioning
Behind the headline growth figures lies a set of operational and structural forces that are reshaping how auditing services are produced, priced, and consumed. One of the most consequential pressures confronting the profession is talent scarcity. The accounting and auditing workforce has experienced sustained attrition, with hundreds of thousands of professionals exiting the field over recent years and a marked decline in new entrants passing certification exams. This compression has extended hiring cycles for qualified auditors, increased reliance on technology-enabled workflows, and elevated labor costs within service delivery models. For buyers, this dynamic translates into longer engagement ramp-up periods, potential capacity constraints during peak reporting seasons, and pricing adjustments as firms pass through higher personnel expenses. For providers, it accelerates investment in automation, continuous auditing, and managed service models designed to decouple throughput from headcount constraints. Regulation and assurance expectations are simultaneously expanding the scope of audit work. Sustainability and ESG disclosure have moved from voluntary narrative to assured reporting for a substantial share of large global enterprises, embedding environmental, social, and governance metrics into the core assurance agenda. This shift is altering the skill mix required of audit teams, introducing new data validation challenges, and prompting firms to develop specialized assurance practices that intersect with traditional financial audit workflows. At the same time, regulatory expectations around continuous reporting, integrated audit-risk management, and real-time financial visibility are encouraging the adoption of continuous auditing models. These models shift audit activity from periodic checkpoint exercises toward ongoing monitoring, requiring technology infrastructure that can ingest, reconcile, and evaluate transaction data on a rolling basis. The operational consequence is a profession increasingly defined by data engineering, analytics, and cross-functional coordination rather than manual sampling and retrospective review. For enterprise decision-makers, these dynamics carry strategic weight. Organizations that rely on point-in-time audit relationships may find their assurance coverage misaligned with the pace of operational change and regulatory expectation. Procurement teams must therefore evaluate whether providers possess the technology architecture, data governance maturity, and cross-disciplinary talent to deliver continuous or semi-continuous assurance. Internal audit functions must assess whether their own staffing, tooling, and integration with external auditors are sufficient to support hybrid assurance models that blend periodic independence with ongoing risk monitoring. The full report provides a detailed mapping of these operational shifts, including scenario-based guidance on how technology adoption curves, workforce constraints, and regulatory cadence will interact to shape service delivery economics through the forecast period.
The Competitive Arena: Scale, Differentiation, and Market Concentration
The worldwide auditing market is characterized by a tiered competitive structure in which scale, global network reach, and brand trust remain decisive, even as niche differentiation and sector specialization create space for disciplined challengers. At the top of the competitive hierarchy stand the largest global networks, whose breadth of service lines, multinational coverage, and investment capacity in technology and talent allow them to serve the most complex assurance mandates. Deloitte, headquartered in London, delivers comprehensive external auditing, assurance, and financial statement audit services across public and private entities worldwide, with a pronounced emphasis on technology-enabled audits and sector-specific expertise. Its recent fiscal outcomes underscore the scale of demand across multidisciplinary practices, with aggregate global revenue reported at 70.5 billion USD for fiscal year 2025, reflecting growth driven by audit and assurance alongside adjacent advisory capabilities. PwC, also London-based, provides audit and assurance services that span statutory audits, internal controls assessment, and ESG assurance for multinational clients, with global revenue reaching 56.9 billion USD for fiscal year 2025. Ernst & Young, headquartered in London, offers independent audit services, financial statement audits, and integrated assurance solutions that emphasize digital transformation and sustainability reporting, with global revenue of 53.2 billion USD for fiscal year 2025 and notable growth in assurance and AI-related services. KPMG, based in Amstelveen, specializes in audit, assurance, and risk advisory for large enterprises and public companies globally, completing the quartet of dominant networks. Collectively, these four firms maintained approximately 51 percent share of SEC registrant audit clients in 2025, with Deloitte leading in the number of clients, a concentration metric that illustrates the enduring gravity of the top tier in regulated public company markets. Beyond the top four, a robust second tier of international networks competes with differentiated positioning. BDO, headquartered in Brussels, provides audit and assurance services to mid-market and large clients, with a focus on quality audits and advisory integration. RSM, London-based, delivers audit, tax, and consulting services with emphasis on assurance for middle-market businesses worldwide, leveraging sector depth and responsive service models. Grant Thornton, also London-based, offers independent audit and assurance services tailored to dynamic organizations and public interest entities, often competing on flexibility and relationship intensity. Mazars, Paris-based, provides audit, accounting, and advisory services with a focus on integrated and sustainable assurance solutions, aligning closely with the ESG and reporting convergence trends. Baker Tilly, London-based, delivers audit and assurance services to privately held and public companies across multiple sectors, while Crowe, operating from Chicago with a global network footprint, specializes in audit, assurance, and risk management services for various industries. This competitive field exhibits meaningful concentration. The top three networks command a combined share of approximately 38.5 percent, while the top five reach roughly 49.2 percent of total market revenue. These concentration levels indicate that scale advantages and brand equity remain powerful inhibitors to full market fragmentation, yet they also reveal substantial headroom for mid-tier providers to compete on specialization, service quality, cost efficiency, and sector intimacy. For enterprise buyers, this landscape has direct procurement implications. Large, complex organizations with global footprints may prioritize provider scale, cross-border coordination, and technology investment capacity, accepting premium pricing in exchange for network breadth and regulatory familiarity. Mid-market and privately held organizations may find better value and service alignment with networks that emphasize middle-market focus, integrated advisory, and agility. Public interest entities and regulated sectors may demand providers with demonstrable audit quality records, sector expertise, and robustness in ESG or forensic capabilities. The full report analyzes these competitive dynamics in depth, including provider positioning by service strength, geographic coverage, technology investment posture, and recent financial performance, enabling procurement and finance leaders to match organizational requirements with provider capabilities rather than relying on brand recognition alone.
Actionable Intelligence for 2026 Enterprise Decision-Making
Market research earns its place in the executive agenda when it converts complexity into decision-ready structure. Our Worldwide Auditing Services Market study is designed to do exactly that. Beyond the headline sizing and growth trajectory, the report delivers operational content that supports procurement, risk governance, and strategic planning. The service-type architecture is unpacked with sufficient granularity to help organizations identify which audit and assurance components are expanding most rapidly, where pricing pressure is likely to intensify, and which service bundles are becoming standard versus premium. The regional decomposition provides context for multi-jurisdiction organizations that must coordinate audit relationships across markets with differing regulatory calendars, talent availability, and provider maturity. The organization-size segmentation clarifies how fee expectations, scope assumptions, and service models diverge between large enterprises and smaller entities, supporting realistic budgeting and scope definition. The competitive analysis connects provider profiles with recent financial outcomes and market share movements, enabling side-by-side evaluation of scale, specialization, and strategic direction. The report also incorporates an assessment of market concentration dynamics, helping readers gauge the degree to which provider consolidation or network dominance may influence negotiation leverage, service continuity, and innovation adoption. Importantly, the study frames these insights within the operational currents reshaping the profession. Talent constraints, technology-enabled continuous auditing, ESG assurance integration, and evolving compliance expectations are not treated as isolated narratives, but as interlocking forces that influence pricing, capacity, service design, and procurement strategy. This integrated lens is what separates descriptive market sizing from decision-grade intelligence. Executives using this research can approach 2026 with greater clarity on several fronts. They can model total assurance expenditure with an understanding of which service lines will drive growth and which may face margin compression. They can evaluate external provider options against defined criteria of technology maturity, sector expertise, geographic reach, and financial stability. They can assess internal audit and risk functions against the trajectory of continuous assurance and ESG integration, identifying capability gaps before they become compliance or reporting vulnerabilities. They can anticipate negotiation dynamics by understanding provider concentration, competitive differentiation, and the economic pressures flowing from workforce constraints and regulatory expansion. None of this requires speculation. It requires a structured view of where the market has been, where it is going, and what forces are shaping the path between the two.
Why the Full Study Belongs in Your Strategic Toolkit
Previewing a market study can demonstrate rigor and direction, but the complete analytical architecture is what enables confident execution. The full Worldwide Auditing Services Market report extends the themes outlined here into a comprehensive decision-support system. It details the segmentation splits across regions, service types, and organization sizes without reducing them to abstract percentages, instead translating each split into procurement and strategic implications. It profiles the competitive field with attention to recent financial performance, service emphasis, and positioning logic, giving readers a basis for provider evaluation that goes beyond reputation. It contextualizes market concentration within the practical realities of negotiation, service continuity, and innovation adoption. It addresses the operational dynamics that will influence cost, quality, and timeline outcomes, including workforce pressures, technology adoption, continuous auditing models, and the expansion of ESG and regulatory assurance. And it situates all of this within the forecast window of 2026 through 2032, providing the temporal framing necessary for multi-year budgeting, capability planning, and vendor relationship strategy. The macro data introduced in this preview, including the progression from 194.2 billion USD in 2020 to 259.85 billion USD in 2025, the projected path to 393.8 billion USD by 2032, and the 6.12 percent compound annual growth rate, serve as the backbone of the analysis. Yet the value of the study lies not in the numbers alone, but in the interpretation layer that converts them into choices. Which service components deserve prioritized investment. Which provider profiles align with organizational complexity. Which operational risks require mitigation before they affect assurance coverage. Which regulatory and sustainability trends will reshape scope and pricing. These are the questions that executive teams must answer in 2026, and they cannot be answered through generic market narratives or fragmented vendor pitches. They require a consolidated, evidence-based view of the market as it is structured and as it is evolving. Our report is built for that purpose. It is calibrated for finance leaders, risk and compliance executives, procurement professionals, and strategy teams who need to make audit and assurance decisions with confidence rather than approximation. The insights presented here offer a credible preview of the depth and practical orientation contained in the full study. They demonstrate the analytical discipline, data integration, and decision focus that define the research. For organizations preparing to navigate an audit landscape defined by growth, concentration, regulatory expansion, and operational change, the complete report provides the intelligence necessary to move from understanding to action. We invite you to access the full Worldwide Auditing Services Market research to obtain the comprehensive segmentation detail, competitive profiles, dynamic analysis, and forecasting structure that will support your 2026 decisions and your planning beyond.
For detailed analysis of this topic, please visit the official page:Worldwide Auditing Services Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com










Sign in to leave a comment.