
Strategic Intelligence: Navigating the Vacuum Isolators Market in 2026 and Beyond
The landscape of controlled environment manufacturing is undergoing a pivotal transformation. As industries ranging from pharmaceuticals to semiconductors demand higher levels of containment, sterility, and process integration, vacuum isolators have emerged as critical infrastructure. For stakeholders operating in this sector, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, capacity planning, and competitive positioning.
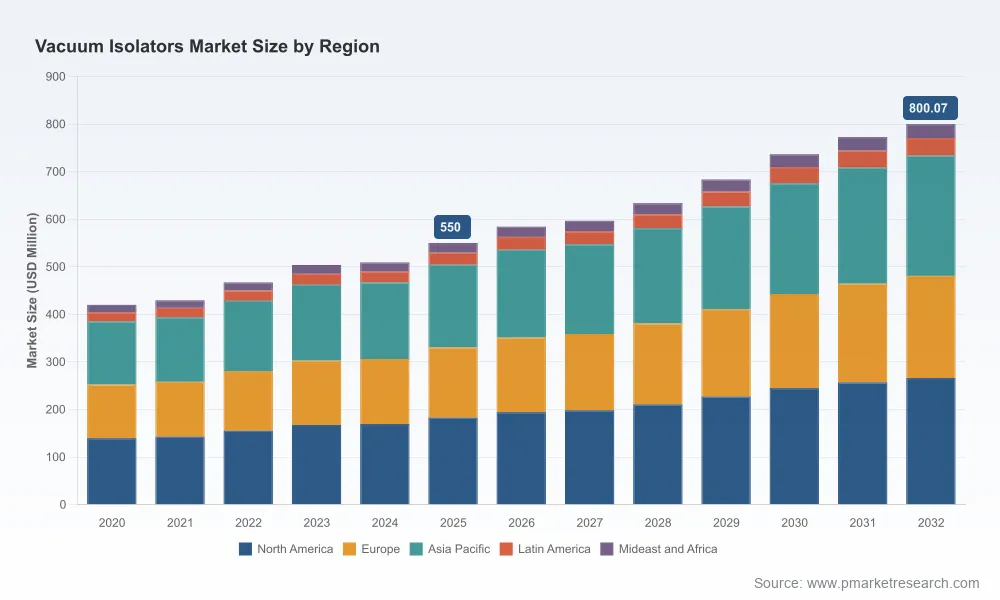
This article serves as a strategic overview of the Vacuum Isolators Market, introducing a comprehensive market research study designed to equip decision-makers with the actionable intelligence needed to navigate the forecast period from 2026 to 2032. The data presented herein reflects a rigorous analysis based on historical performance from 2020 through 2025, projected forward to highlight the opportunities and risks defining the next seven years.
Market Trajectory and Macro Economic Indicators
The vacuum isolators market has demonstrated resilience and steady growth over the past half-decade. Historical analysis from 2020 to 2025 reveals a consistent upward trend, driven by tightening regulatory frameworks and the increasing complexity of manufacturing processes. The total revenue generated by this sector, denominated in USD Millions, underscores the significant capital flowing into containment solutions.
Looking ahead, the market is poised for continued expansion. The forecast period spanning 2026 to 2032 indicates a compound annual growth rate (CAGR) of 5.5 percent. This growth rate suggests a mature yet expanding market where incremental innovations and regulatory compliance drive adoption rather than purely disruptive technology shifts. By the end of the forecast period, the market revenue is projected to reach significant milestones, reflecting the sustained demand for high-integrity isolation systems.
For strategic planners, this trajectory implies that demand will not plateau in the immediate future. Instead, the market will likely see intensified competition and specialization. Companies that fail to align their product portfolios with the evolving requirements of this growth curve risk losing market share to competitors who can offer more integrated, compliant, and cost-effective solutions.
Segmentation Dynamics: Type, Application, and Region
Understanding where value is concentrated is essential for targeted strategy. The market is segmented across various dimensions, including equipment type, application vertical, and geographic region. While specific percentage splits and localized monetary values are detailed within the full report, the broader structural characteristics of these segments offer immediate strategic insights.
Equipment Type
The market is primarily driven by distinct material and configuration types. Stainless steel isolators represent the dominant portion of the market value, reflecting the industry preference for durability, cleanability, and compliance with strict pharmaceutical standards. Acrylic and polymer isolators constitute a significant secondary segment, often favored for specific laboratory applications where visibility or cost considerations are paramount. Additionally, modular custom systems are gaining traction, offering flexibility for facilities that require scalable containment solutions without the footprint of traditional rigid units.
Application Verticals
In terms of end-use, pharmaceutical manufacturing remains the cornerstone of demand. The need for potent compound handling, sterile processing, and containment during dispensing and filling ensures that this vertical consumes the largest share of vacuum isolator resources. However, the semiconductor and electronics sector is a formidable driver of growth. As chip manufacturing processes become more sensitive to contamination, the integration of vacuum isolators in cleanroom environments is becoming increasingly critical.
Digital Isolators Market
Research and academic laboratories, along with the emerging battery and energy storage sector, also contribute to the demand landscape. The battery sector, in particular, represents a high-growth niche where vacuum processes are integral to electrode coating and drying, suggesting a diversification of the customer base beyond traditional life sciences.
Geographic Distribution
Regionally, the market shows a balanced but distinct distribution of revenue. North America and Asia Pacific represent major centers of demand, correlating with high concentrations of pharmaceutical manufacturing and semiconductor fabrication capacity. Europe remains a key market, supported by stringent regulatory environments and a strong legacy of medical device and pharmaceutical production. Latin America and the Middle East and Africa, while smaller in total revenue contribution compared to the major economies, represent emerging opportunities where infrastructure investment is beginning to accelerate.
Competitive Landscape and Strategic Positioning
The vacuum isolators marketplace is characterized by a moderate to high level of concentration. Analysis indicates that a core group of manufacturers controls a significant portion of the market revenue, creating a environment where competitive differentiation is driven by technology integration, service quality, and regulatory expertise.
Key Industry Participants
The competitive arena features several established players with strong regional footholds and specialized capabilities. Companies such as Zhejiang Tailin Bioengineering Co., Ltd. have built reputations in China for offering containment isolators tailored to pharmaceutical dispensing and drying. In Europe, firms like Tema Sinergie and Comecer S.p.A. are recognized for their focus on pharmaceutical isolators, including aseptic and containment systems suitable for vacuum-integrated processes.
SKAN AG, based in Switzerland, stands out as a leading provider of advanced containment and aseptic solutions, often offering customized vacuum-compatible systems that cater to high-value pharmaceutical applications. Similarly, Getinge AB from Sweden provides isolator systems designed for aseptic processing in medical and pharmaceutical settings, supporting integrated vacuum operations.
In the United Kingdom, Extract Technology Ltd. focuses on the design and manufacture of containment and aseptic isolators compatible with vacuum processes for potent compounds. Azbil Telstar in Spain has been active in developing dual-mode systems and vacuum-related solutions for sterile and containment applications. Furthermore, Schematic Engineering Industries in India contributes to the market by manufacturing integrated Vacuum Tray Dryer isolators in both rigid and flexible barrier configurations.
Recent Developments and Innovation Trends
Innovation within this space is visible through recent product launches and technological insights. For instance, Azbil Telstar introduced a new dual-mode isolator system in early 2024, aimed at enhancing flexibility in pharmaceutical processing. Such developments signal a market trend toward versatility, where single systems must accommodate multiple process modes to justify capital expenditure.
Additionally, technology insights highlighted by industry players like Cytiva in early 2026 have drawn attention to the economic advantages of robotic gloveless pharmaceutical isolators over traditional systems. This points to a broader shift toward automation and robotic integration, which reduces operator exposure and improves consistency, aligning with the industry's push for higher quality standards and labor optimization.
Regulatory and Economic Drivers Influencing Decision Making
Strategic planning in the vacuum isolators market cannot be divorced from the regulatory and economic context. Compliance requirements are a primary driver of capital expenditure in this sector. Regulatory frameworks such as the EU GMP Annex 1 require closed isolator systems to correspond to a minimum Grade D background environment for sterile medicinal product manufacturing. These mandates compel manufacturers to invest in compliant equipment, effectively setting a floor for market demand.
Furthermore, the regulatory landscape continues to evolve. The FDA Quality Management System Regulation (QMSR) for medical devices became effective in early 2026, updating quality system requirements relevant to device manufacturing equipment like isolators. Organizations must ensure their equipment selection and validation processes align with these updated requirements to avoid compliance risks.
Capital Expenditure and Cost Considerations
Economic factors also play a decisive role. Average annual capital expenditure on health across OECD countries has remained relatively stable, hovering around 0.6 percent of GDP between 2021 and 2024. While this macro indicator provides context for public sector spending, private sector investment in containment technology is often driven by the specific cost-benefit analysis of production efficiency and risk mitigation.
It is important to note that the high initial investment for pharmaceutical-grade isolators often exceeds $150,000 per system. When validation costs are factored in, ownership costs can increase by 20 to 30 percent. This financial reality underscores the importance of total cost of ownership analysis. Decision-makers must look beyond the sticker price and evaluate the long-term operational costs, including maintenance, validation, and potential downtime.
Optical Isolators Market
Strategic Value of the Comprehensive Report
While the overview presented here outlines the fundamental dynamics, the full Vacuum Isolators Market research report offers a depth of analysis that transforms general awareness into precise strategy. The report is designed to function as a decision-support tool, providing granular data and expert insights that are essential for navigating the forecast period.
Detailed Segmentation Analysis
The report includes deep-dive analyses into the segmentation splits by region, type, and application. Rather than relying on broad generalizations, the study breaks down market sizes and growth rates for specific segments. This allows stakeholders to identify high-growth niches, assess the saturation of mature segments, and benchmark their product offerings against the specific demands of each category. The data provides the granularity needed to answer questions about which regions offer the best ROI for new market entry and which application verticals are most price-sensitive versus performance-driven.
Competitive Benchmarking
Beyond listing key companies, the research provides a nuanced look at the competitive landscape. It examines market concentration metrics, revealing how revenue is distributed among top players. This information is vital for M&A strategy, partnership identification, and understanding the threats posed by incumbent competitors. The report also contextualizes recent developments and strategic moves by major players, offering a timeline of industry evolution that helps predict future competitive behaviors.
Operational and Regulatory Guidance
The report integrates industry context noise, such as regulatory updates and cost structures, directly into the analysis of market dynamics. By correlating regulatory changes like EU GMP Annex 1 and FDA QMSR with market demand, the study helps organizations anticipate compliance-driven purchasing cycles. Additionally, the inclusion of cost data and CapEx trends enables financial modeling that accounts for the real-world economics of isolator procurement and deployment.
PW Consulting Information & Electronics Research Center
Forecast Precision
The forecast data extends through 2032, providing a long-term view that supports multi-year planning. The report details the projected revenue progression year by year, allowing companies to align their production capacity, R&D investment, and sales targets with the expected market trajectory. This precision reduces uncertainty and enables more confident strategic commitments.
Conclusion: Acting on Intelligence
The Vacuum Isolators Market is at a stage where growth is supported by robust regulatory drivers and expanding applications in high-tech industries. The projected CAGR of 5.5 percent through 2032 indicates that this is not a fleeting opportunity but a sustained trend. However, capturing value in this market requires more than a general understanding of growth; it demands precise knowledge of where demand is originating, who is competing for it, and how regulatory and economic factors will influence purchasing decisions.
For executives, procurement leaders, and strategic planners, the risk of operating without detailed intelligence is significant. Misjudging segment demand, underestimating competitive pressure, or overlooking compliance nuances can lead to costly misallocations. The comprehensive market research study provides the necessary depth to mitigate these risks and capitalize on the opportunities within the vacuum isolators sector.
To access the full spectrum of data, including precise segmentation values, detailed company profiles, and extended forecast tables, stakeholders are encouraged to consult the complete report. This intelligence asset is designed to empower organizations to make informed, data-driven decisions that secure their position in a competitive and evolving market landscape.
For detailed analysis of this topic, please visit the official page: Vacuum Isolators Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com






















Sign in to leave a comment.