
Navigating the Flexible Surgical Robot Revolution: Strategic Imperatives for 2026 and Beyond
The landscape of minimally invasive surgery is undergoing a tectonic shift. For decades, robotic surgery has been dominated by rigid, multi-port platforms that require significant incision sites and extensive operating room footprint. However, the next frontier is not about bigger arms or more degrees of freedom in a fixed plane—it is about flexibility, navigability, and access. As we move into 2026, the flexible surgical robot market is no longer a theoretical niche; it is a rapidly maturing sector poised to redefine how clinicians interact with complex anatomies. Our latest research provides a granular roadmap of this transformation, offering enterprise leaders the intelligence needed to navigate capital allocation, partnership strategies, and regulatory positioning in a market projected to reach nearly $1.6 billion by 2032.
Flexible Surgical Robot Market
Macroeconomic Momentum: Growth Beyond the Early Adopters
The financial trajectory of flexible surgical robotics tells a story of accelerating adoption that outpaces traditional surgical robotics growth curves. Analysis of market history from 2020 through 2025 reveals a consistent upward climb, with market size expanding from approximately $281 million in 2020 to $620 million in 2025. This more than doubling of value in five years underscores a critical turning point: flexible platforms are transitioning from investigational concepts to commercially viable solutions. Looking forward, the forecast period from 2026 to 2032 suggests sustained momentum, with the market expected to approach $1.6 billion by the end of the decade. This expansion is underpinned by a compound annual growth rate of 14.5 percent, a figure that signals robust demand and validates the strategic urgency for stakeholders to engage now rather than wait for market maturation.
Flexible Surgical Robot Market
For corporate strategists and investors, these aggregate figures serve as a baseline for opportunity sizing. However, the true value of our comprehensive report lies in deconstructing what drives this growth. The headline numbers mask the divergent adoption rates across clinical indications, the varying penetration of different mechanical architectures, and the regional disparities influenced by reimbursement policies and healthcare infrastructure. Understanding these underlying currents is essential for accurate forecasting and risk management. Our analysis provides the detailed breakdowns necessary to move beyond top-line estimates and into actionable scenario planning.
Flexible Surgical Robot Market
Segmentation Dynamics: Technology Architectures and Clinical Applications
The flexible surgical robot ecosystem is not monolithic. It is defined by distinct mechanical approaches that cater to specific procedural needs and anatomical constraints. Our report categorizes the market by mechanism, analyzing the competitive strengths and limitations of catheter-based systems, endoscope-based platforms, and needle or flexible-tooling systems. Catheter-based architectures have established a dominant share of the market, reflecting their proven utility in vascular and endoluminal navigation. Endoscope-based systems represent a substantial and growing segment, leveraging compatibility with existing GI and pulmonology workflows to accelerate adoption. Meanwhile, needle and flexible-tooling systems are emerging as high-potential niches, offering the potential for sub-millimeter precision in tight spaces such as the bladder or biliary tree.
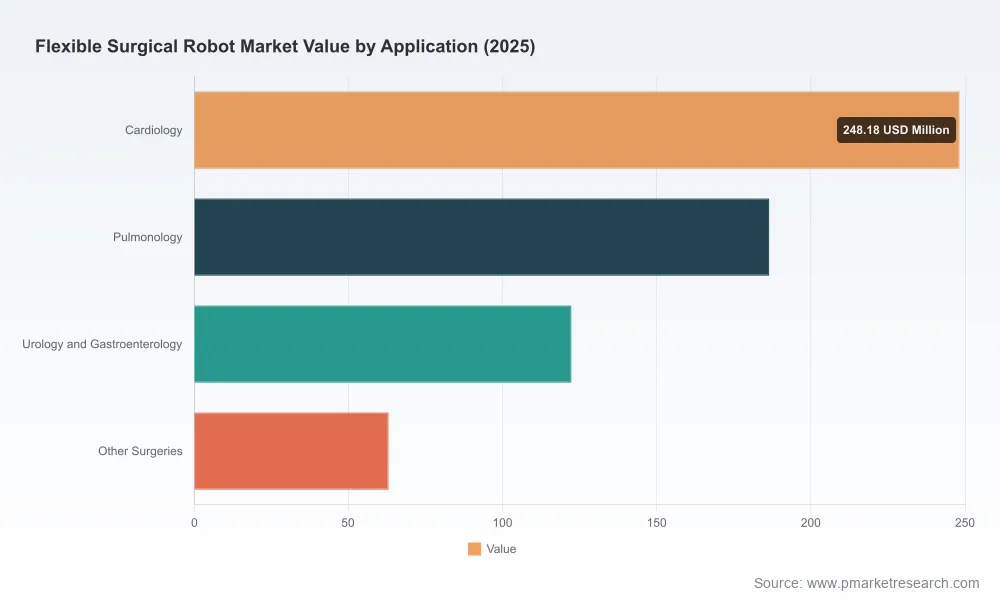
Equally critical is the application landscape, which reveals how clinical demand is shaping technology development. Cardiology remains a primary driver, with robotic navigation enabling safer access to distal lesions and complex bifurcations. Pulmonology has seen a surge in interest, particularly in bronchoscopic interventions where robotic assistance improves lesion targeting and reduces procedure variability. Urology and gastroenterology continue to expand their scope, utilizing flexible platforms for tumor resections, stone management, and reconstructive procedures. Other surgical applications are also beginning to emerge as flexible robotics prove their versatility. Each application vertical carries its own regulatory pathways, reimbursement profiles, and surgeon training requirements. Our research dissects these application-specific dynamics, providing insights into which segments offer the fastest returns and which require longer investment horizons.
Competitive Landscape: Innovation Leaders and Strategic Positioning
The competitive arena is characterized by a mix of specialized innovators and major medtech conglomerates, creating a complex environment for market entry and partnership. Market concentration data indicates that a small group of players controls a significant portion of revenue, with the top three companies accounting for over 58 percent of the market and the top five holding more than 76 percent. This concentration suggests both high barriers to entry and the importance of strategic alliances for new entrants. Our report provides detailed profiles of key companies shaping the market, examining their technology platforms, geographic footprints, and clinical milestones.
EndoQuest Robotics, based in Houston, Texas, has emerged as a notable leader in endoluminal surgery. The company's Endoluminal Surgical System is designed for scar-free access through natural orifices, aiming to perform complex procedures without external incisions. Recent clinical activity has underscored the system's potential; in late 2025, EndoQuest completed the first robotic ESD procedure at the Mayo Clinic as part of the PARADIGM multicenter trial, targeting a complex colorectal lesion. This milestone was preceded by significant capital reinforcement, including a Series D-2 funding round co-led by Crescent Enterprises and Dr. Fred Moll, which will support the PARADIGM trial and platform advancement. Earlier regulatory progress, including FDA Investigational Device Exemption clearance in late 2024, has paved the way for these clinical investigations, positioning EndoQuest at the forefront of translational flexible robotics.
Agilis Robotics, headquartered in Hong Kong, is pursuing a distinct strategy focused on extreme miniaturization. The company develops fully flexible robotic instruments with diameters ranging from 2.8 to 3.5 millimeters, designed to integrate with standard endoscopes for gastrointestinal, urinary, and other procedures. This approach promises to lower the learning curve by leveraging familiar endoscopic workflows while adding robotic precision and stability. Virtuoso Surgical, located in Nashville, Tennessee, is advancing robotic endoscopic capabilities through needle-sized concentric tube manipulators. These structures offer enhanced dexterity within rigid endoscopic environments, with specific applications in bladder lesion removal and other urologic interventions where access and manipulation are traditionally challenging.
Johnson & Johnson, through its Auris Health subsidiary and the Monarch Platform, represents the scale and integration capability of large incumbents. The Monarch Platform provides a flexible robotic system for bronchoscopy and endoluminal navigation, demonstrating the potential for broad clinical deployment supported by a global commercial network. The presence of such established players highlights the increasing convergence of flexible robotics with broader surgical ecosystems and the value of combining innovation with distribution strength. Our analysis compares these and other players across dimensions of technology maturity, clinical validation, commercialization readiness, and partnership potential, enabling readers to identify where collaboration or acquisition may create the most value.
Market Dynamics: Reimbursement, Regulation, and Economic Realities
The growth of the flexible surgical robot market is influenced by forces that extend well beyond technology performance. Reimbursement frameworks are evolving, creating both opportunities and constraints. Recent updates have introduced new coding structures that support robotic-assisted procedures, such as Category III CPT codes for lymphovenous bypass incorporating robotic assistance, alongside CMS reimbursement adjustments relevant to robotic microsurgery. These developments signal a gradual recognition of the clinical and economic value of robotic precision in specific high-need areas. However, reimbursement remains fragmented, and the path to sustainable revenue often depends on demonstrating clear outcomes improvements and cost offsets. Our report examines the reimbursement landscape across key markets and procedures, offering guidance on how to navigate coding changes and build the evidence base required for coverage expansion.
Regulatory pathways continue to shape product development and market access. The FDA maintains active review processes for robotic surgical systems through 510(k) and De Novo pathways, with recent clearances reflecting a preference for modular and flexible designs tailored to specific indications such as urologic interventions and cholecystectomy. This regulatory trend favors focused device strategies and encourages iterative innovation. Companies must align their clinical evidence generation with the expectations of reviewers, ensuring that safety and effectiveness claims are supported by robust data. Our research tracks regulatory trends and provides insights into how companies can optimize their development timelines and documentation strategies to accelerate clearance without compromising compliance.
Economic considerations also play a central role in hospital adoption. The total cost of ownership for robotic platforms involves complex calculations that include initial capital expenditure, ongoing maintenance, and per-procedure disposable instruments. Flexible systems may offer advantages in terms of reduced facility costs or shorter recovery times, but the financial equation must be compelling for healthcare providers operating under budget constraints. Our analysis addresses these economic realities, exploring how pricing models, disposable utilization, and procedural efficiency influence adoption decisions. This economic perspective is vital for companies designing commercial strategies and for procurement teams evaluating technology investments.
Strategic Applications of Our Report for 2026 Decision Making
For executives, investors, and clinical leaders preparing for the 2026 operating environment, this report serves as a comprehensive intelligence asset. The detailed segmentation analysis allows strategists to identify high-growth sub-segments and prioritize resources accordingly. Whether the focus is on catheter-based navigation for cardiology, endoscope-integrated instruments for gastroenterology, or needle-scale manipulators for urology, our findings provide the comparative context needed to assess opportunity size and competitive intensity. The regional breakdowns further enable market entry planning, revealing where regulatory support, reimbursement readiness, and clinical demand create the most favorable conditions for expansion.
The competitive profiles and recent development tracking offer a real-time view of the innovation cycle. By monitoring clinical trials, funding events, and regulatory milestones, decision makers can anticipate shifts in the market and adjust their strategies proactively. Companies considering partnerships, licensing, or M&A can use our analysis to evaluate potential targets based on technology differentiation, clinical validation status, and commercial trajectory. Investors can gain clarity on which technologies are approaching inflection points and which segments carry higher execution risk. The integration of reimbursement and regulatory insights ensures that strategic plans are grounded in the practical realities of market access, reducing the likelihood of costly missteps.
Our report also addresses the operational dimensions of flexible robotic adoption. Topics such as surgeon training, workflow integration, infection control, and data connectivity are examined to help organizations understand the full implications of deploying these systems. As flexible platforms become more integrated into standard care pathways, the ability to manage change and optimize utilization will become a competitive differentiator. The intelligence provided in this study supports not only market strategy but also operational planning, enabling stakeholders to build the infrastructure and expertise needed to capture long-term value.
Conclusion: Seizing the Flexible Robotics Opportunity
The flexible surgical robot market is entering a phase of accelerated development where innovation, clinical evidence, and commercial execution converge. The growth trajectory projected through 2032 reflects a market that is expanding in both scale and sophistication. Companies that understand the nuances of segmentation, regulatory dynamics, reimbursement evolution, and competitive positioning will be best positioned to capture share and drive sustainable growth. This report delivers the depth and breadth of analysis required to make informed strategic decisions in a rapidly evolving environment.
To access the complete dataset, detailed segmentations, full competitive assessments, and region-specific forecasts, we invite you to explore the full Flexible Surgical Robot Market research. The insights contained within are designed to support confident decision making and to provide a clear roadmap for navigating the opportunities and challenges of this dynamic sector.
For detailed analysis of this topic, please visit the official page:Flexible Surgical Robot Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com

















Sign in to leave a comment.