
Navigating the Vaginal Pessary Market: Strategic Insights for 2026 and Beyond
The global vaginal pessary market stands at a critical inflection point as healthcare providers increasingly prioritize non-surgical interventions for pelvic floor disorders. Based on a comprehensive analysis tracking performance from 2020 through 2032, the sector demonstrates resilient growth trajectories that demand careful strategic positioning from manufacturers, distributors, and clinical stakeholders. This market research delivers the analytical rigor required to navigate regulatory shifts, reimbursement complexities, and evolving product preferences that will define competitive outcomes through the end of the decade.
Market Trajectory and Growth Dynamics
Historical performance from 2020 to 2025 reveals a consistent expansion pattern, with the market advancing from 235.5 million USD to 320.0 million USD over the five-year period. This growth reflects sustained demand for conservative management options in pelvic organ prolapse and stress urinary incontinence, conditions that affect millions of women globally and drive recurring consumption of pessary devices. The base year valuation of 320.0 million USD establishes a robust foundation for forward-looking projections that extend through 2032.
The forecast period from 2026 to 2032 projects the market to reach 492.13 million USD, representing a compound annual growth rate of 6.5 percent. This trajectory underscores the structural nature of demand rather than temporary fluctuations. Year-over-year expansion demonstrates acceleration in the early forecast window, with 2026 expected to reach 352.45 million USD, followed by progressive gains that peak at 492.13 million USD by 2032. The consistency of this growth curve signals to strategic planners that market entry, product development, and capacity expansion decisions should be calibrated against a multi-year horizon rather than short-term volatility.
Several macro factors support this expansion. An aging female population, increasing awareness of pelvic floor health, and a growing preference for non-invasive management protocols collectively expand the addressable patient base. Healthcare systems facing cost pressures increasingly view pessary therapy as a cost-effective alternative to surgical intervention, particularly for patients who are poor surgical candidates or who prefer to delay operative procedures. These dynamics create a favorable environment for sustained commercial activity, though they also intensify competitive scrutiny among established manufacturers and emerging entrants alike.
Clinical Applications and Product Segmentation Landscape
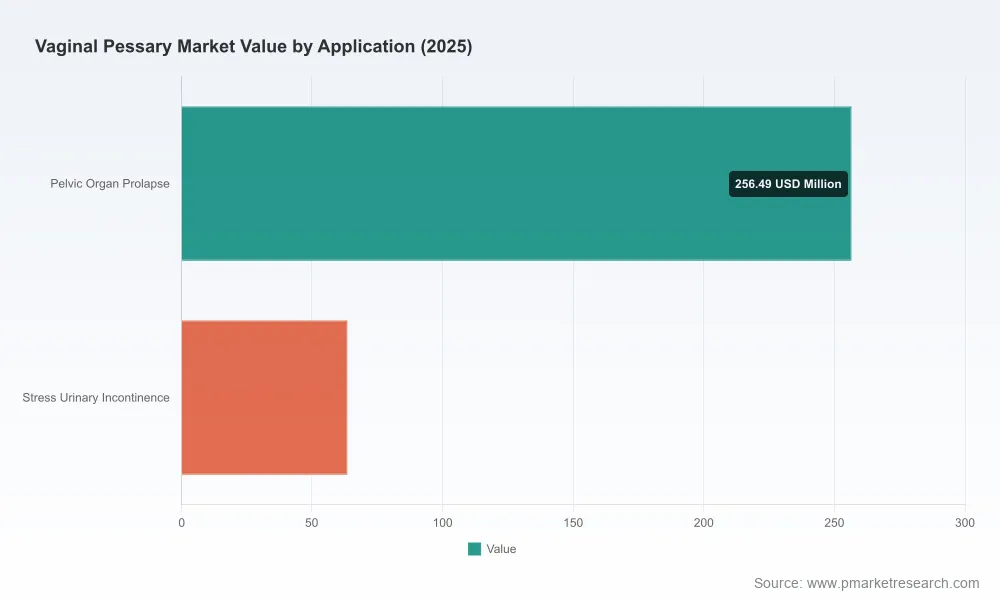
The market serves two primary clinical indications that together define the core revenue architecture. Pelvic organ prolapse represents the dominant application, reflecting the broad prevalence of conditions affecting the anterior, posterior, and apical vaginal compartments. Stress urinary incontinence constitutes a significant secondary segment, driven by patient populations seeking conservative management before considering surgical sling procedures or other operative options. The interplay between these indications shapes product development priorities, clinical education initiatives, and reimbursement strategies across different healthcare settings.
Product design diversity remains a defining characteristic of the competitive field. Ring configurations, gellhorn structures, donut geometries, cube variants, and specialized designs each address distinct anatomical requirements and patient comfort preferences. The availability of multiple styles within individual product lines allows clinicians to tailor fittings to individual patient anatomy, which in turn supports higher retention rates and longer device utilization. Manufacturers that maintain comprehensive portfolios spanning ring, gellhorn, cube, donut, and folding configurations position themselves to capture demand across varying clinical scenarios and practitioner preferences.
Material selection introduces additional strategic considerations. Traditional PVC constructions continue to serve local practice environments due to favorable cost profiles and established clinical familiarity. Silicone alternatives command premium pricing but offer extended service life when maintained properly, with some devices supporting multiple wash cycles over extended periods if structural integrity remains intact. The reimbursement environment accentuates this material tension, as billing codes differentiate between rubber and non-rubber constructions, creating economic incentives that influence both procurement decisions and physician prescribing patterns. Understanding these material economics is essential for pricing strategy, portfolio mix optimization, and market segmentation targeting.
Competitive Landscape and Strategic Positioning
The competitive architecture features a mix of established manufacturers with broad pelvic health portfolios and specialized players focusing intensively on pessary solutions. CooperSurgical, headquartered in Connecticut, maintains a prominent position through its Milex® Pessary line, which encompasses more than twenty-five styles including ring, gellhorn, cube, donut, and folding designs. The company supplies clinics and practices worldwide, leveraging distribution infrastructure and clinical support resources to sustain market presence. Its breadth of offerings allows engagement with diverse fitting requirements and supports relationships with high-volume clinical settings.
MedGyn Products, based in Illinois, emphasizes comprehensive fitting solutions with complete pessary fitting sets that include twenty-eight pessaries across multiple designs and sizes. This approach addresses the diagnostic and fitting workflow directly, supporting clinicians in achieving optimal device selection during initial consultations. The availability of ring configurations with and without support, knobbed variants, cube designs, and dish structures enables systematic exploration of patient anatomy during the fitting process. Companies that supply complete fitting ecosystems benefit from the recurrent need for size verification and style adjustment as patient conditions evolve.
Vaginal Pessary Market
Bioteque America contributes to the market with silicone ring, dish, and cerclage pessaries that address pelvic organ prolapse, urinary incontinence, and cervical support requirements. The emphasis on silicone construction aligns with settings where longer device life and reduced allergic risk are prioritized. Panpac Medical Corporation, operating from Canada, focuses on FDA-cleared disposable and flexi-shelf pessaries for uterine prolapse and stress urinary incontinence, targeting segments where single-use convenience or flexible shelf configurations meet specific clinical needs.
International participation adds geographic and technological diversity. Cetro Medical, based in Israel, manufactures doughnut-type and other pessaries for pelvic organ prolapse management. ConTIPI Medical, also headquartered in Israel, has pursued an aggressive commercialization path with its ProVate disposable vaginal ring pessary designed for at-home use. Thomas Medical, located in Indiana, offers various pessary styles including ring and cube configurations for pelvic support. The Bray Group, based in the United Kingdom, produces PVC and other ring-type pessaries for prolapse management, reflecting the continued relevance of cost-effective materials in certain practice environments.
Recent commercial activity illustrates the dynamic nature of this competitive field. ConTIPI Medical executed a U.S. commercial launch of its ProVate disposable vaginal ring pessary in December 2024, making the device available for physician prescribing with six sizes and at-home insertion capability via an applicator. This launch followed an August 2024 partnership with EVERSANA to support U.S. commercialization and rollout, demonstrating how specialized manufacturers leverage external commercialization capabilities to accelerate market penetration. Separate regulatory milestones occurred in 2024, with FDA 510(k) clearances granted for the Gynethotics™ Pessary and the Reia collapsible reusable vaginal pessary, both addressing pelvic organ prolapse and related conditions. These clearances expand the available device options and signal ongoing innovation within the Class II medical device framework.
Regulatory Framework and Reimbursement Architecture
Vaginal pessaries operate within a defined regulatory environment that shapes product development timelines, compliance obligations, and market access strategies. These devices are classified as Class II medical devices under FDA regulations, specifically governed by 21 CFR 884.3575 with product code HHW. The classification requires 510(k) premarket notification and subjects manufacturers to general controls including good manufacturing practices. This regulatory pathway creates a baseline requirement for technical documentation, performance testing, and quality system adherence that all market participants must satisfy. The clearance activity observed in 2024 confirms that new entrants can navigate this pathway successfully when they present distinct technological characteristics or intended uses that differentiate their devices from predicate products.
Reimbursement mechanisms directly influence clinical adoption and patient access. HCPCS Level II codes A4561 and A4562 govern vaginal pessary billing, with A4561 covering rubber pessaries and A4562 covering non-rubber constructions, typically silicone. The higher reimbursement rate associated with A4562 creates a financial dynamic that rewards silicone device utilization, while the reduced allergic risk profile of silicone adds a clinical rationale for selection. This code structure means that material choice carries both economic and clinical implications, and manufacturers must align their product specifications with the reimbursement categories that optimize value for healthcare providers and patients.
Procedural coding further shapes the economic model. Fitting and insertion of pessaries are reported using CPT code 57160, which carries a zero-day global period. In practice, modifier -25 is often added when the fitting occurs during an annual examination, allowing separate reimbursement for the procedural component. This coding configuration supports clinical workflows where fitting and routine examination coincide, and it reinforces the importance of proper documentation to ensure appropriate reimbursement. Providers and manufacturers alike benefit from clarity around these coding practices, as they affect the total cost of care and the financial viability of pessary management programs.
Strategic Priorities for 2026 Decision-Making
Enterprise strategy for 2026 must account for multiple intersecting forces. Market growth at a 6.5 percent compound annual rate through 2032 provides a supportive backdrop, but growth alone does not guarantee competitive success. Companies need to differentiate across product design, material selection, fitting support, and commercialization execution to capture demand in a market where concentration metrics indicate meaningful presence by leading participants.
Portfolio architecture requires careful calibration. Manufacturers that offer comprehensive style coverage, from ring to gellhorn to cube to donut configurations, position themselves to serve diverse clinical needs and reduce the risk of missing demand in any single category. At the same time, specialized focus on particular segments, such as disposable devices for at-home use or collapsible reusable designs that improve handling, can create differentiated value propositions that resonate with specific patient populations and clinical workflows. The strategic question is not whether to pursue breadth or depth, but how to align portfolio composition with the intended customer base and the reimbursement environment in which those customers operate.
Regulatory strategy demands proactive engagement. The Class II framework requires 510(k) submissions that demonstrate equivalence to predicate devices or justify differences through performance data. Companies introducing new designs, materials, or use models must anticipate the documentation burden and timeline implications of premarket notification. Recent clearance activity shows that the pathway remains viable for innovation, but success depends on rigorous preparation and clear differentiation from existing devices. Firms that invest in regulatory readiness early gain advantages in time-to-market and can establish presence before competitors navigate the same requirements.
Commercial execution increasingly involves partnerships and specialized capabilities. The collaboration between ConTIPI Medical and EVERSANA illustrates how manufacturers can leverage external commercialization infrastructure to support U.S. rollout, prescription access, and market education. As the market expands, companies with limited internal commercial resources may find partnership models attractive for accelerating distribution, supporting clinical training, and building awareness among prescribing physicians. The availability of comprehensive fitting sets from certain manufacturers also highlights the value of enabling the clinical workflow end-to-end, rather than supplying devices in isolation.
Reimbursement literacy is a competitive necessity. Understanding the distinctions between HCPCS codes A4561 and A4562, the implications of CPT code 57160 with modifier -25, and the material-related tradeoffs between PVC and silicone allows manufacturers to design products, position pricing, and support customers in ways that align with the economic realities of clinical practice. Providers make procurement and prescribing decisions within reimbursement constraints, and manufacturers that demonstrate awareness of these constraints build credibility and facilitate adoption.
Research Scope and Analytical Coverage
This market research delivers a structured examination of the vaginal pessary industry across multiple analytical dimensions. The study encompasses historical performance data from 2020 through 2025, establishing a validated baseline that anchors forward projections. The forecast period extends from 2026 through 2032, providing a long-view perspective that supports capacity planning, investment prioritization, and scenario analysis. Revenue figures are presented in million USD, enabling consistent comparison across periods and facilitating integration with financial models used by corporate planning teams.
The analysis addresses market segmentation across region, type, and application, with detailed enumeration reserved for the full report to protect the integrity of proprietary estimates. Key companies are profiled with attention to headquarters location, product offerings, and market activities that reflect competitive positioning. Recent developments, including commercial launches, partnership announcements, and regulatory clearances, are documented to provide a current view of industry momentum. Industry context materials covering reimbursement codes, material cost considerations, and regulatory classifications are integrated to support practical decision-making rather than abstract observation.
Concentration metrics indicate that leading participants hold substantial market share, with the top three firms collectively representing a significant portion of industry revenue and the top five firms extending that footprint further. This concentration pattern underscores the importance of differentiated strategy for companies seeking to gain share or defend position. The report examines the implications of this structure for new entry, product innovation, and competitive response, providing context that helps planners assess realistic pathways to growth.
Pelvic Organ Prolapse Repair Device Market
Conclusion
The vaginal pessary market offers a constructive growth environment shaped by demographic trends, clinical preference for non-surgical management, and a regulatory and reimbursement framework that supports device utilization. Achieving competitive success in 2026 and beyond requires more than awareness of market size and compound annual growth rate. It demands detailed understanding of product design preferences, material economics, reimbursement dynamics, regulatory requirements, and the commercialization strategies employed by established and emerging participants. This research provides that understanding, equipping strategic decision-makers with the intelligence needed to position portfolios, allocate resources, and respond to industry developments with confidence. For organizations seeking to translate market awareness into actionable strategy, the complete report offers the depth and specificity required to support rigorous planning and informed execution.
For detailed analysis of this topic, please visit the official page: Vaginal Pessary Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com
























Sign in to leave a comment.