
Financial markets are moving toward a model where assets can exist in digital form and interact with different financial applications. RWA Tokenization is an important part of this shift because it represents real-world assets such as real estate, private credit, bonds, commodities, funds, and other financial instruments as blockchain-based tokens.
Composable finance adds another layer by allowing these tokenized assets to interact with lending, trading, settlement, collateral, and portfolio applications.
Instead of treating each tokenized asset as an isolated digital representation, composable finance allows assets to participate in a broader financial environment. A token representing a real estate fund, for example, could potentially be used within an approved lending application or portfolio management system. This creates a connection between asset ownership, financial applications, and blockchain infrastructure.
For businesses considering Real World Asset Tokenization, this development changes how platforms may be designed. The focus is no longer limited to issuing tokens. Businesses also need to consider how those tokens can interact with other applications while maintaining compliance, asset records, investor permissions, custody arrangements, and transaction controls.
What Is RWA Tokenization?
RWA Tokenization refers to representing ownership, rights, claims, or economic interests associated with physical or traditional financial assets through blockchain-based tokens. The asset remains connected to its legal and operational structure, while the token provides a digital representation that can be recorded and transferred through blockchain infrastructure.
Common examples include tokenized real estate, government securities, private equity interests, investment funds, commodities, invoices, and private credit. Each asset category has different legal, valuation, custody, and transfer requirements, so tokenization projects usually require more than smart contract development.
An RWA Tokenization Company may develop infrastructure for asset onboarding, token issuance, investor verification, wallet management, compliance checks, trading, reporting, and settlement. The exact structure depends on the asset class and the jurisdictions in which the platform operates.
The growing interest in tokenized assets comes from the possibility of creating more programmable financial instruments. Once an asset is represented digitally, certain rules can be incorporated into the transaction process, such as investor eligibility, transfer restrictions, holding periods, and distribution calculations.
What Does Composable Finance Mean for Tokenized Assets?
Composable finance describes a financial model where digital assets and applications can interact through compatible technical standards and interfaces. In a tokenized asset market, this means an asset does not necessarily have to remain inside the application where it was issued.
For example, a tokenized bond could potentially interact with a portfolio application, a lending protocol, or a settlement system if the necessary technical, legal, and compliance conditions are satisfied. The token becomes part of a wider financial environment rather than remaining limited to one platform.
This approach can create several possible use cases. Tokenized assets may serve as collateral, become part of diversified portfolios, interact with automated settlement systems, or be used in structured financial products. However, these functions require carefully designed permission systems and legal frameworks because real-world assets carry rights and obligations that cannot be represented by code alone.
How RWA Tokenization and Composable Finance Work Together
The relationship between tokenization and composable finance can be understood through several layers.
The first layer is the underlying asset. This could be a property, bond, private credit instrument, commodity, or investment fund. The second layer contains legal documentation and ownership arrangements. The third layer represents the asset through a blockchain token. The fourth layer consists of financial applications that interact with the token.
For example, consider a tokenized commercial property. The property may be held through a legal entity, while investors receive digital tokens representing defined economic rights. After issuance, those tokens could potentially be accepted by an approved lending application as collateral. A portfolio application could also track the tokens alongside other holdings.
This interaction creates a financial environment where tokenized assets can have functions beyond ownership representation. The important consideration is that every interaction must respect the rights attached to the underlying asset.
Why Composability Matters for Asset Infrastructure
Traditional financial assets often operate within separate systems. A fund may have one platform for investor records, another for reporting, another for custody, and another for transactions. Moving information between these systems can involve manual processes and multiple intermediaries.
Tokenization provides a common digital representation, while composability introduces the possibility of connecting that representation with other applications. This can reduce the need for repeated data entry and create more direct connections between different financial services.
For investors, the result could be a broader range of ways to use digital assets. For financial businesses, it creates opportunities to develop services around tokenized collateral, portfolio management, secondary markets, lending, payments, and asset servicing.
This does not mean every token should interact with every protocol. Permissioned environments may remain necessary for regulated assets. Composability in RWA markets is therefore likely to develop around controlled access rather than unrestricted interaction.
The Role of Smart Contracts
Smart contracts provide much of the technical logic behind tokenized assets. They can define how tokens are issued, transferred, redeemed, and restricted. In a composable financial environment, smart contracts also determine how external applications can interact with tokenized assets.
For example, a smart contract may check whether an investor is eligible to receive a particular token before allowing a transfer. Another contract may calculate distributions based on token holdings. A lending application may check whether a token is an approved collateral asset before accepting it.
This makes smart contract design particularly important for RWA projects. Developers need to consider business rules, compliance requirements, asset lifecycle events, permission models, oracle data, and upgrade mechanisms.
RWA tokenization development therefore involves both blockchain engineering and financial system design. The technology needs to reflect the legal and operational structure surrounding the asset.
How Businesses Can Use Composable RWA Infrastructure
Businesses can approach composable finance through several practical methods.
One method is tokenized collateral. Businesses can represent eligible assets digitally and allow approved financial applications to evaluate those tokens for collateral purposes. This could create new lending arrangements around assets that previously required more manual processes.
Another method is portfolio construction. Investors may hold different tokenized assets within one portfolio interface. A platform could display real estate, bonds, private credit, and other assets in one environment, subject to the applicable regulations.
A third method is automated asset servicing. Smart contracts and connected applications can support activities such as distribution calculations, ownership updates, redemption processing, and investor notifications.
A fourth method is secondary market integration. Tokenized assets can potentially be transferred through approved trading venues, allowing eligible investors to participate in secondary transactions without creating a completely separate representation of ownership for each venue.
The Technology Stack Behind Composable RWA Platforms
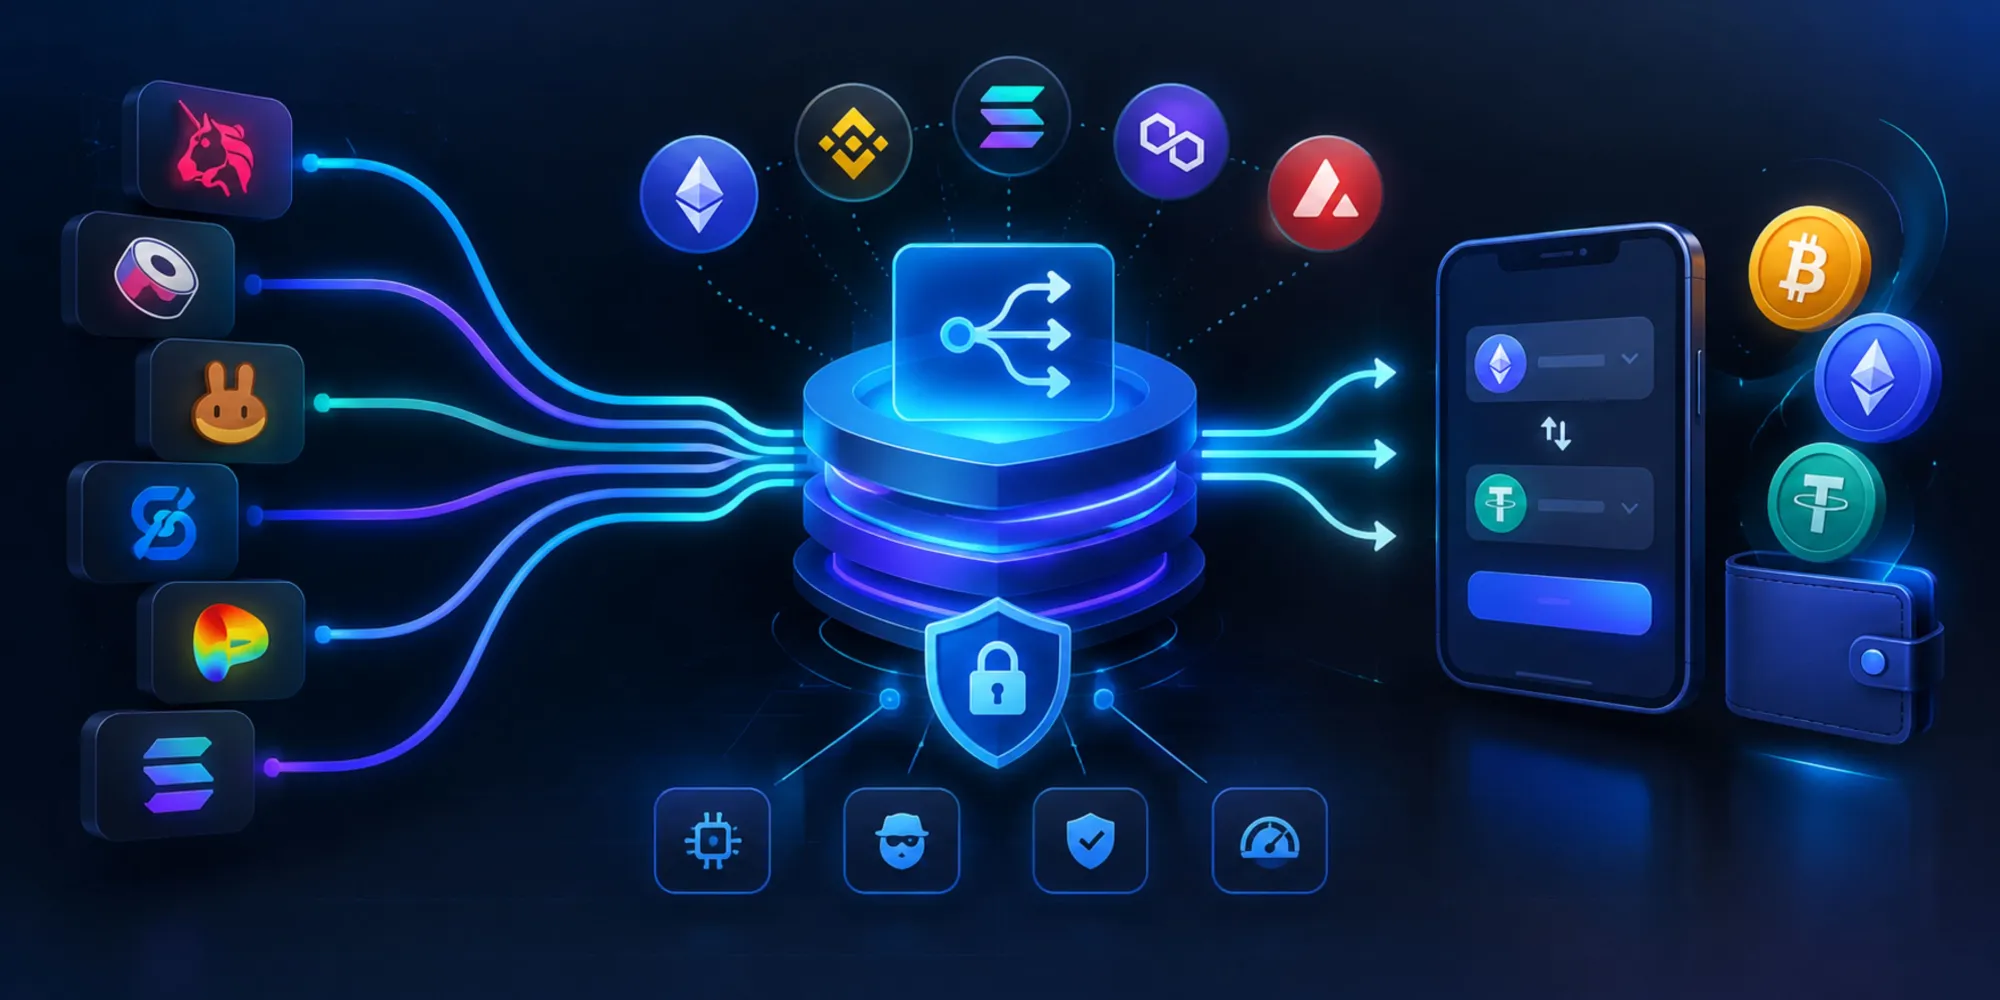
A composable RWA platform usually includes several technical layers. The blockchain network provides transaction recording and token management. Smart contracts define asset and transaction rules. Wallet infrastructure manages investor accounts and digital assets.
Identity and compliance systems handle investor verification, eligibility checks, sanctions screening, and jurisdiction restrictions. Custody infrastructure manages asset security where required. Oracles may provide information such as asset prices, interest rates, valuation data, or other external information needed by applications.
APIs and integration layers connect the tokenization platform with external financial applications. This is particularly important for composable finance because applications need reliable ways to read asset information and submit permitted transactions.
A well-planned rwa tokenization platform development project therefore needs to consider both internal platform functions and external application connectivity.
Compliance Considerations for Composable Tokenized Assets
Composability introduces regulatory questions that businesses cannot ignore. A token may represent an investment contract, ownership interest, debt claim, fund unit, or another regulated instrument depending on its structure and jurisdiction.
If that token is later used with another financial application, businesses need to determine whether the second application is permitted to interact with the asset. Investor eligibility, transfer restrictions, custody requirements, reporting obligations, and applicable securities regulations may continue to apply after token issuance.
For this reason, Real World Asset Tokenization Services increasingly need to account for compliance throughout the asset lifecycle. Compliance should not be treated as a one-time check performed only when an investor first purchases a token.
Permissioned tokens, identity-linked wallets, transfer restrictions, and transaction monitoring can be used where appropriate. Legal and regulatory advice should guide the specific design for each market.
Challenges Facing Composable RWA Markets
Despite the potential, several challenges remain. Different blockchain networks may use different token standards and technical structures. Financial institutions may also use different data formats and internal systems.
Legal enforceability is another major consideration. A digital token must have a well-defined relationship with the underlying asset and the rights held by its owner. If this relationship is unclear, technical interoperability does not solve the underlying legal problem.
Liquidity is also important. A tokenized asset may be technically transferable but still have limited market activity. Composability can provide more places where an asset could be used, but market demand remains necessary for meaningful trading activity.
Security presents another challenge. Smart contract vulnerabilities, compromised wallets, inaccurate external data, and poorly designed permissions can create financial risks. Platforms therefore need testing, monitoring, access controls, and ongoing maintenance.
What RWA Token Development May Look Like Next
RWA token development is likely to move toward infrastructure that supports multiple financial functions rather than simple token issuance. Businesses may seek platforms where assets can be issued, managed, transferred, monitored, and connected with approved financial applications from one environment.
An RWA tokenization development company may therefore work on modular systems containing token issuance, compliance, custody, investor management, asset servicing, APIs, analytics, and application integrations.
RWA tokenization development services may also focus more heavily on interoperability. Businesses may want tokenized assets to communicate with multiple blockchain networks and financial applications without creating separate systems for every use case.
This direction could make tokenized assets more useful within institutional financial workflows. Instead of being viewed simply as digital certificates, they may become programmable components within broader financial systems.
How Businesses Can Prepare for This Shift
Businesses planning an RWA project should begin by identifying the asset type, investor group, target jurisdictions, legal structure, custody model, and intended token functions. These decisions affect the technical architecture and compliance requirements.
The next step is to define how the token will interact with other systems. If the business expects lending, trading, portfolio management, or asset servicing applications to interact with the token, those requirements should be considered during platform planning.
Businesses should also establish standards for identity, permissions, data access, smart contract management, and external integrations. Starting with a limited asset class or controlled pilot can help teams evaluate the operational model before expanding to additional assets.
Conclusion
RWA Tokenization and composable finance represent a broader direction for digital asset infrastructure, where tokenized real-world assets can participate in multiple financial functions rather than remaining confined to a single platform. Real World Asset Tokenization can provide the digital representation, while composable finance can connect that representation with approved applications for lending, portfolio management, trading, settlement, and asset servicing. Businesses need to consider legal structures, investor permissions, custody, smart contracts, interoperability, data systems, and compliance when planning these platforms. An RWA Tokenization Company can support this process through Real World Asset Tokenization Services and RWA Tokenization Services designed around the asset and business model. Blockchain App Factory provides RWA tokenization development services for businesses looking to develop tokenized asset platforms, including RWA token development, compliance-focused infrastructure, smart contract systems, and rwa tokenization platform development.
FAQs
1. What is RWA Tokenization?
RWA Tokenization is the process of representing rights or economic interests connected to real-world assets through blockchain-based tokens. These assets can include real estate, bonds, funds, commodities, and private credit.
2. What is composable finance?
Composable finance refers to financial applications and digital assets interacting with one another through compatible technical systems. In RWA markets, this can allow approved tokenized assets to participate in different financial functions.
3. Can tokenized real estate be used as collateral?
Potentially, yes. If the legal structure, token design, lender requirements, and applicable regulations permit it, tokenized real estate interests may be considered for collateral arrangements.
4. Why are smart contracts important for RWA platforms?
Smart contracts can manage rules for token issuance, transfers, investor permissions, distributions, redemption, and other asset-related activities.
5. What does an RWA tokenization development company do?
An RWA tokenization development company can provide technology development for token issuance, smart contracts, investor management, compliance systems, custody integration, asset servicing, APIs, and related platform functions.
6. What are RWA Tokenization Services?
RWA Tokenization Services can cover the technical and operational components required to represent real-world assets digitally, including token design, smart contract development, platform development, integrations, and asset management functions.
7. Is composable finance suitable for every tokenized asset?
No. The suitability depends on the asset type, legal structure, investor restrictions, regulatory requirements, technical standards, and the applications that need to interact with the token.
8. What is the future of RWA token development?
RWA token development is likely to move toward assets that can participate in several approved financial applications while retaining appropriate ownership, compliance, and transfer controls. This may make tokenized assets more useful within digital financial infrastructure.










Sign in to leave a comment.