

Portfolio management has traditionally depended on financial institutions, fund managers, custodians, brokers, and a range of administrative processes. Investors usually interact with funds through established financial channels, while ownership records, subscriptions, redemptions, reporting, and settlement are handled across separate systems. Tokenized funds introduce a different approach by representing fund interests as blockchain-based tokens and recording relevant transactions through distributed ledger infrastructure.
This model is gaining attention within the wider RWA tokenization market because investment funds can represent a practical use case for bringing traditional financial assets onto blockchain networks. A tokenized fund can represent ownership interests in assets such as private equity, bonds, real estate, credit instruments, commodities, or other investment products. Instead of treating the fund only as an entry in a traditional database, the ownership interest can also exist as a programmable digital token subject to defined rules.
For businesses considering RWA tokenization platform development, tokenized funds present an opportunity to rethink how portfolio management systems handle ownership, investor participation, reporting, settlement, and compliance. The technology does not remove the need for financial regulations or professional fund management. Rather, it introduces blockchain-based infrastructure into selected parts of the investment lifecycle.
Method 1: Representing Fund Ownership Through Digital Tokens
A tokenized fund begins with the representation of an investor's interest as a digital token. Depending on the fund structure and applicable regulations, each token can correspond to a particular ownership percentage, unit, share, or economic interest in the fund.
Instead of maintaining ownership information only through conventional databases, the token contract can record wallet ownership and relevant transaction activity on a blockchain. The fund manager can connect this token layer with off-chain records that contain investor information, accounting data, asset valuations, and regulatory documentation.
For an RWA tokenization company, fund tokenization therefore involves much more than issuing a blockchain token. The system must connect the token with the legal structure of the fund and define how subscriptions, transfers, distributions, redemptions, and investor permissions work.
Method 2: Giving Portfolio Managers More Frequent Ownership Data
Traditional fund reporting often works around scheduled statements and periodic updates. Portfolio managers may receive information from administrators, custodians, valuation providers, and other parties before making portfolio decisions.
Tokenized funds can provide a more continuous record of token ownership and transaction activity. When investors subscribe to or transfer eligible fund tokens, those activities can be recorded on-chain. Portfolio management systems can then connect blockchain data with internal financial systems.
This does not mean that every portfolio metric becomes real-time. Asset valuation, for example, may still depend on appraisal processes, market prices, accounting procedures, or external data providers. However, ownership and transaction records can be updated more frequently, giving fund managers another source of portfolio information.
An RWA tokenization development company can design dashboards that combine blockchain activity with conventional portfolio data. Managers could view token holdings, investor positions, transaction history, asset allocation, and fund performance within one interface.
Method 3: Making Fund Access More Fractional
Investment funds frequently involve minimum investment requirements that can restrict participation. Tokenization can divide eligible fund interests into smaller digital units, subject to the fund's legal and regulatory framework.
For example, a fund holding a portfolio of private credit assets could issue a large number of tokens representing fractional interests. Investors could acquire a smaller portion rather than purchasing a large fund position directly.
Fractional ownership can also affect how portfolio managers think about investor distribution. A fund may have the ability to accommodate different investor segments while maintaining separate eligibility requirements for each category.
However, fractionalization does not automatically make an investment available to everyone. Securities laws, investor accreditation requirements, geographic restrictions, transfer rules, and fund documentation still apply. The token infrastructure must reflect these requirements rather than treating tokenization as a replacement for regulation.
Method 4: Applying Rules Directly to Fund Tokens
Smart contracts can contain predefined conditions governing how tokens behave. In a tokenized fund, these conditions could cover investor eligibility, transfer restrictions, holding limits, distribution mechanisms, or redemption procedures.
For instance, if a fund is restricted to verified investors, the platform can connect wallet addresses with an approved investor registry. A transfer can then be checked against eligibility requirements before it is processed.
This approach gives an RWA tokenization platform development project a programmable compliance layer. The precise rules depend on the fund structure, jurisdiction, and legal advice, but the technical system can be designed to apply those rules consistently.
Smart contracts should still be subject to testing, audits, monitoring, and administrative controls. A coding error or incorrect rule can create financial and operational problems, so tokenized fund systems require careful contract design.
Method 5: Improving Subscription and Redemption Workflows
Fund subscriptions and redemptions can involve multiple parties and several administrative steps. Investors submit requests, fund administrators verify information, payments are processed, ownership records are updated, and confirmations are issued.
Tokenized funds can connect several of these activities through blockchain infrastructure. An investor may submit a subscription request through a platform, complete identity verification, transfer the required funds, and receive eligible tokens after approval.
Redemption can follow a similar process. The platform can verify the investor's holdings, check the applicable redemption conditions, calculate the relevant amount, and initiate the required settlement process.
The exact process varies according to whether the fund permits frequent redemptions, periodic windows, lockups, or other restrictions. An RWA tokenization development project should therefore start with the fund's operating model before deciding which processes should be automated.
Method 6: Creating a Shared Portfolio Record
Portfolio management involves information from many sources. Fund managers may depend on administrators, custodians, brokers, valuation providers, auditors, and other service providers.
Blockchain infrastructure can act as a shared transaction record for selected activities. When token ownership changes, authorized participants can reference the same ledger rather than maintaining completely separate transaction histories.
This can reduce discrepancies between records when the blockchain layer is properly connected with off-chain systems. It can also provide an auditable history of token movements.
A Real-world asset tokenization company working on fund infrastructure may therefore combine blockchain records with APIs, accounting systems, investor databases, custody services, identity verification tools, and reporting platforms.
Method 7: Supporting Portfolio Rebalancing
Portfolio managers regularly review asset allocations and adjust positions according to investment mandates. Tokenized fund interests can provide more granular data about investor ownership and fund activity, which may support portfolio administration.
Suppose a fund invests across corporate debt, real estate, and private equity. Each asset category can have different valuation schedules, liquidity conditions, and holding periods. The tokenized representation can provide a digital record of investors' interests in the overall fund while portfolio systems continue managing the underlying assets.
Tokenization does not decide when a manager should rebalance a portfolio. Investment decisions remain with the fund manager and depend on the fund strategy. The value comes from having an additional digital infrastructure layer for ownership, transactions, and administration.
Method 8: Connecting Tokenized Funds With Secondary Markets
One of the most discussed possibilities around tokenized funds is secondary trading. Traditional private market investments can have limited transfer opportunities because transactions may require approvals, paperwork, and direct coordination between parties.
A tokenized fund can potentially support secondary transfers through compliant trading venues or marketplaces. Investors may be able to transfer eligible tokens when the fund's legal structure permits it.
This does not mean that every tokenized fund will become freely tradable. Lockups, investor eligibility, transfer restrictions, market liquidity, and regulatory requirements can limit secondary activity.
For an RWA tokenization platform development company, this creates a need for marketplace functions that check investor status, token restrictions, transaction limits, and settlement conditions before a trade takes place.
Method 9: Linking Portfolio Analytics With Blockchain Data
Portfolio management increasingly depends on data. Managers monitor allocation, returns, investor flows, transaction activity, risk exposure, and other metrics.
A tokenized fund platform can feed blockchain transaction data into analytics systems. Managers can examine token issuance, transfers, redemptions, wallet activity, and investor concentration alongside traditional portfolio information.
This can create a more detailed view of fund activity. For example, a manager may identify changes in investor holdings without waiting for a later reporting cycle, provided the relevant data is available and properly integrated.
An RWA token development project can include analytics dashboards, portfolio monitoring tools, investor reports, transaction histories, and administrative controls to support these requirements.
Method 10: Reducing Manual Administrative Work
Fund administration contains many repetitive tasks, including ownership updates, document handling, investor verification, transaction reconciliation, and reporting. Tokenization can automate selected parts of these workflows.
For example, when an approved investment transaction is completed, the platform can update token ownership automatically through a smart contract. Related records can then be synchronized with internal systems.
Automation does not remove administrators from the process. Human review remains important for exceptions, regulatory decisions, valuation questions, disputed transactions, and unusual investor activity.
The practical objective is to reduce repeated manual actions while preserving appropriate controls and review processes.
What a Tokenized Fund Platform May Need
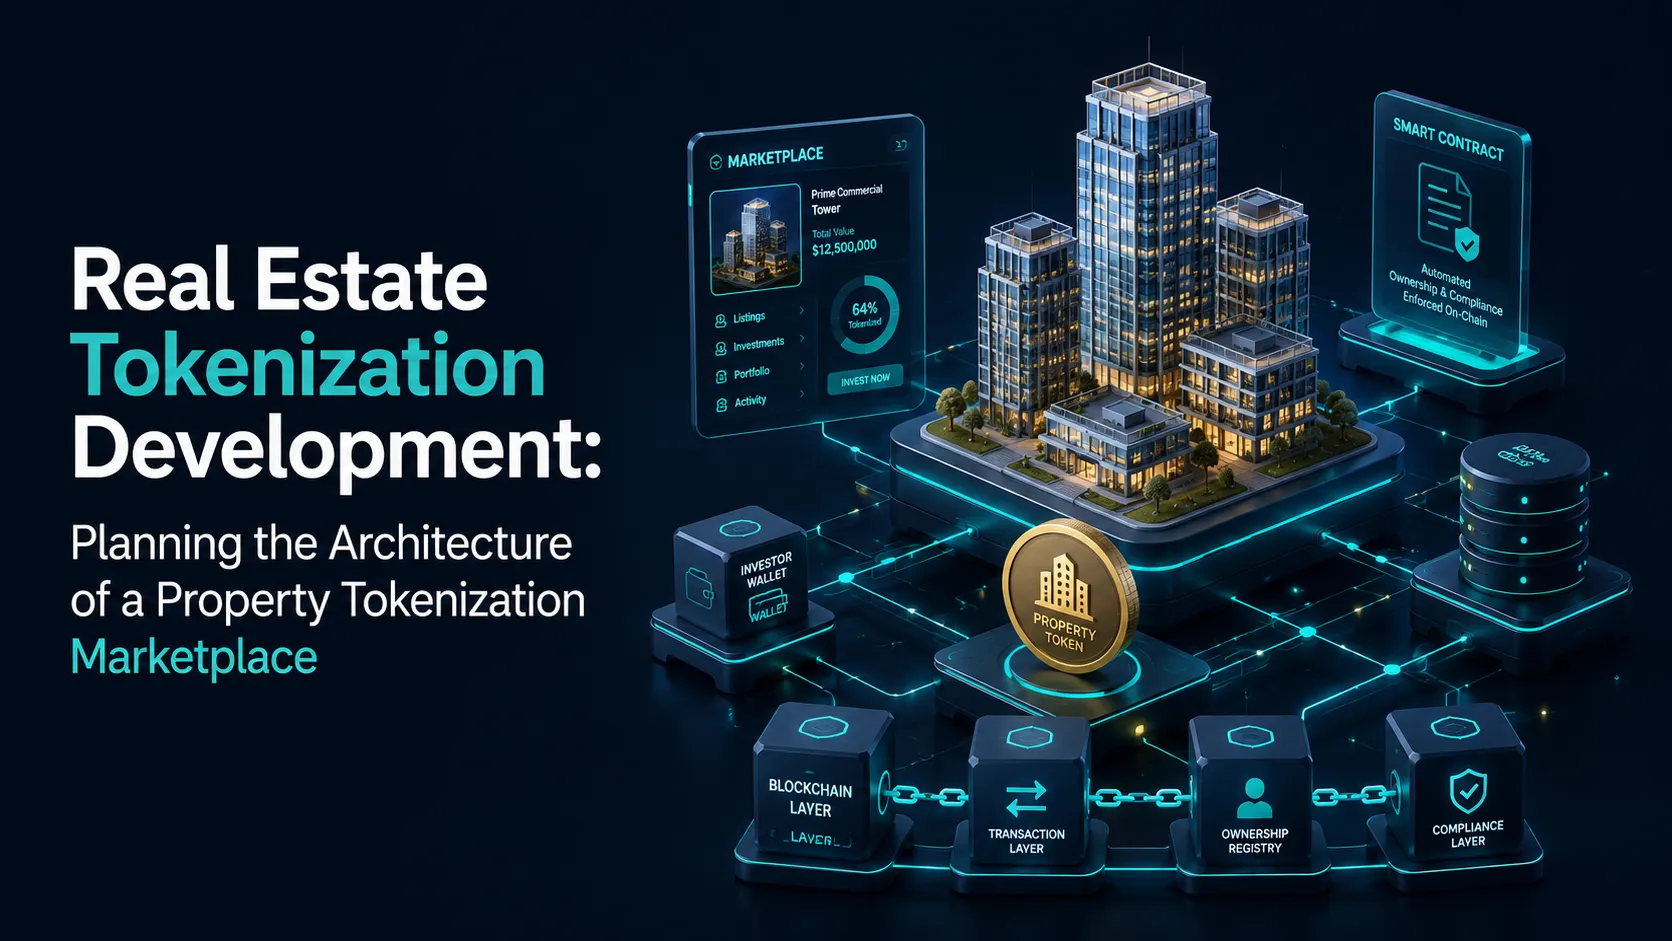
A complete tokenized fund ecosystem can contain several connected components. These may include investor onboarding, identity verification, wallet management, token issuance, smart contracts, fund administration, payment processing, portfolio dashboards, compliance controls, reporting tools, custody integration, and secondary trading functionality.
The blockchain network is only one part of the system. The platform also needs connections to off-chain databases and financial infrastructure because many fund activities cannot exist entirely on-chain.
Security also deserves significant attention. Smart contract vulnerabilities, compromised wallets, unauthorized access, incorrect permissions, and data inconsistencies can create serious risks. Testing, contract audits, role-based access, transaction monitoring, and recovery procedures should therefore be considered during RWA tokenization development.
Business Considerations Before Launch
Businesses considering tokenized funds should first determine what asset class the fund will hold and what type of investor it will serve. The legal structure should be established before the technical architecture is finalized.
The business should also define how tokens represent ownership, where investor records are maintained, how distributions occur, whether transfers are permitted, and how redemptions are processed.
Choosing an RWA tokenization company should involve more than evaluating blockchain development capabilities. Businesses should assess experience with token standards, smart contracts, investor onboarding, compliance workflows, custody integrations, financial APIs, security testing, and fund-related infrastructure.
The technology should follow the investment model rather than forcing the fund to operate according to the limitations of a particular blockchain design.
Future Role of Tokenized Funds in Portfolio Management
Tokenized funds could gradually become part of a broader digital investment infrastructure. As financial institutions experiment with blockchain-based fund structures, portfolio management may increasingly combine traditional financial systems with token-based ownership records.
The most important change may not be the token itself. It may come from connecting ownership, compliance, settlement, reporting, and investor access within a shared digital workflow.
For portfolio managers, this could create more frequent access to transaction information and new ways to manage investor positions. For investors, tokenized structures may offer smaller investment units and different forms of access where regulations and fund policies permit them.
The development path will depend on regulation, market adoption, custody infrastructure, investor demand, and the willingness of financial institutions to integrate blockchain systems into existing operations.
Conclusion
Tokenized funds could change portfolio management by introducing blockchain-based ownership records, programmable fund rules, fractional interests, digital settlement, automated administrative processes, and new possibilities for compliant secondary transfers. Their value will depend on how effectively these capabilities connect with conventional fund structures, regulatory requirements, valuation systems, custody services, and investor workflows. RWA tokenization platform development is therefore becoming a broader financial infrastructure project rather than a simple token issuance exercise. Businesses entering this market need to consider fund structure, investor eligibility, smart contract design, data management, security, compliance, custody, and reporting before launch. With the right operating model, tokenized funds could give portfolio managers a different way to manage ownership information and investment administration as digital asset markets mature. Blockchain App Factory provides RWA tokenization development services for businesses looking to develop tokenized asset and investment platforms around their specific business requirements.
FAQs
1. What are tokenized funds?
Tokenized funds are investment funds where ownership interests or fund units are represented through blockchain-based digital tokens. The token can represent an investor's eligible interest in the fund according to its legal and operational structure.
2. How can tokenized funds affect portfolio management?
Tokenized funds can provide digital ownership records, programmable transaction rules, more frequent transaction updates, fractional fund interests, and automated administrative workflows. These capabilities can give portfolio managers additional tools for monitoring and managing fund activity.
3. Is RWA tokenization suitable for investment funds?
RWA tokenization can be suitable for certain investment fund structures, including funds holding assets such as real estate, private credit, securities, commodities, and other eligible assets. Suitability depends on the fund structure, jurisdiction, investor requirements, and regulatory framework.
4. What technologies are used in tokenized fund development?
A tokenized fund platform may use blockchain networks, smart contracts, token standards, wallets, identity verification systems, APIs, databases, portfolio dashboards, custody infrastructure, payment systems, and compliance tools.
5. Can investors trade tokenized fund tokens?
Potentially, but trading depends on the fund structure, applicable regulations, investor eligibility, transfer restrictions, lockup periods, and whether a compliant secondary market is available.
6. What does RWA token development involve?
RWA token development can involve token design, smart contract development, asset representation, ownership rules, investor permissions, compliance conditions, wallet integration, issuance mechanisms, transfer logic, and connections with off-chain financial systems.
7. Why is compliance important in tokenized funds?
Tokenized fund interests may fall under securities or other financial regulations depending on the structure and jurisdiction. Compliance controls can help manage investor eligibility, transfer restrictions, identity verification, reporting requirements, and other regulatory obligations.
8. How does an RWA tokenization development company help with tokenized funds?
An RWA tokenization development company can provide technical services covering token contracts, blockchain infrastructure, investor platforms, fund dashboards, compliance integrations, custody connections, APIs, security testing, and other components required for a tokenized fund ecosystem.











Sign in to leave a comment.