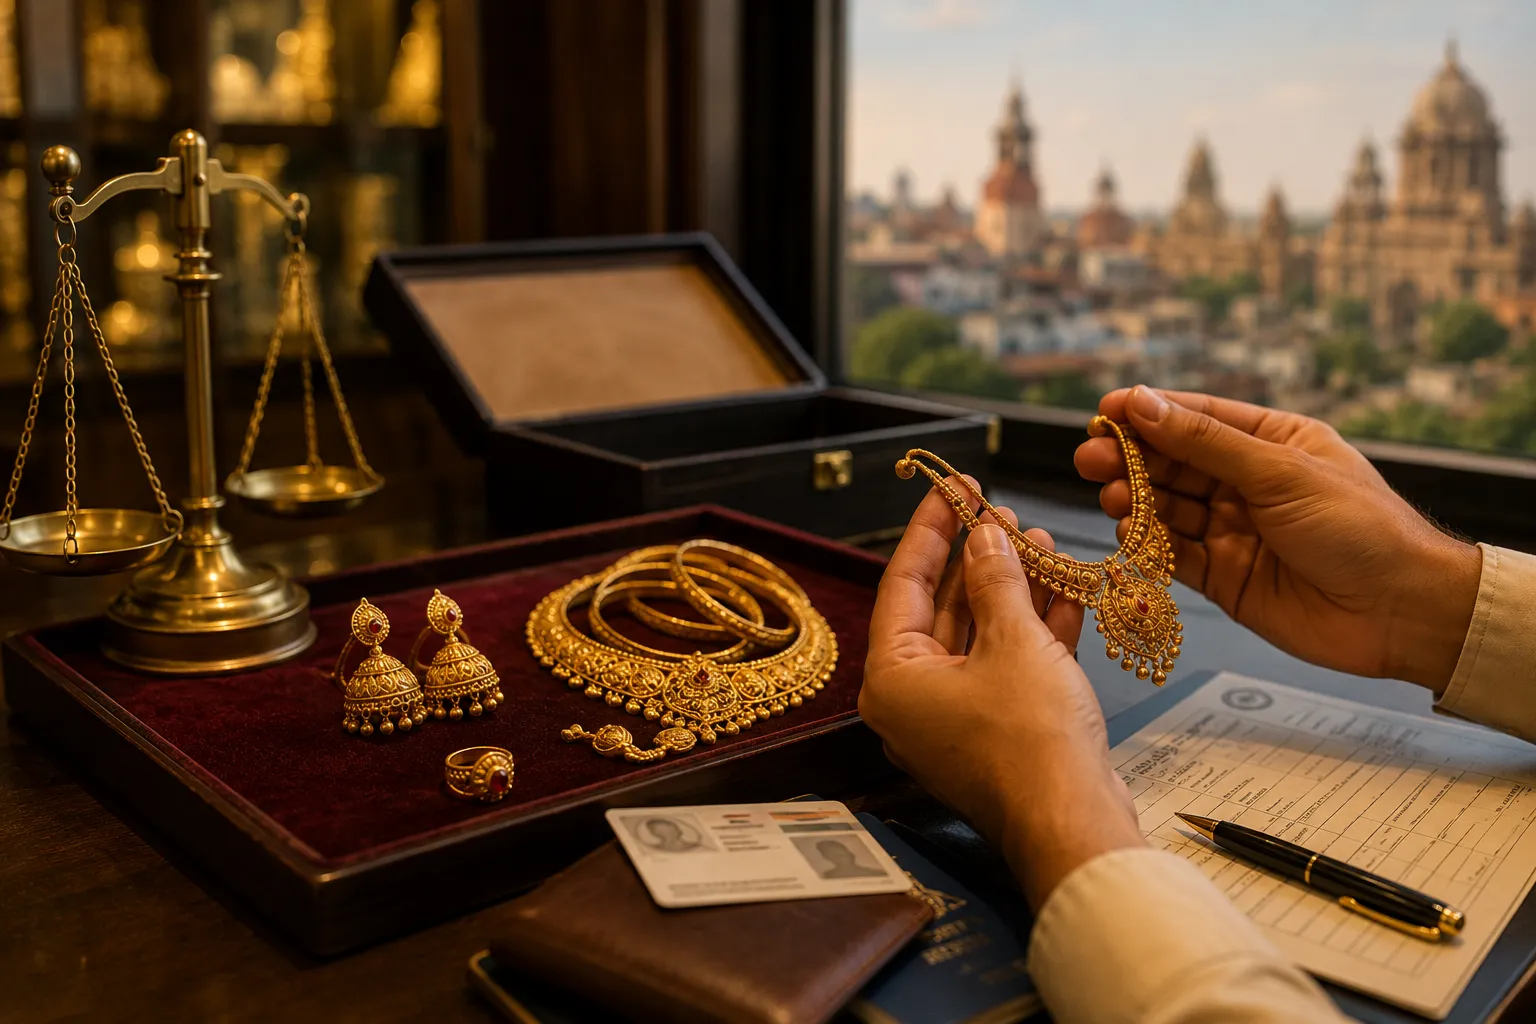

Bought a gold necklace in Delhi and now want to sell it in Gurugram? Or perhaps you purchased jewellery in Mumbai, Jaipur, or another city and have moved elsewhere. Many people wonder if a local buyer can legally purchase gold that was bought in another city. The good news is that the place where you originally bought the jewellery usually does not stop you from selling it. Even when looking for cash for gold in Gurgaon, what matters more is your identity, ownership, the jewellery’s purity, and proper transaction records.
The process is fairly simple. But a few documents and tax points can make a big difference. Here is what you should know before handing over your jewellery.
Does the City Where You Bought Gold Matter?
In most cases, no.
You are not required to sell gold in the same city where you purchased it. A genuine buyer can assess jewellery bought from another state or city and make an offer based on its current purity, weight, and market value.
However, the buyer may ask questions about where the jewellery came from. This is especially common for high-value transactions.
Your original purchase invoice is useful here. It helps establish when and where you bought the item and can support your ownership claim.
BIS itself advises consumers to keep authentic bills or invoices for hallmarked jewellery. Such records can help in disputes, complaints, and other verification needs.
Documents You Should Carry When Selling Gold
1. Original purchase bill
This is one of the most useful documents you can have.
The bill may show:
- Date of purchase
- Jewellery description
- Net gold weight
- Purity or fineness
- Hallmarking details
- Purchase price
- Jeweller information
Even if the jewellery is several years old, do not throw away the invoice.
2. Identity proof
A buyer may request identity and transaction details, particularly for a higher-value sale. Keep a valid government-issued identity document and PAN details available when required.
The purpose is straightforward. Established buyers need to maintain proper records and comply with applicable tax and financial rules.
3. Proof of ownership
An invoice is usually the strongest evidence. If you inherited the jewellery or received it as a gift, the situation can be different.
For inherited gold, keep documents such as a will, succession-related papers, or other evidence of inheritance where available. For gifted jewellery, supporting gift documentation can also be useful.
What If the Jewellery Has a BIS Hallmark?
A hallmark can make the evaluation easier.
Modern hallmarked gold jewellery generally carries the BIS logo, purity mark and a six-digit HUID number. Consumers can use the BIS Care system to verify a HUID.
But there is an important point: old or unhallmarked jewellery can still be sold to a jeweller. BIS specifically confirms that consumers can sell old hallmarked as well as unhallmarked jewellery to jewellers.
So, lack of a hallmark does not automatically mean your gold cannot be sold.
If you are unsure about purity, you can also have jewellery tested at a BIS-recognised Assaying and Hallmarking Centre. These centres can test consumer jewellery for a fee and issue an assay report.
How Buyers Calculate the Value
Do not expect to receive the original purchase price.
Gold jewellery contains more than the value of pure gold. Your original bill may include making charges, wastage charges, GST and design-related costs. These amounts are generally not recovered in full when you sell the item.
The buyer normally focuses on factors such as:
- Net gold weight
- Purity
- Current gold price
- Refining or melting requirements
- Applicable deductions
- Whether stones or other non-gold components are present
This is why two buyers can give different quotes for the same jewellery.
A reputable second hand gold jewellery buyer should explain the testing method, weight and calculation before finalising the offer.
Is Gold Sale Income Taxable?
It can be.
Gold jewellery held for personal use can be treated as a capital asset. If you sell it for more than its applicable cost, the resulting gain may fall under capital gains rules. The Income Tax Department states that profits arising from the transfer of a capital asset are generally taxable under the head “Capital Gains.”
The holding period also matters. Under the current framework, assets covered by the general 24-month rule become long-term after being held for more than 24 months. Long-term capital gains on applicable assets are generally taxed at 12.5%, subject to the specific provisions that apply to your transaction.
Keep your original purchase invoice because the purchase cost is important when working out the gain. If the jewellery was inherited or gifted, the tax calculation can involve different rules.
For a large transaction, speak with a tax professional before filing your return.
Should You Accept a Cash Payment?
Be careful with large cash transactions.
Cash receipts are subject to restrictions under India's tax laws, and high-value transactions can also create reporting and documentation concerns. The Income Tax Rules require PAN-related transaction documentation for certain transactions exceeding specified thresholds, including certain goods transactions above ₹2 lakh.
For a substantial gold sale, a bank transfer or another traceable payment method is generally easier to document.
Always ask for a proper sale receipt or transaction statement showing the amount paid and relevant details.
How to Sell Gold Bought in Another City Safely
Compare more than one offer
Do not accept the first quote. Ask at least two or three established buyers to assess the jewellery.
Watch the weighing process
Make sure the jewellery is weighed in front of you. Ask how stones, beads or other non-gold parts are being treated.
Ask for the purity test
Understand whether the buyer is using XRF testing, fire assay, or another method. Ask for the result before agreeing to the price.
Check the final calculation
The quoted gold rate is only one part of the equation. Ask for the net weight, purity, rate used and deductions separately.
A transparent calculation is a good sign.
Why Choosing the Right Buyer Matters
Selling gold is not simply about finding the highest headline rate. Trust matters just as much.
A professional buyer should clearly explain the valuation process, provide transaction records and answer questions about purity and deductions. Established names such as Sona Chandi Buyers can be considered when you want a structured evaluation and a transparent selling process.
Most importantly, do not feel pressured to sell immediately. Take your invoice, verify the jewellery details, compare offers and understand the final amount before signing anything.
Ready to Sell Your Gold? Start With a Trusted Buyer
Gold bought in another city can generally be sold without travelling back to the original jeweller. The key is proper documentation and a transparent valuation.
Carry your purchase bill and identity documents. Check the hallmark or HUID where applicable. Confirm the purity and net weight. Understand deductions. Keep a complete record of the sale. And remember that tax treatment depends on your individual circumstances and the nature and holding period of the gold.
If you are ready to sell, choose a trusted buyer that explains every step instead of simply quoting a price. A careful evaluation today can help you avoid surprises later.











Sign in to leave a comment.