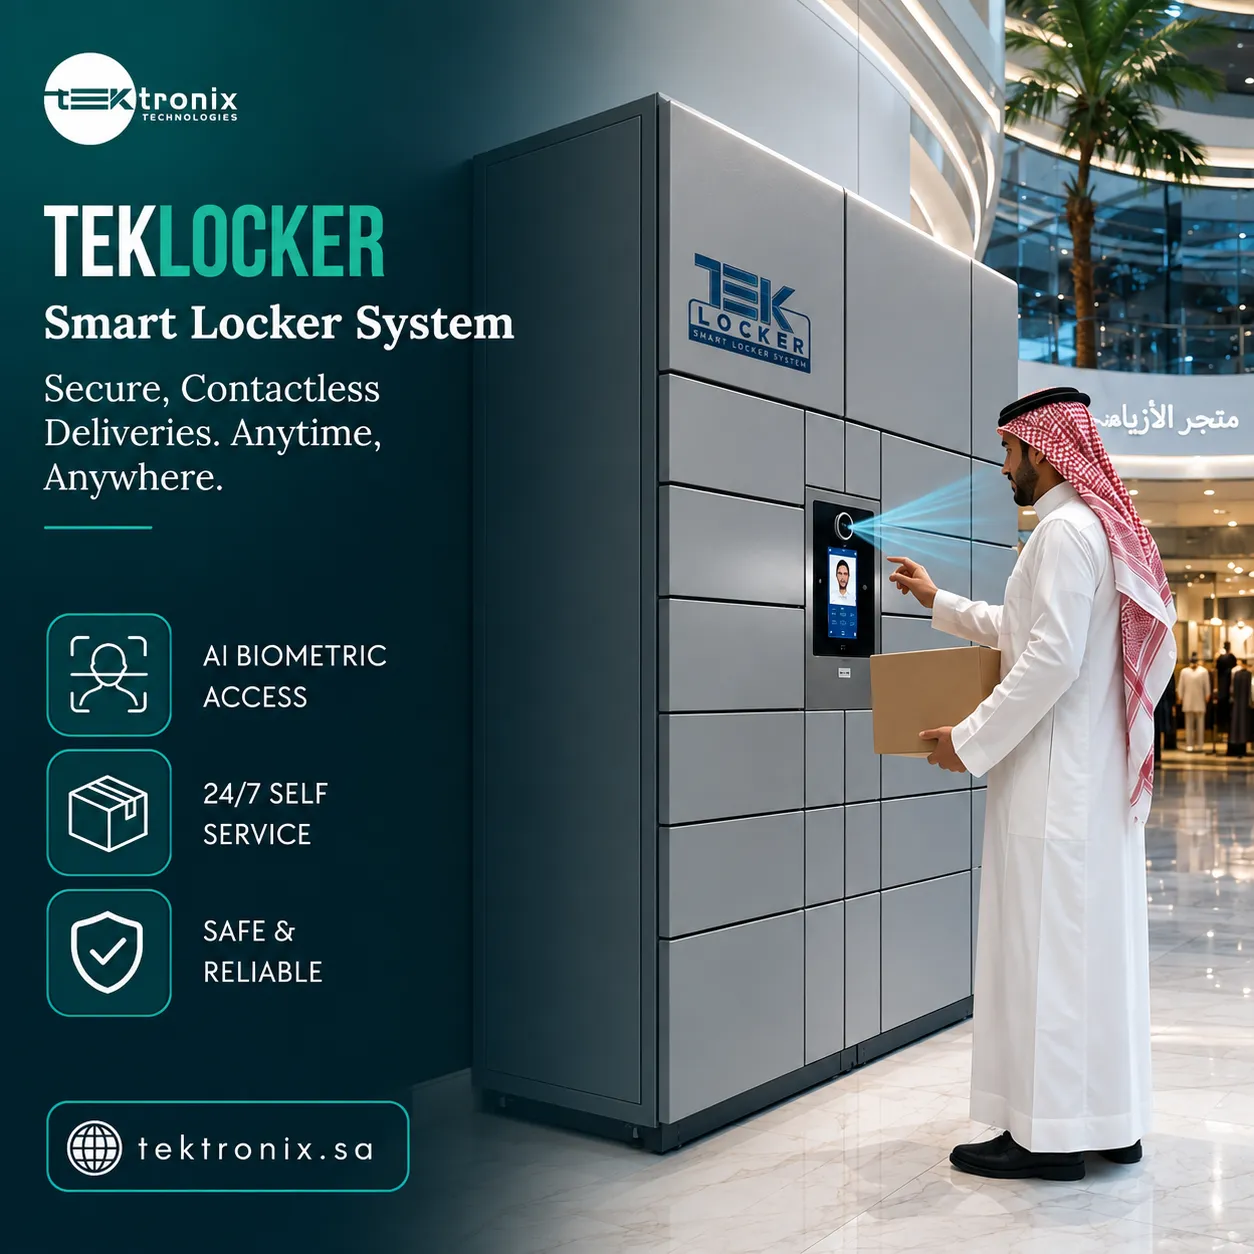

Saudi Arabia's banking sector is undergoing rapid digital transformation, and a modern Smart Locker System is becoming a core part of that shift. Banks across the Kingdom are replacing manual, key-based storage with automated, sensor-driven locker units that protect valuables, documents, and cash trays while reducing staff workload at the counter. This is not a cosmetic upgrade — it is a direct response to rising customer expectations, tighter regulatory oversight from the Saudi Central Bank, and branch operating models built around fewer physical touchpoints and faster self-service. Institutions evaluating this transition can review the complete range of banking locker hardware and control software on Tektronix's dedicated smart locker product page, where specifications, integrations, and deployment options for branches across Riyadh, Jeddah, and the Eastern Province are detailed in full.
What a Modern Locker System Means for Retail and Corporate Banking
At its core, this technology replaces a physical key and a manual logbook with a sealed, sensor-monitored compartment that opens only after verified authentication. Every open, close, and access attempt is timestamped and stored, creating a defensible audit trail that branch managers and compliance officers can pull on demand. For a sector under continuous scrutiny from regulators and auditors, that single capability — a tamper-evident, searchable access record — is often the deciding factor in moving away from legacy metal cabinets.
Beyond compliance, the appeal is operational. Self-service kiosks paired with locker banks let customers deposit or retrieve safe-custody items, sealed cash bags, or loan documents without waiting for a teller to be free. Branch staff are freed from repetitive key-handling tasks and can focus on advisory and sales conversations, which is exactly the branch-of-the-future model most Saudi banking groups are now targeting under their digital transformation roadmaps.
The shift also changes how branch real estate is used. Where a traditional layout dedicated a supervised room to safe-deposit boxes, a compact, wall-mounted or freestanding locker bank can sit in the public lobby without a permanent staff member watching over it, since the audit trail and alarm system take on that supervisory role instead. That frees floor space for advisory desks, digital onboarding stations, or simply a shorter, less congested customer queue — a visible, everyday improvement that customers notice even if they never think about the compliance engineering behind it.
Common Pain Points This Technology Removes
- Lost or duplicated physical keys, and the cost of re-keying an entire cabinet bank
- Manual logbooks that are slow to search and easy to dispute during an audit
- Teller time consumed by routine safe-custody deposits and withdrawals
- No remote visibility into which compartments are occupied, overdue, or flagged
Smart Lockers for Banks: Transforming Branch Operations Across the Kingdom
Smart Lockers for Banks are no longer limited to safe-deposit replacement. Deployed correctly, they touch nearly every physical process inside a branch — from cash logistics to courier hand-offs to internal document custody — and each use case reduces a manual, error-prone step to a logged, automated one.
Key Use Cases in Retail and Corporate Branches
- Safe-custody and valuables storage for retail customers, replacing shared-key deposit boxes
- Cash-in-transit and teller cash-recycling lockers for secure end-of-day reconciliation
- Document drop-off and courier lockers for loan files, cheques, and KYC paperwork
- Staff locker banks for personal items and device custody on the banking floor
Because each of these workflows generates its own compliance requirement, banks typically standardise on one locker network rather than mixing vendors — a single control layer is far easier to audit than three or four disconnected cabinet systems.
Corporate banking teams are also finding uses beyond the retail floor. Relationship managers handling business loan files, trade-finance documents, or collateral paperwork can use a dedicated locker bank to hand off physical files to underwriting or legal teams overnight without a courier trip across the city, with the same access log giving both parties proof of exactly when a file changed hands.
Digital Lockers System: The Technology Powering Next-Generation Bank Branches
A Digital Lockers System is the combination of hardware compartments, an identification layer, and a connected software backend that ties every physical action to a verified digital identity. It is this three-part architecture — not the cabinet itself — that gives banks the reporting and control regulators expect.
Core Components of a Digital Lockers System
- Ruggedized steel compartments with individual electronic locking mechanisms
- A touchscreen or kiosk interface for identity verification and compartment selection
- RFID, PIN, or card-based credential readers for staff and customer authentication
- A cloud or on-premises management console for remote monitoring and reporting
This modular design means a branch can start with a small bank of lockers at a single Riyadh location and scale the same platform network-wide as rollout budgets allow, without re-training staff on a different interface at every stage.
Compartment sizing is another practical detail worth planning early. A branch handling mostly documents and small valuables needs a different mix of slot sizes than one also managing sealed cash bags or larger corporate parcels, and getting this wrong at the design stage usually means a costly hardware swap later. A short site survey before installation — matching expected daily volume and item size to a compartment layout — avoids that rework and keeps the rollout on schedule.
Electronic Locker System Security Standards for Financial Institutions
Banking hardware is judged against a different bar than retail or logistics deployments. A compliant Electronic Locker System for a Saudi financial institution needs encrypted access logs, tamper and forced-entry alarms, redundant power handling, and an architecture that can be aligned with the Saudi Central Bank's cybersecurity framework and the Kingdom's Personal Data Protection Law (PDPL).
Encryption in transit and at rest, role-based administrative permissions, and full event logging are the baseline requirements most compliance teams now specify before a vendor is shortlisted. The security architecture behind Tektronix's locker platform is built around these exact controls, giving IT security and compliance teams a system, they can defend to internal audit and external regulators alike.
Physical hardening matters just as much as the software layer. Reinforced door frames, anti-drill lock housings, and battery-backed operation during a power interruption all reduce the practical attack surface at the branch level, while a secondary offline authentication path ensures staff are never locked out of critical compartments during a network outage — a scenario compliance teams specifically test for before sign-off.
Vendors should also be able to demonstrate a clear incident-response process: what happens, procedurally and technically, if a forced-entry alarm triggers outside branch hours, and how quickly that alert reaches both the branch security team and head-office risk monitoring. This operational detail is often the difference between a system that looks secure on a spec sheet and one that performs under an actual incident.
Face Recognition Locker Access: Biometric Security for Saudi Bank Branches
Card and PIN credentials can be shared, lost, or copied — a limitation banks increasingly want to close at the locker level. Face Recognition Locker Access removes that gap by tying every compartment opening to a live, liveness-checked facial match rather than something a customer or staff member is carrying.
For customers, the experience is contactless and fast: no card to present, no PIN to remember, and no queue while a teller verifies a signature card. For the bank, it produces a stronger, non-transferable audit trail and reduces the operational cost of reissuing lost access cards across a large branch network — an important consideration for institutions scaling locker deployment across dozens of sites in the Kingdom.
Liveness detection is the detail that separates a genuinely secure deployment from a basic camera match: the system needs to distinguish a live person from a photo, video replay, or mask attempt before granting access. Pairing this with a fallback credential — a PIN or staff-issued override — also keeps the branch operational for the rare customer who cannot use facial verification, without weakening the primary security model for everyone else.
Data handling around biometric templates deserves its own scrutiny during vendor selection. Templates should be stored as encrypted mathematical representations rather than raw images, processed in line with PDPL consent requirements, and never shared outside the locker platform's own access-control function — a distinction worth confirming in writing before any biometric rollout begins.
Locker Management Software: Centralized Control and Regulatory Reporting
Locker Management Software is the layer branch operations and compliance teams actually work in day to day. Rather than physically checking cabinets, administrators use a single dashboard to view compartment status across every branch, issue or revoke access remotely, and export audit-ready reports for internal review or a Saudi Central Bank inspection.
Look for a platform that supports multi-branch role hierarchies, automated alerts for prolonged or failed access attempts, and data handling that satisfies PDPL requirements for customer information. Tektronix's locker management console is built to cover exactly this scope, giving head-office teams the same visibility whether a locker bank sits in a Riyadh flagship branch or a smaller regional outlet.
Integration with existing core-banking and identity systems is usually the deciding technical factor at procurement stage. A management platform that can pull staff identities from an existing directory service, or push access events into a bank's own security-information system, saves months of duplicate administration compared with a locker network that operates as an isolated island. It is worth asking any vendor early in the evaluation how their software exposes this data — through an API, scheduled export, or direct integration — rather than assuming compatibility.
Reporting Features Compliance Teams Look For
- Exportable, timestamped access logs filtered by branch, user, or compartment
- Automated alerts for failed access attempts or doors left ajar
- Role-based dashboards separating branch staff, IT administrators, and auditors
- Scheduled compliance reports ready for internal review or regulator request
Smart Locker System KSA: Regulatory Alignment and Vision 2030 Readiness
Deploying a Smart Locker System KSA-wide means designing for a regulatory and strategic environment that is moving fast. Vision 2030's financial-sector digitisation targets are pushing banks toward paperless, self-service branches, while the Saudi Central Bank's ongoing cybersecurity and data-governance updates raise the bar for any system that stores customer records or valuables.
Institutions building branches inside emerging smart-city projects, including developments connected to NEOM, are already specifying locker and access-control hardware that meets these standards from day one rather than retrofitting later. Vendors with existing GCC compliance experience — rather than hardware imported without local regulatory alignment — are best placed to support that timeline.
Procurement teams evaluating a nationwide rollout should also weigh after-sales logistics: spare-part availability, firmware update cycles, and warranty terms that hold up across the Kingdom's geography, not just in a single pilot city. A platform that depends on hardware or engineers based outside the region tends to show longer downtime windows when something does need attention, which matters over the multi-year lifespan a bank typically plans around this kind of infrastructure investment.
Smart Locker System Riyadh: Deployment Across the Capital's Financial Hubs
Riyadh's concentration of head offices, regional banking hubs, and the King Abdullah Financial District (KAFD) makes it the natural starting point for most locker-network rollouts before they extend to Jeddah, Dammam, and other regional centres. A Smart Locker System Riyadh deployment typically anchors the pilot phase, giving compliance and IT teams a controlled environment to validate integrations before wider rollout.
Local installation and support matter here as much as the hardware itself: a Riyadh-based technical team that can respond to a branch on the same business day keeps uptime high and shortens the maintenance cycle that head-office risk teams monitor closely.
Beyond the capital, banks are extending the same platform into Jeddah's commercial districts and the Eastern Province's industrial and financial corridors, where corporate banking volumes create similar demand for secure document and cash-handling infrastructure. Running one consistent locker standard across all three regions — rather than a different vendor per city — is what ultimately lets a bank produce a single, Kingdom-wide compliance report instead of reconciling several incompatible systems at year end.
Why Tektronix Is the Right Partner for Bank Locker Deployment in Saudi Arabia
Tektronix has engineered and deployed physical security and access-control systems across UAE and Saudi banking, government, and enterprise sites, giving the team direct, hands-on experience with the compliance expectations financial institutions in the region operate under. Hardware is engineered to align with ISO-grade security practices, and every deployment includes on-the-ground installation and after-sales support rather than a shipped box and a manual.
Banks evaluating vendors can view the full smart locker product specifications and integration options here before shortlisting a supplier for a pilot branch or a full network rollout.
Conclusion
A Smart Locker System is now a practical requirement for Saudi banks balancing customer convenience with regulatory demands. Smart Lockers for Banks streamline safe-custody, cash, and document workflows, while a well-built Digital Lockers System and a hardened Electronic Locker System give compliance teams the audit trail they need. Face Recognition Locker Access and centralized Locker Management Software add contactless security and remote control across every branch. For any Smart Locker System KSA rollout, starting with a Smart Locker System Riyadh deployment offers a proven, low-risk path to Kingdom-wide scale.
FAQs
1. What makes a locker system suitable for bank branches specifically?
Banking-grade hardware needs encrypted, timestamped access logs, tamper alarms, and reporting that satisfies the Saudi Central Bank and PDPL requirements — features generic storage lockers do not include.
2. How does biometric access improve on card or PIN-based lockers?
A face-recognition credential cannot be shared or lost the way a card or PIN can, producing a stronger and more accurate audit trail for both staff and customer access.
3. Can the management software cover multiple branches from one dashboard?
Yes. A properly built management platform gives head-office teams live status, remote unlock, and audit exports across every branch in the network from a single console.
4. Is this technology aligned with Saudi Central Bank and PDPL requirements?
When built with encrypted access logs, role-based permissions, and compliant data storage, the platform can be aligned with current Saudi Central Bank cybersecurity guidance and PDPL data-handling rules.
5. Where should a bank start when rolling out lockers across Saudi Arabia?
Most institutions pilot in Riyadh — often near the King Abdullah Financial District — before extending the same platform to Jeddah, Dammam, and other regional branches.















Sign in to leave a comment.