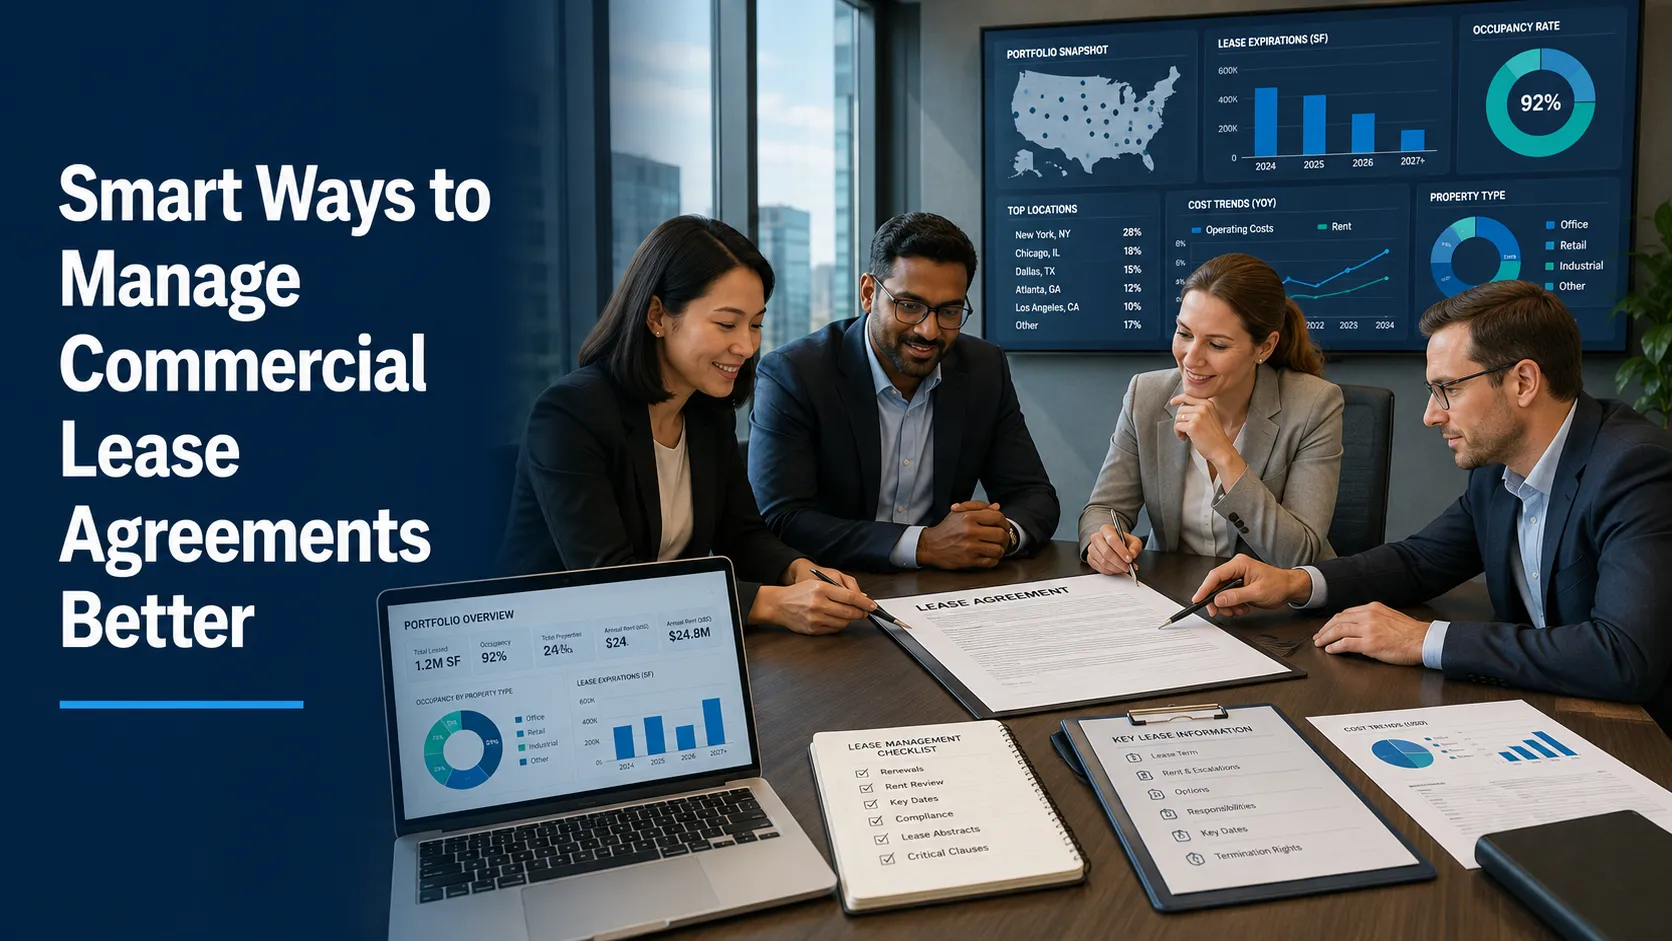

Managing a commercial lease involves much more than paying rent on time. Every agreement contains dates, financial terms, responsibilities, renewal options, and notice periods that can affect a business for years. When those details are stored in different spreadsheets, emails, or folders, simple questions can take time to answer.
A smarter approach is to treat every lease as an active business record. Good lease management keeps information organized, gives teams time to act, and makes it easier to understand the real cost of each location. These habits can help businesses manage commercial lease agreements with greater confidence.
Start With a Clear Lease Summary
Commercial leases can be long and detailed. Teams should not have to read the full document every time they need to check a rent increase, renewal option, or maintenance responsibility.
Creating a clear summary of important terms makes day-to-day management easier. Useful information may include commencement and expiration dates, base rent, rent escalations, renewal options, notice requirements, security deposits, insurance obligations, and responsibilities for repairs or common area costs.
A structured lease administration process helps keep these details connected to the original documents. This gives employees a reliable place to check information while preserving the full agreement for reference.
Track Critical Dates Before They Become Urgent
One of the easiest ways for a lease to become costly is to miss a deadline. Renewal options, termination rights, notice periods, rent reviews, and expiration dates often require action months before the actual event.
Waiting until the last minute limits a business's choices. A rushed renewal may leave little time to compare alternatives or negotiate better terms.
Teams should create reminders well in advance and assign ownership for each important event. Regular reviews give decision-makers time to evaluate the location, involve finance or legal teams, and prepare a plan.
Understand More Than the Base Rent
The monthly rent shown on a lease rarely tells the whole story. Depending on the agreement, a tenant may also be responsible for common area maintenance, property taxes, insurance, utilities, repairs, or other operating expenses.
Different lease structures distribute these costs differently. A gross lease may include many expenses in rent, while a triple net lease can place more responsibility on the tenant. Modified gross and percentage leases can create other combinations.
Teams should document which expenses belong to the landlord and which belong to the tenant. Reviewing actual charges against the lease can help identify unexpected increases or billing errors.
Keep Every Amendment With the Current Lease Record
Commercial leases often change during their lifetime. A business may add space, extend the term, adjust rent, change responsibilities, or negotiate a new option.
Problems occur when the original lease is easy to find but later amendments are stored somewhere else. Someone reviewing only the first agreement may make a decision using outdated information.
Every amendment, side letter, renewal, and related document should be linked to the current lease record. Key terms should also be updated when a change is signed. Keeping a clear history improves accuracy and future reviews.
Connect Real Estate and Finance Information
Lease decisions have direct financial consequences. Rent changes affect budgets, amendments may affect future obligations, and certain lease events can require accounting updates.
A strong process keeps real estate and finance teams working from the same current information. For organizations with reporting requirements, lease accounting also depends on accurate lease terms, payment schedules, and modifications.
Regular communication between these teams can prevent situations where an operational change is known by one department but missing from financial records. That alignment becomes more important as the number of locations grows.
Create a Consistent Renewal Review Process
Renewals should not be treated as automatic decisions. Before exercising an option or negotiating an extension, businesses should review how the location is performing and whether it still supports current plans.
Useful questions include whether the space still fits the team, how occupancy costs compare with other locations, whether market rent has changed, and whether the business expects to grow or reduce its footprint.
If the company is considering alternatives, a structured deal management process can help organize site comparisons, proposals, negotiations, approvals, and documents. This allows the renewal decision to be compared with other realistic options.
Assign Clear Responsibilities Across the Team
Lease management often involves several people. Real estate may handle landlord communication, finance may manage payments, legal may review amendments, and operations may handle location-specific obligations. Without clear ownership, tasks can easily be assumed rather than completed.
Each major responsibility should have an owner, including critical dates, document updates, payment reviews, renewal planning, and landlord requests. This is especially useful for real estate teams managing multiple properties and coordinating with other departments. Clear ownership also makes employee transitions easier.
Review the Portfolio, Not Just Individual Leases
A lease may look reasonable on its own but appear expensive or restrictive when compared with the rest of the portfolio.
Regular portfolio reviews can reveal useful patterns. Teams may identify locations with unusually high operating expenses, clusters of upcoming expirations, inconsistent lease terms, or opportunities to consolidate space.
Looking across the full portfolio also supports better budgeting and long-term planning. Instead of reacting to one lease at a time, the business can prepare for several upcoming decisions together.
Make Lease Management an Ongoing Process
Commercial lease agreements should not disappear into a folder after they are signed. They continue to affect costs, operations, reporting, and future real estate decisions throughout their term.
The best approach is simple: keep terms organized, monitor deadlines early, track costs, update records after changes, and make responsibilities clear across teams.
When these habits become part of normal operations, businesses spend less time searching for information or responding to unexpected lease issues. They gain better visibility into their commitments and more time to make thoughtful decisions about renewals, expenses, and future locations.





















Sign in to leave a comment.