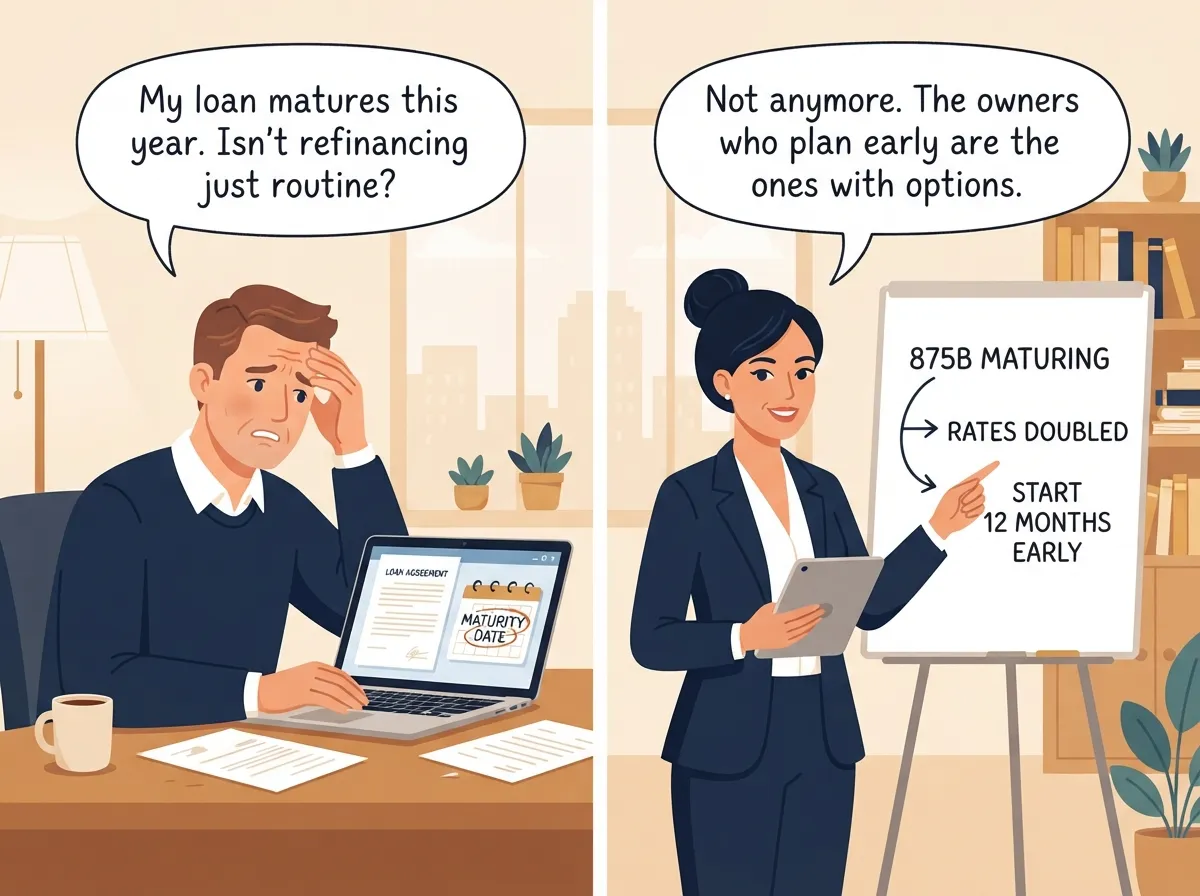
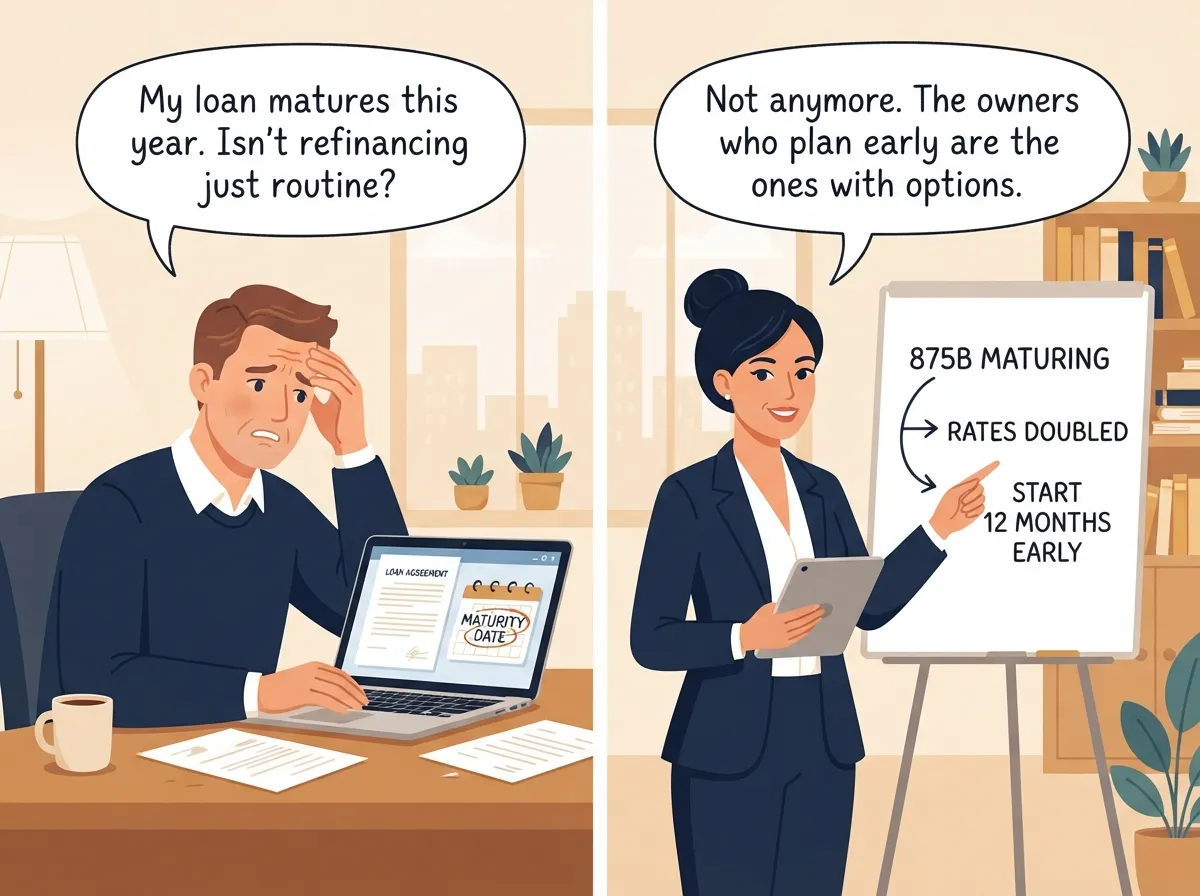
Commercial property owners spent years borrowing at rates that felt almost too good to be true. Now the bill is coming due, literally. An enormous wave of commercial mortgages taken out between 2018 and 2022 is reaching maturity in 2026, and the refinancing environment waiting on the other side looks nothing like the one borrowers left.
What Is the Maturity Wall, and Why 2026 Is Different
The maturity wall describes what happens when a huge volume of loans comes due at the same time, in a market where credit conditions have shifted dramatically since origination. According to the Mortgage Bankers Association, roughly 875 billion dollars in commercial and multifamily mortgage debt is scheduled to mature in 2026 alone, about 17 percent of all outstanding CRE loans nationwide.
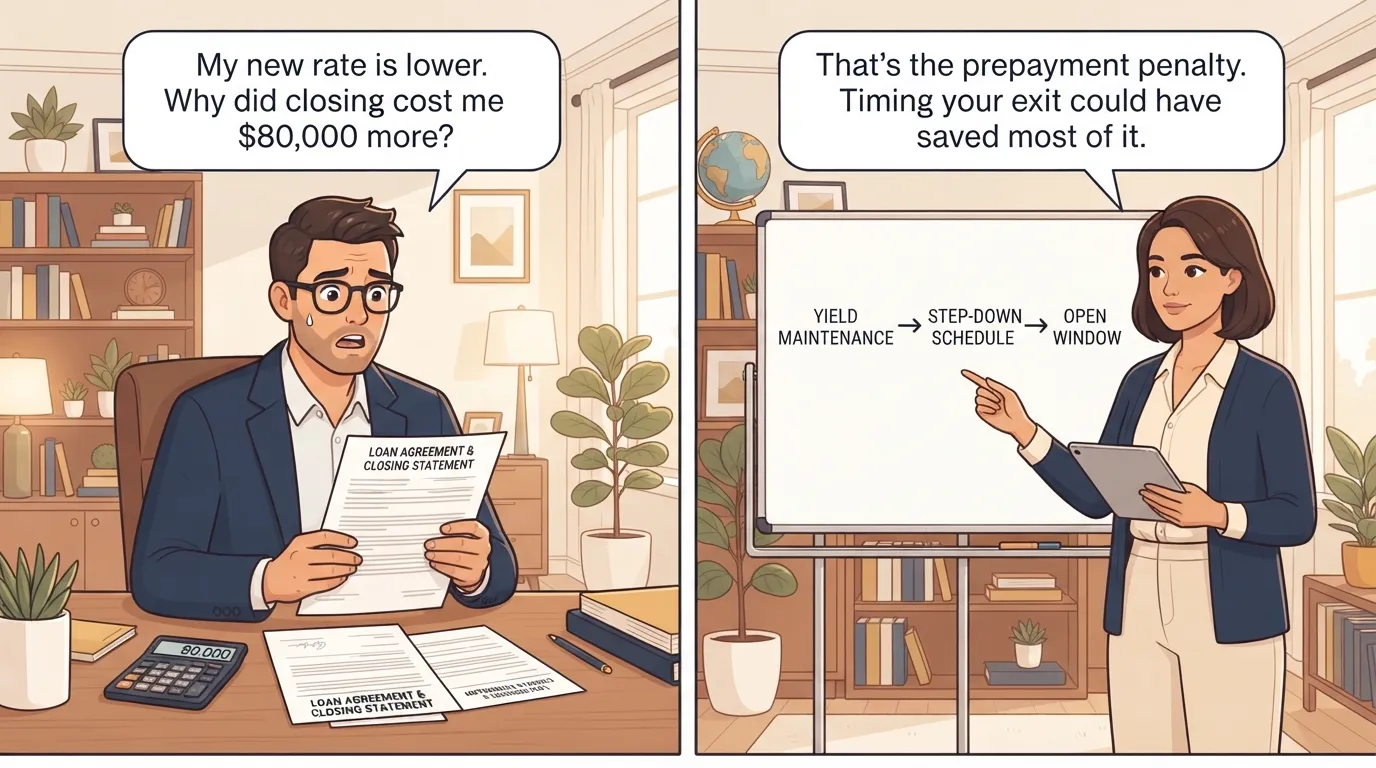
What makes this wave different from past refinancing cycles is the rate gap. Many of these loans were originated at 3 to 4 percent. Refinancing today often lands closer to 6 or 7 percent. That is not a minor adjustment, it is enough to turn a property that comfortably covered its debt service in 2021 into one that barely breaks even, or worse, in 2026.
Which Property Types Are Under the Most Pressure
Not every asset class is feeling this equally. Some sectors are absorbing a disproportionate share of the maturities, while others are dealing with a different kind of structural risk entirely.
Multifamily's Outsized Share of the Wall
Multifamily properties account for the single largest slice of loans maturing through 2026, roughly a third of all commercial loan maturities across every asset class. That concentration means multifamily owners are navigating a uniquely crowded refinancing market, competing for lender attention and capital against thousands of similar properties hitting maturity in the same narrow window. For owners in this specific position, Multifamily Lender's detailed action plan for multifamily maturity wall help breaks down the exact loan audit steps, refinancing options, and restructuring paths built specifically around that segment of the market.
Office and Hospitality Face a Different Kind of Risk
Office and hospitality assets carry their own complications. Office properties are dealing with occupancy questions layered on top of financing pressure, while hospitality assets face nightly revenue exposure that makes any sign of financial strain ripple into operations almost immediately. Both sectors tend to see lenders apply more conservative underwriting than they would for a stabilized multifamily property with predictable rent rolls.
Why Traditional Refinancing Is Getting Harder
Beyond the rate gap, higher rates have also pushed cap rates up, which pushes property valuations down. A property that appraised comfortably in 2021 may come in significantly lower today, which means a new loan is often smaller, more expensive, and based on a diminished asset value all at once. That combination is exactly why so many owners who assumed refinancing would be routine are finding it anything but.
Banks have also grown more selective across the board, not just in one property type. Many are demanding larger reserves, lower leverage, and cleaner financials before they will even engage, timelines that don't always match an owner's actual maturity date.
The Playbook Owners Are Using to Get Ahead of It
The owners navigating this wave successfully share a common pattern, they start early. A loan audit conducted 12 months before maturity, covering DSCR, current appraisal value, and extension options, gives an owner real leverage to shop multiple financing paths instead of scrambling for whatever a single lender offers at the last minute.
Bridge loans have become a common tool for buying time on transitional or underperforming assets, while DSCR loans continue to serve as a strong permanent exit for properties with stabilized, cash-flowing income. For owners whose numbers simply don't support a straight refinance, restructuring tools like loan modifications, preferred equity, or note sales are increasingly viable alternatives to a forced sale.
The Bottom Line
The 2026 maturity wall is a real and well-documented challenge, but it is not a uniform one. An office building, a hotel, and a multifamily property are all facing this wave from different starting points, with different tools available to them. What matters most across every asset class is the same, owners who treat their maturity date as a planning deadline rather than a countdown clock tend to come out the other side with far more options than those who wait.
Working with an advisor who understands both the broader market conditions and the specific dynamics of your property type is often the difference between a stressful scramble and a controlled transition into better terms.











Sign in to leave a comment.