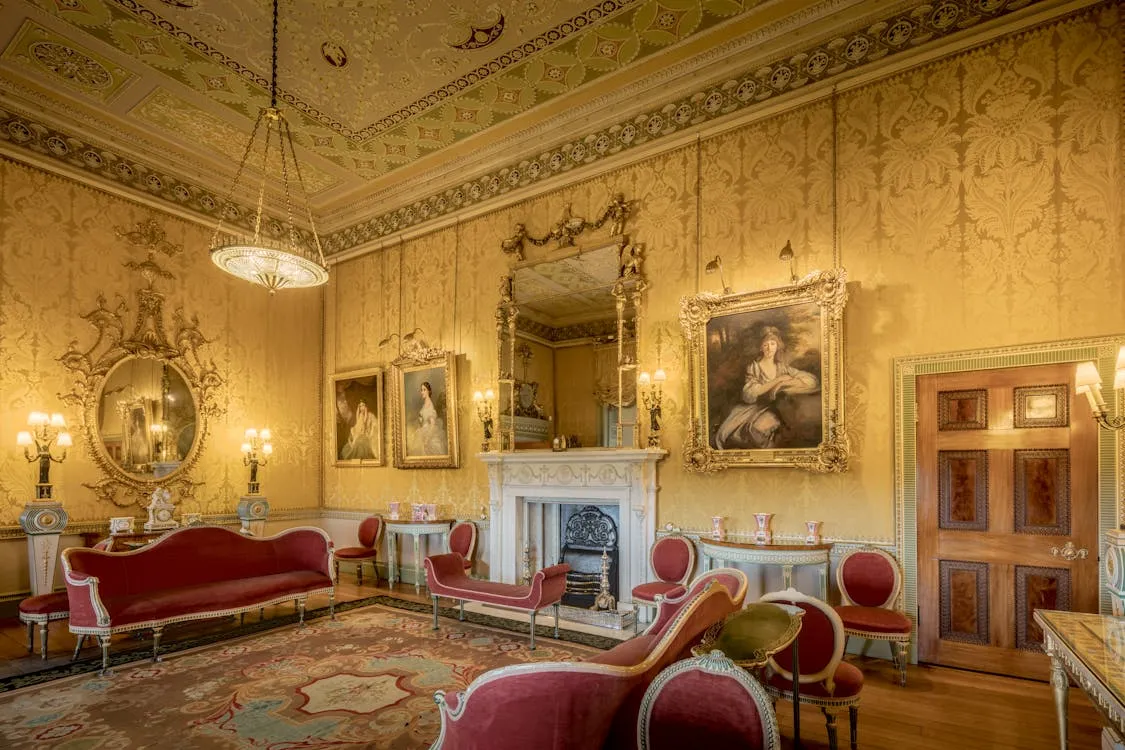


Fine art, jewelry, rare collectibles, and other passion assets are among the most consequential items an executor will encounter during estate administration, and among the most mishandled. Unlike liquid financial holdings, these assets require immediate physical attention, specialist valuation, and careful documentation that goes far beyond a general household inventory. Executors who treat passion assets as afterthoughts expose themselves to fiduciary liability and the estate to significant financial and legal risk. For fiduciaries in Texas, engaging a qualified estate art appraisal in Houston is one of the most protective steps they can take.
This checklist is designed for legal and financial professionals navigating estates with substantial art or collectibles. It is not a substitute for legal counsel, but it maps the key steps that too many fiduciaries learn the hard way.
Step 1: Secure Physical Custody Immediately
The moment a fiduciary assumes office, the physical security of all assets becomes their responsibility. According to the American Bar Association's Guidelines for Individual Executors and Trustees, it is crucial to secure and value all assets as soon as possible after death. For art and collectibles, this means confirming the location of every significant piece, ensuring works on loan to galleries or institutions are formally recalled or placed under documented custody arrangements, and verifying that climate-controlled storage is in place for works not on display.
Any works stored in a primary residence that will sit vacant should be moved to professional art storage immediately. Theft, damage from environmental fluctuations, and accidental loss during estate proceedings are all real risks that the fiduciary is responsible for preventing.
Step 2: Conduct an Emergency Insurance Review
Before any appraisal is complete, review the decedent's existing insurance policies. Many high-value collections are covered under fine art floaters or scheduled personal property riders, but coverage amounts are often based on outdated valuations. If a painting appraised at $80,000 five years ago is now worth $300,000 and the estate suffers a loss before a current appraisal is obtained, the gap is unrecoverable.
Contact the insurer immediately to notify them of the death, confirm current coverage levels, and request a temporary extension or supplemental coverage while formal appraisals are being arranged. Document every communication.
Step 3: Engage an Accredited, USPAP-Compliant Appraiser
This is the step with the most legal and financial consequences. Under IRS regulations, as detailed in the ABA's overview of art and estate planning, an appraisal is required for art valued at $3,000 or more per item, or $10,000 or more for an aggregate collection on Form 706, with an executor certification signed under penalty of perjury.
The appraiser must meet the IRS definition of a qualified appraiser and comply with USPAP standards. A general appraiser or dealer opinion will not satisfy these requirements.
Step 4: Establish the Stepped-Up Basis
Without a formal appraisal at the date of death, heirs have no documented fair market value and no established basis from which to calculate gain or loss on future sale. As the ABA notes, the absence of an appraisal removes the possibility of a stepped-up basis entirely, which can result in substantially higher capital gains tax liability when beneficiaries eventually dispose of inherited works.

Step 5: Document Provenance and Condition
A valuation without provenance documentation is an incomplete record. The estate file should include acquisition records, exhibition history, prior appraisals, condition reports, bills of sale, and any reproduction or licensing rights. Appraisal services for high-value art collections conducted by a specialist will incorporate this research, but the executor should actively gather all available documentation to support it.
Step 6: Plan the Disposition Strategically
Once valuation and documentation are complete, disposition options include distribution to beneficiaries, charitable donation, private sale through fine art brokerage services, or auction. Each path carries different tax, timing, and legal implications, requiring coordination between the estate attorney, tax counsel, and art advisor. Art collection management services during administration ensure works are properly maintained and insured while those decisions are made.

A Note on Fiduciary Liability
Executors who fail to properly inventory, value, and report personal assets face personal liability. Underreporting is treated as fraud. The cost of engaging an accredited art appraiser is a legitimate administration expense and far smaller than the consequences of getting it wrong. Engage specialist counsel early. The documentation produced protects the estate, the beneficiaries, and the fiduciary.
Executors and estate attorneys managing significant art holdings will find a trusted resource in CHASE Art Advisory & Valuation. The firm provides estate art appraisal in Houston, TX, for legal professionals and fiduciaries across the full spectrum of estate administration. Reach out to them to learn more.
About the Author
Cameron Rhodes is an estate planning attorney and fiduciary consultant with over twenty years of experience advising executors, trustees, and personal representatives on complex estate administration. Cameron writes regularly for legal and financial publications on fiduciary best practices and the management of non-traditional asset classes.




















Sign in to leave a comment.