Conventional 30-year mortgage rates are stabilizing around 6.9% in 2026, while Islamic mortgage profit rates are running 6.2% to 7.1%, according to recent industry analysis. That narrow band matters more than it looks. For the first time since 2021, Musharakah-based home financing isn't just the ethically preferable option for Muslim families avoiding interest, it's genuinely price-competitive with a conventional mortgage, removing what used to be the single biggest objection families raised before choosing it.
That shift changes the actual decision families are making. For years, choosing Musharakah meant accepting a real financial tradeoff in exchange for religious compliance. In 2026, for many buyers, that tradeoff has largely disappeared, which means the remaining differences between the two structures, not the price, are what actually deserve scrutiny before signing anything.
Why "Avoiding Interest" Was Never the Whole Story
Musharakah, a diminishing partnership structure where the financier and buyer jointly own a property and the buyer's ownership share grows with each payment, gets talked about almost exclusively through the lens of Riba avoidance. That's the foundational principle, but it's not the only structural difference that matters to a family actually comparing their options.
The deeper distinction is about who bears risk. In a conventional mortgage, the lender is owed a fixed payment regardless of what happens to the property or the borrower's circumstances, the debt exists independently of the asset's performance. In Musharakah, the financier is a genuine co-owner, which means the structure treats the transaction as a shared position in a real asset, not a claim against the borrower's income.
Three Places the Structures Actually Diverge
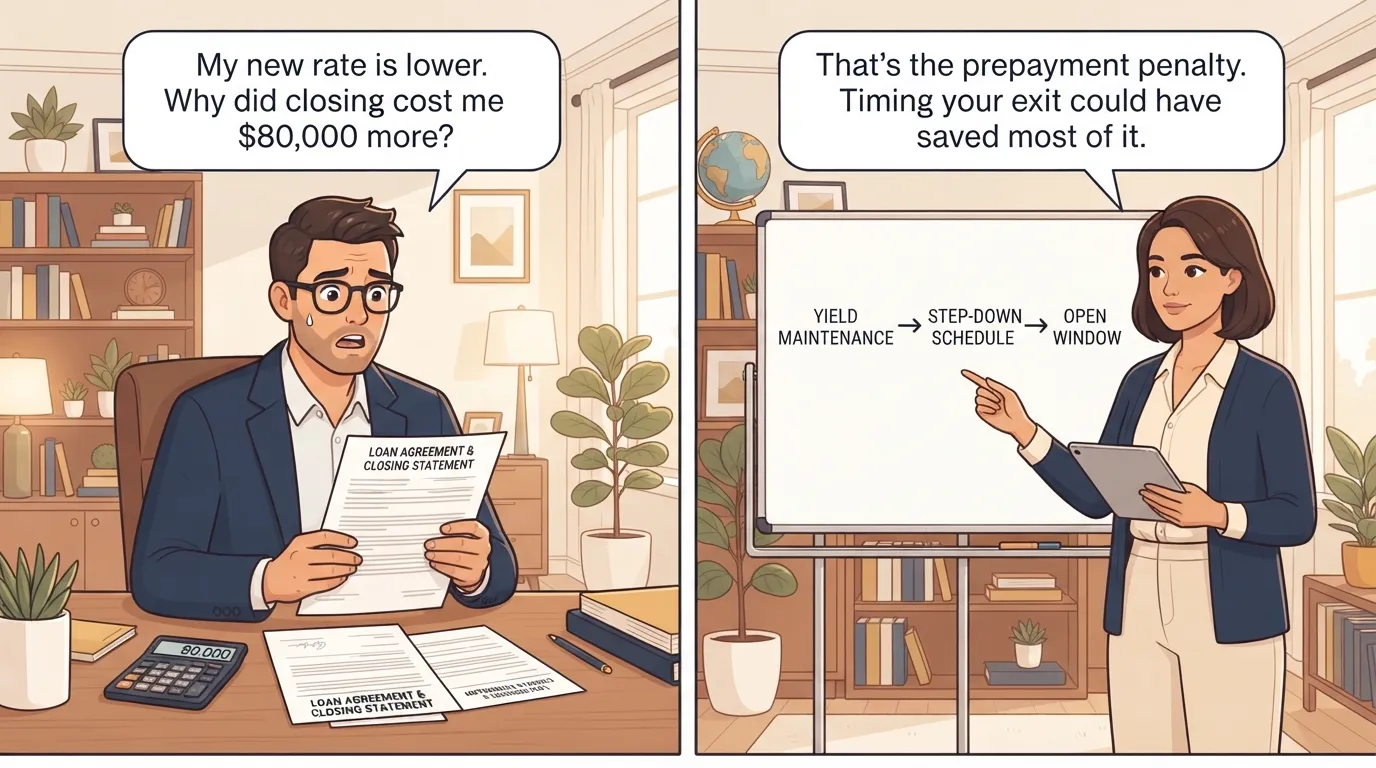
1. Prepayment treatment. Conventional mortgages frequently carry prepayment penalties designed to protect the lender's expected interest income over the life of the loan. Musharakah structures, since profit comes from a portion of ownership rather than an interest schedule, generally don't penalize early payoff, and in most structures actively encourage the buyer to increase their equity share faster, since that directly reduces the financier's remaining position.
2. Default and hardship handling. A conventional mortgage in default accrues late fees and additional interest, mechanisms explicitly built to compensate the lender for risk. Musharakah providers typically charge a flat administrative fee for late payments rather than compounding interest, since charging interest on a missed payment would itself violate the same principle the entire structure is built around.
3. Tax treatment in the US. The "rent" portion of a Musharakah payment, the amount covering the financier's remaining ownership share, is generally recognized by the IRS as qualified residence interest for deduction purposes, meaning it remains itemizable in most cases despite not being interest in the conventional sense. That detail surprises a lot of first-time buyers who assume choosing a halal structure means giving up a tax benefit conventional borrowers keep.
What Changed to Make the Pricing Gap Close
Two forces converged to bring Islamic mortgage pricing into genuine competitive range this year. The Federal Reserve's SOFR benchmark, which most Islamic profit rates are tied to, has stabilized, making pricing more predictable for providers structuring these deals. At the same time, conventional rates themselves have settled into a higher band than the ultra-low environment of the early 2020s, narrowing the gap that used to make Musharakah a meaningfully more expensive choice.
There's also been real growth on the supply side. As of 2024, more than 25 U.S. banks and institutions offered halal mortgage products, according to reporting from Fast Company, a dramatic expansion from a market where, until 1997, no U.S. financial institution offered this kind of financing at all. More providers competing for the same pool of buyers has done what competition usually does to pricing.
What This Means for a Family Comparing Options Today
The families evaluating home financing in 2026 are increasingly finding that the decision isn't really about accepting a financial penalty for religious compliance anymore. It's a genuine structural comparison, prepayment flexibility, default handling, and long-term ownership mechanics, layered on top of pricing that no longer requires a meaningful concession.
We've laid out a full side-by-side breakdown of how Musharakah home financing compares to a conventional mortgage, covering the exact payment mechanics, ownership transfer schedule, and what happens in a default scenario under each structure, worth reading in full for anyone weighing this decision with real numbers in front of them.
The Bottom Line
A rate environment where Islamic mortgage pricing sits within a point of conventional financing is a genuinely new moment for Muslim homebuyers in America. For years, the honest conversation about Musharakah financing included a real cost tradeoff alongside the ethical case for it. In 2026, that tradeoff has largely closed, which means the choice increasingly comes down to which ownership structure a family actually wants, not which one they're willing to pay more for.











Sign in to leave a comment.