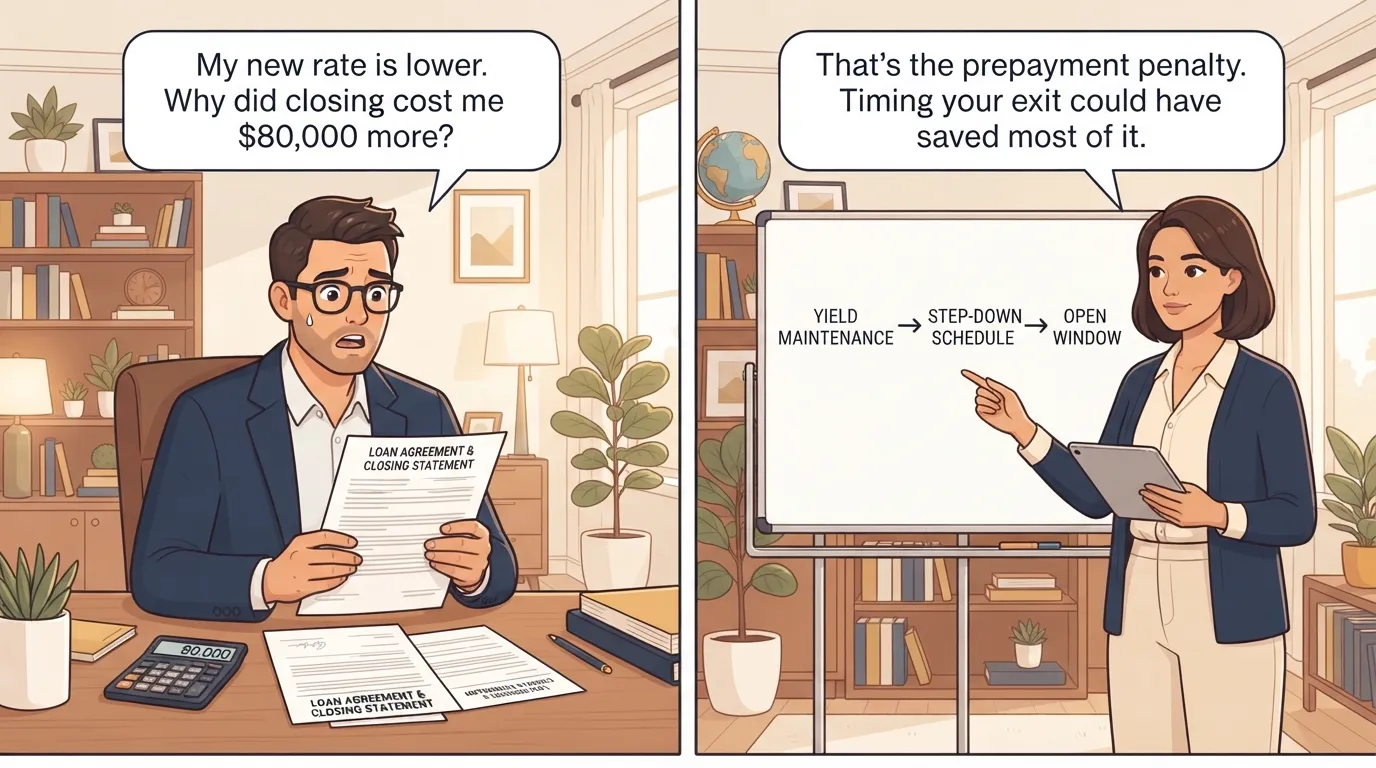
Owners racing to refinance ahead of the 2026 maturity wave tend to focus on one number, the new interest rate. Fewer stop to calculate what it costs to exit the old loan in the first place, and that oversight is turning otherwise smart refinancing decisions into expensive surprises.
Why Prepayment Penalties Catch Owners Off Guard
Most commercial borrowers sign their original loan documents years before they ever think seriously about paying the loan off early. The prepayment terms buried in that paperwork rarely get a second look until a refinance or sale is already in motion, and by then the penalty structure is locked in regardless of how the broader market has shifted.
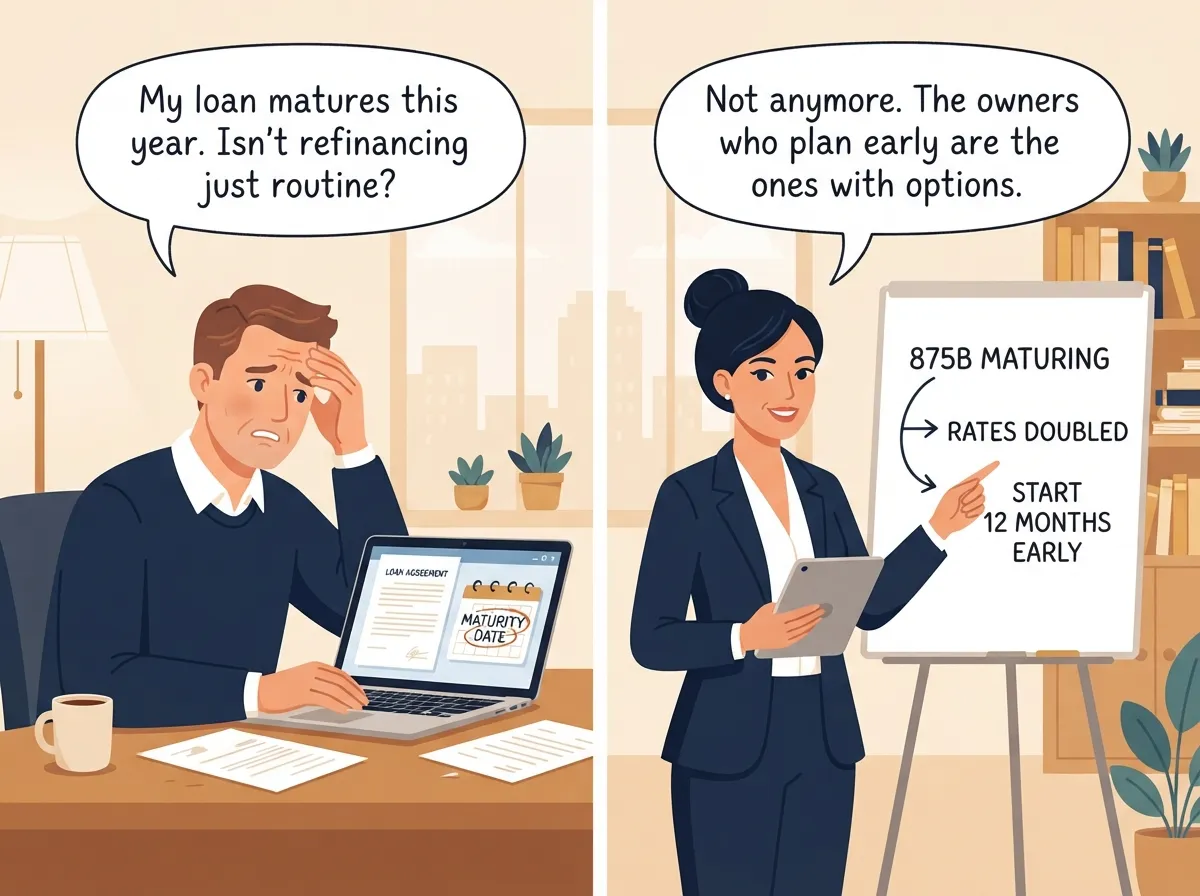
That gap in attention matters more in 2026 than in a typical year. With such a large share of commercial mortgages hitting maturity simultaneously, owners are moving faster than usual to lock in new terms, and speed is exactly when a five- or six-figure penalty gets missed until it shows up on the closing statement.
The Three Penalty Structures You're Likely to Encounter
Not all prepayment penalties work the same way, and the structure attached to a loan determines both the cost and the strategy for minimizing it.
Yield Maintenance: The Most Expensive Trap
Yield maintenance penalties compare the interest payments a lender would have collected over the loan's remaining term to what they can currently earn reinvesting in comparable Treasury securities. The counterintuitive part is that this penalty gets more expensive when rates fall, not when they rise, because a lower reinvestment rate widens the gap the borrower has to cover. An owner who assumes today's higher-rate environment protects them from a steep penalty may be in for an unpleasant recalculation.
Defeasance: A Different Kind of Complexity
CMBS loans commonly use defeasance instead, which requires the borrower to replace the real estate collateral with a portfolio of Treasury securities structured to replicate the lender's remaining cash flows. It is not simply a fee, it is a legal and financial substitution process that typically requires outside defeasance consultants, legal counsel, and several weeks of lead time. Owners often underestimate both the cost and the timeline this adds to a payoff.
Step-Down Schedules and Open Payoff Windows
Not every loan carries the harsher yield maintenance or defeasance structures. Many commercial loans use a simpler step-down schedule instead, where the penalty percentage declines on a fixed timeline, often something like 5 percent in year one, dropping a point each year until it disappears entirely. Some loans also include a short open payoff window near maturity where no penalty applies at all.
The practical takeaway is straightforward, an owner who knows exactly where their loan sits on that schedule can often time a sale or refinance to land inside a lower-fee year, or inside the penalty-free window, rather than paying full freight simply because the maturity date arrived first.
How to Time Your Exit Around the Fee Structure
The owners who avoid the worst of this outcome tend to do one thing early, they pull their original loan documents and identify the exact penalty structure months before they start shopping for new financing. That single step determines whether a refinance six months early saves money or costs more than simply waiting.
From there, the calculation becomes straightforward. Compare the penalty cost under the current structure against the rate improvement or equity access a new loan would provide. In some cases the math favors an immediate move despite the fee. In others, waiting two or three months for a step-down threshold or an open window saves far more than any rate difference would.
The Bigger Picture: Penalty Cost Is Just One Piece
Prepayment penalties are a real cost, but they are only one variable in a much larger exit decision that also includes property valuation, current occupancy, and which financing path, refinance, bridge, restructuring, or sale, actually fits the property's condition. Understanding the penalty structure simply ensures that whichever path an owner chooses, they are not losing tens of thousands of dollars to a fee they never needed to pay in full.
Commercial Lending USA's broader guide on the 10 best commercial mortgage exit options for 2026 walks through the full range of strategies, from traditional refinancing to sale-leasebacks to government-backed loans, along with a 12-month planning timeline for owners weighing which path fits their specific property.
Reviewing loan documents is not the most exciting part of managing commercial real estate, but in 2026's maturity environment, it may be the single cheapest hour an owner spends all year. According to the Commercial Real Estate Finance Council, understanding a loan's defeasance or yield maintenance terms well ahead of maturity remains one of the most overlooked steps in the refinancing process, and one of the most costly to skip.







Sign in to leave a comment.