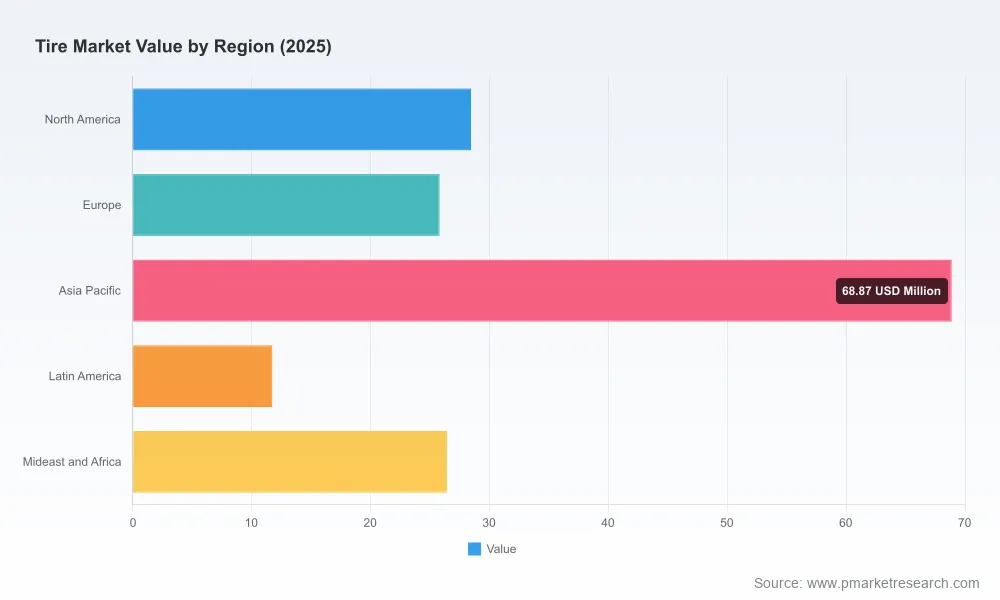

Navigating the Tire Market: Strategic Trends & Commercial Opportunities Through 2032
1. Market Landscape: Growth Trajectory Amid Structural Headwinds
The global tire market is entering a phase of measured but steady expansion, growing from USD 131.82 billion in 2020 to a projected USD 161.28 billion by 2025, with momentum continuing toward USD 215.0 billion by 2032. This trajectory reflects a compound annual growth rate of 4.2 percent across the forecast horizon, underscoring a sector that is advancing not through explosive surges, but through consistent demand absorption, product evolution, and regional rebalancing. The baseline year of 2025 serves as a critical inflection point, capturing a market that has moved past post-pandemic normalization and is now recalibrating around technological shifts, regulatory pressures, and evolving end-use requirements.
Despite the upward revenue path, the industry is navigating a set of structural challenges that demand strategic attention. First, margin compression is intensifying as input cost volatility collides with competitive pricing dynamics. Raw material fluctuations, coupled with shifting freight and energy expenses, have made cost predictability increasingly elusive for both manufacturers and downstream buyers. Second, the regulatory environment is fragmenting across key markets, creating compliance complexity and altering competitive advantages tied to geographic footprint. Third, demand patterns are bifurcating: replacement volume remains a reliable revenue anchor, while original equipment placements are growing at a different pace, shaped by vehicle mix transitions and manufacturer procurement strategies. These forces are not isolated; they interact in ways that reward agility and penalize rigid operational models.
Understanding this landscape requires looking beyond headline growth figures. The market’s resilience stems from its dual-channel structure and the continuous replacement cycle, but the next phase of expansion will be defined by how effectively participants manage cost variability, align product portfolios with shifting performance expectations, and respond to policy-driven trade realignments. The companies that treat these headwinds as design constraints rather than external disruptions will be best positioned to convert market growth into durable profitability.
2. Key Drivers Shaping the Next Horizon
Technological Innovation and Product Differentiation
Product development is no longer a supporting function; it has become a primary lever for competitive positioning. Recent product introductions highlight how manufacturers are engineering tires around specific use cases rather than pursuing broad-spectrum upgrades. Enhanced tread architectures, optimized compound formulations, and targeted durability improvements reflect a market that increasingly values performance consistency across varied driving conditions. For electric vehicles, the emphasis has shifted toward load-bearing capacity, noise reduction, and rolling resistance optimization, signaling a maturing understanding of how tire characteristics interact with vehicle dynamics. This trajectory suggests that future revenue gains will be captured by players who can match technical refinement with clear application storytelling, rather than those who simply expand SKU counts.
Policy and Regulatory Realignment
Trade and compliance frameworks are actively reshaping sourcing logic and competitive exposure. Tariff reviews, periodic exclusions, and sector-specific trade actions have reintroduced uncertainty into cross-border supply planning. For tire market participants, this means that geographic concentration of production and procurement must be evaluated not only on cost and capacity, but also on policy resilience. Regulatory shifts also influence consumer-facing and commercial adoption by changing total ownership economics, particularly where energy efficiency, durability standards, and sourcing expectations intersect. The direction of travel points toward greater regionalization of supply chains and a stronger premium on compliance visibility, as buyers seek to reduce exposure to sudden trade policy adjustments.
Demand-Side Shifts in Consumer and Commercial Behavior
Buyers are making purchasing decisions with a wider set of criteria than in previous cycles. In the replacement channel, longevity, all-weather reliability, and total cost of ownership are gaining relevance over lowest upfront price. Fleet operators and commercial buyers are similarly weighing fuel efficiency, maintenance intervals, and uptime implications more heavily. At the same time, vehicle electrification and evolving SUV and light truck preferences are altering the performance profile demanded from tires. These changes are creating pockets of differentiated demand where specialized product lines can command stronger positioning, while commoditized segments face continued pressure on price and specification parity.
Specialty Tire Market
Supply Chain and Input Cost Dynamics
Cost structure volatility remains one of the most direct influences on margin outcomes. Natural rubber, for example, moved from USD 2.03 per kilogram in November 2025 to USD 2.39 per kilogram by March 2026, a 17.7 percent increase, following a temporary decline earlier in the year. Such swings illustrate how quickly procurement assumptions can be tested. Beyond raw materials, energy costs, logistics constraints, and capacity scheduling continue to affect production economics. The practical implication is that resilience is increasingly built through supplier diversification, forward contracting discipline, and inventory strategies that balance responsiveness against carrying costs. Companies that treat input volatility as a recurring operational variable, rather than an episodic disruption, are better equipped to protect margins without sacrificing product availability.
Winter Tire Market
3. Competitive Dynamics and Leadership Strategies
The market’s competitive structure reflects both entrenched incumbency and continuous portfolio evolution. A concentrated group of major manufacturers commands a significant share of revenue, with the top three participants representing approximately 47.0 percent of the market and the top five reaching 62.5 percent. This concentration does not imply a static hierarchy, however. Differentiated advantage is being built through application focus, technology roadmaps, and manufacturing footprint decisions rather than scale alone.
Strategic Positioning of Leading Players
Several firms illustrate how distinct positioning can translate into market relevance. Michelin continues to advance premium passenger, SUV, and electric vehicle offerings while emphasizing sustainable materials and performance range expansion. Recent launches have centered on fuel savings, extended lifespan, and reduced environmental impact, reinforcing a strategy that ties product performance to operating economics. Bridgestone remains focused on premium passenger, truck, and specialty segments, with recent introductions targeting enhanced driving experience and performance versatility. Continental emphasizes ultra-high performance and all-season solutions across passenger and commercial applications, leveraging engineering credibility in varied conditions. Goodyear has pushed into new all-terrain options with models designed for rugged versatility across conventional and electric vehicles, broadening its application reach. Pirelli has concentrated on high-performance and premium vehicle fitment, updating its performance lineup with newer-generation technology. Sumitomo Rubber Industries, Yokohama Rubber, Hankook Tire & Technology, and Toyo Tire each contribute differentiated portfolios spanning premium, all-terrain, and all-weather segments, demonstrating that competitive depth exists across multiple brand identities and regional strengths.
Market Evolution: Integration, Fragmentation, and New Entry Pressure
The competitive landscape is evolving along two simultaneous paths. On one side, scale advantages, shared technology platforms, and procurement leverage continue to support consolidation benefits among large manufacturers. On the other side, application specialization and regional demand variations are creating fragmentation where focused product lines can outperform broader but less targeted portfolios. New entry pressure is less about mass-market displacement and more about niche relevance: manufacturers that can deliver clear performance differentiation for specific vehicle classes, climate conditions, or commercial use cases are finding room to gain share without requiring dominant scale. This environment rewards companies that can balance portfolio breadth with disciplined segmentation, and that can invest in differentiated technology without inflating complexity across every product line.
4. Forward Outlook: Trends Defining the 2026-2032 Window
Trend One: Application-Specific Engineering as a Growth Multiplier
Over the next three to five years, tire value creation will increasingly depend on how well products are engineered for defined applications rather than positioned as general-purpose solutions. The combination of electric vehicle growth, changing light truck and SUV usage patterns, and commercial uptime requirements is pushing demand toward tires with tailored load, wear, noise, and traction characteristics. This trend creates opportunities for manufacturers to build stronger pricing power in specialized segments and for buyers to reduce lifecycle costs through better specification matching. The risk lies in over-indexing on narrow niches without sufficient volume scale, or in misreading adoption speed for new vehicle platforms.
Trend Two: Trade Policy and Regional Sourcing as Strategic Variables
Trade actions and tariff reviews are likely to remain recurring factors rather than one-time events. Ongoing reviews of passenger vehicle and light truck tire tariffs, alongside broader import measures, will continue to influence sourcing decisions, manufacturing placement, and competitive cost structures. Companies with flexible distribution networks and diversified production footprints will have an advantage in adapting to policy shifts. For investors and procurement leaders, the key opportunity is to treat regional sourcing resilience as a value driver, not just a risk mitigation exercise. The uncertainty to monitor is the pace and scope of future trade adjustments, which can alter cost assumptions faster than internal planning cycles.
Trend Three: Input Cost Discipline and Value-Based Commercialization
As raw material prices and energy costs remain subject to volatility, margin management will depend on a combination of procurement discipline and commercial strategy. The recurring pattern of input price swings, including the 14 percent decline in April and May 2025 followed by recovery to USD 2.39 per kilogram by March 2026, reinforces the need for dynamic hedging, multi-source sourcing, and pricing strategies tied to value delivery rather than cost pass-through alone. Manufacturers that can communicate performance, durability, and total cost benefits more effectively will be better positioned to protect margins. Buyers, in turn, can capture value by aligning procurement with lifecycle performance rather than transactional price points. The main risk is complacency in cost planning, which can leave organizations exposed when volatility returns after short-lived relief periods.
5. Strategic Actions for Decision Makers
For manufacturers: Prioritize application-led product development and protect margins through procurement flexibility rather than fixed cost assumptions. Invest in differentiated performance attributes that map clearly to defined use cases, especially where electric vehicle fitment, all-weather reliability, and commercial durability are becoming decision drivers. Review manufacturing and sourcing footprints with policy resilience in mind, so that trade shifts do not force reactive restructuring.
For investors: Evaluate portfolio exposure to segments where technology differentiation and replacement demand provide more stable revenue characteristics. Consider how regional concentration, trade sensitivity, and input cost volatility affect margin resilience across target companies. Look for operators that demonstrate disciplined SKU strategy, strong application positioning, and the ability to convert product innovation into consistent commercial outcomes rather than one-time launches.
For procurement and fleet buyers: Shift evaluation frameworks toward total cost of ownership, including wear life, fuel efficiency implications, downtime risk, and seasonal performance reliability. Build sourcing strategies that include supplier diversification and visibility into input cost trends, reducing dependency on single points of failure. Align tire specification with actual operating conditions to avoid paying for unnecessary performance features or underperforming in critical use environments.
The tire market is not simply expanding; it is being re-segmented by technology expectations, policy dynamics, and end-use behavior. Organizations that anticipate these shifts early will be able to align product strategy, sourcing logic, and investment priorities before the next wave of competitive repositioning becomes visible. Comprehensive segment-level data, regional dynamics, and scenario-based planning can sharpen those decisions considerably. For decision makers seeking deeper granularity beyond this overview, the full research report provides the detailed breakdowns and customized strategic perspectives needed to convert market intelligence into execution-ready plans.
PW Consulting Automotive & Machinery Research Center
For detailed analysis of this topic, please visit the official page: Tire Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com


























Sign in to leave a comment.