

Can an employer automatically subtract 30 or 60 minutes for lunch from an employee's time card?
Sometimes. But calling a period "lunch" does not automatically make it unpaid.
Under federal wage-and-hour rules, a genuine meal period can generally be excluded from hours worked when the employee is sufficiently relieved from work duties. Short rest breaks, on the other hand, are ordinarily treated as paid work time.
The difference matters because incorrectly removing meal time from a time card can reduce regular hours, gross wages and even overtime pay.
The issue received fresh attention in September 2026 when the U.S. Department of Labor issued a new opinion letter addressing employees who spent part of a 60-minute unpaid meal period walking to and from an employer-designated break area.
For both employers and workers, the practical question is therefore not simply, "Was there a lunch break?"
The better question is:
Was the employee actually relieved from duty during the time that payroll excluded from paid hours?
Does Federal Law Require Employers to Give Lunch Breaks?
The Fair Labor Standards Act does not generally require employers to provide meal periods or rest breaks.
However, when an employer does provide breaks, federal rules determine whether certain break time must be counted as hours worked.
The U.S. Department of Labor's FLSA Hours Worked Advisor explains that short rest periods are generally compensable while bona fide meal periods generally are not.
State law is another layer.
Some states impose their own meal-period or rest-break requirements. Employees and employers therefore need to consider applicable state rules in addition to the federal baseline.
A break that satisfies the FLSA does not automatically resolve every state-law requirement.
What Counts as a Paid Rest Break?
Short rest breaks generally count as hours worked.
The Department of Labor states that breaks lasting approximately 5 to 20 minutes ordinarily must be counted as paid work time.
Examples can include:
- A 10-minute coffee break
- A 15-minute rest break
- A brief restroom break
- A short personal break
Because this time is normally treated as hours worked, employers should generally not deduct a standard 10- or 15-minute rest period from paid time simply because the employee was not actively performing normal job duties during those minutes.
This distinction is important when using a time card calculator with lunch and overtime. Paid rest breaks should not automatically be entered as unpaid lunch time.
When Can a Lunch Break Be Unpaid?
A bona fide meal period can generally be excluded from hours worked when the employee is genuinely relieved from duty.
The Department of Labor says that a meal period of around 30 minutes or more is ordinarily long enough, although a shorter period can potentially qualify under special circumstances.
The amount of time alone is not the only issue.
The employee must also be relieved from work responsibilities.
For example, a 30-minute period may not operate as a genuine unpaid lunch if the employee is required to:
- Answer business phone calls
- Respond to customers
- Monitor machinery
- Watch a reception desk
- Respond to required work messages
- Perform production duties
- Continue required administrative work
The DOL specifically explains that an office worker required to eat at a desk while answering calls or customers is not completely relieved from duty. The same principle applies to a factory employee required to watch equipment while eating.
The September 2026 DOL Lunch-Break Opinion Letter
The Department of Labor provided a useful new example on September 7, 2026.
In Opinion Letter FLSA2026-11, the agency considered an unpaid 60-minute lunch period where employees had to spend approximately 6 to 14 minutes walking to and from an employer-designated break area.
That left approximately 46 to 54 minutes after the required travel time.
Under the specific facts presented, the Wage and Hour Division concluded that the period remained a bona fide meal period.
The agency emphasized that the employees were relieved from work responsibilities and still had sufficient uninterrupted time to eat or attend to personal matters.
You can review the original Department of Labor Opinion Letter FLSA2026-11.
This is an important example because it shows that the analysis does not depend on one rigid rule such as "every minute required by the employer must make lunch paid."
The actual circumstances matter.
Does Walking to the Break Room Count as Work Time?
Not necessarily.
The September 2026 opinion letter involved employees who had to walk to an employer-designated meal area.
The Department of Labor did not conclude that the walking time automatically converted the entire 60-minute period into paid work.
Instead, the agency looked at whether employees remained sufficiently relieved from work and had enough usable time for the meal period after accounting for the travel.
That is why employers should be cautious about creating universal rules from one example.
A different situation involving a much shorter meal period, extensive security procedures, required work duties or other restrictions could require a different analysis.
What If You Work While Eating Lunch?
This is one of the clearest situations employees should examine.
Eating food does not automatically mean the employee is on an unpaid meal period.
Consider these examples:
Example 1: Answering Phones During Lunch
An office employee clocks out for lunch but must stay at the desk and answer customer calls.
Even if no customer happens to call during one particular lunch period, the requirement to remain responsible for that duty can affect whether the employee is genuinely relieved from work.
Example 2: Monitoring Equipment
A production employee eats beside a machine but must continuously monitor it.
The employee may still be performing job duties even though food is being eaten at the same time.
Example 3: Duty-Free Lunch
An employee clocks out for 30 minutes, performs no work, is relieved from job responsibilities and can use the period for personal purposes.
Under the federal baseline, this looks much more like a bona fide unpaid meal period.
Can an Employer Automatically Deduct 30 Minutes for Lunch?
An automatic deduction system is not necessarily wrong by itself.
The real problem arises if payroll deducts time that was actually compensable work.
For example, imagine an employer's system automatically removes 30 minutes every day.
On Monday, the employee takes the full duty-free lunch.
On Tuesday, the employee works through lunch because of a customer emergency.
On Wednesday, the employee receives only 15 uninterrupted minutes before being called back to work.
If the timekeeping system still deducts 30 minutes on all three days without accurately accounting for the work performed, the employee's recorded hours may be understated.
That can create a mismatch between the time actually worked and the hours eventually appearing on the paycheck.
If this happens, compare the records using the ePaystubs guide on what to do when pay stub hours do not match the time card.
Lunch Deductions Can Affect Overtime
An incorrect meal deduction does more than reduce straight-time wages.
It can also change overtime.
Under the federal FLSA baseline, covered nonexempt employees generally receive overtime for hours worked above 40 in a fixed workweek.
The Department of Labor's overtime guidance explains that overtime is generally paid at not less than one and one-half times the employee's regular rate for qualifying hours over 40.
Suppose a worker's time card shows:
- Monday: 8 hours
- Tuesday: 8 hours
- Wednesday: 8 hours
- Thursday: 8 hours
- Friday: 8 hours
Recorded total:
40 hours
Now suppose payroll automatically removed 30 minutes on Tuesday and Wednesday even though the employee actually worked through those lunches.
That adds back:
30 minutes + 30 minutes = 1 additional hour worked
The reconstructed workweek could therefore contain:
41 hours worked
For a covered nonexempt employee under the usual federal rule, that extra hour can matter to the overtime calculation.
Do Not Average Two Weeks to Avoid Overtime
This is especially important for employees paid biweekly.
A biweekly paycheck can contain two separate workweeks, but federal overtime is generally determined one workweek at a time.
For example:
- Week 1: 44 hours worked
- Week 2: 36 hours worked
The total across the biweekly period is 80 hours.
However, that does not normally eliminate the four overtime hours in the first workweek under the federal weekly overtime model.
This is why the pay period and the employer's defined workweek should not be treated as the same thing.
A paycheck may cover two weeks while overtime is still calculated independently inside each fixed workweek.
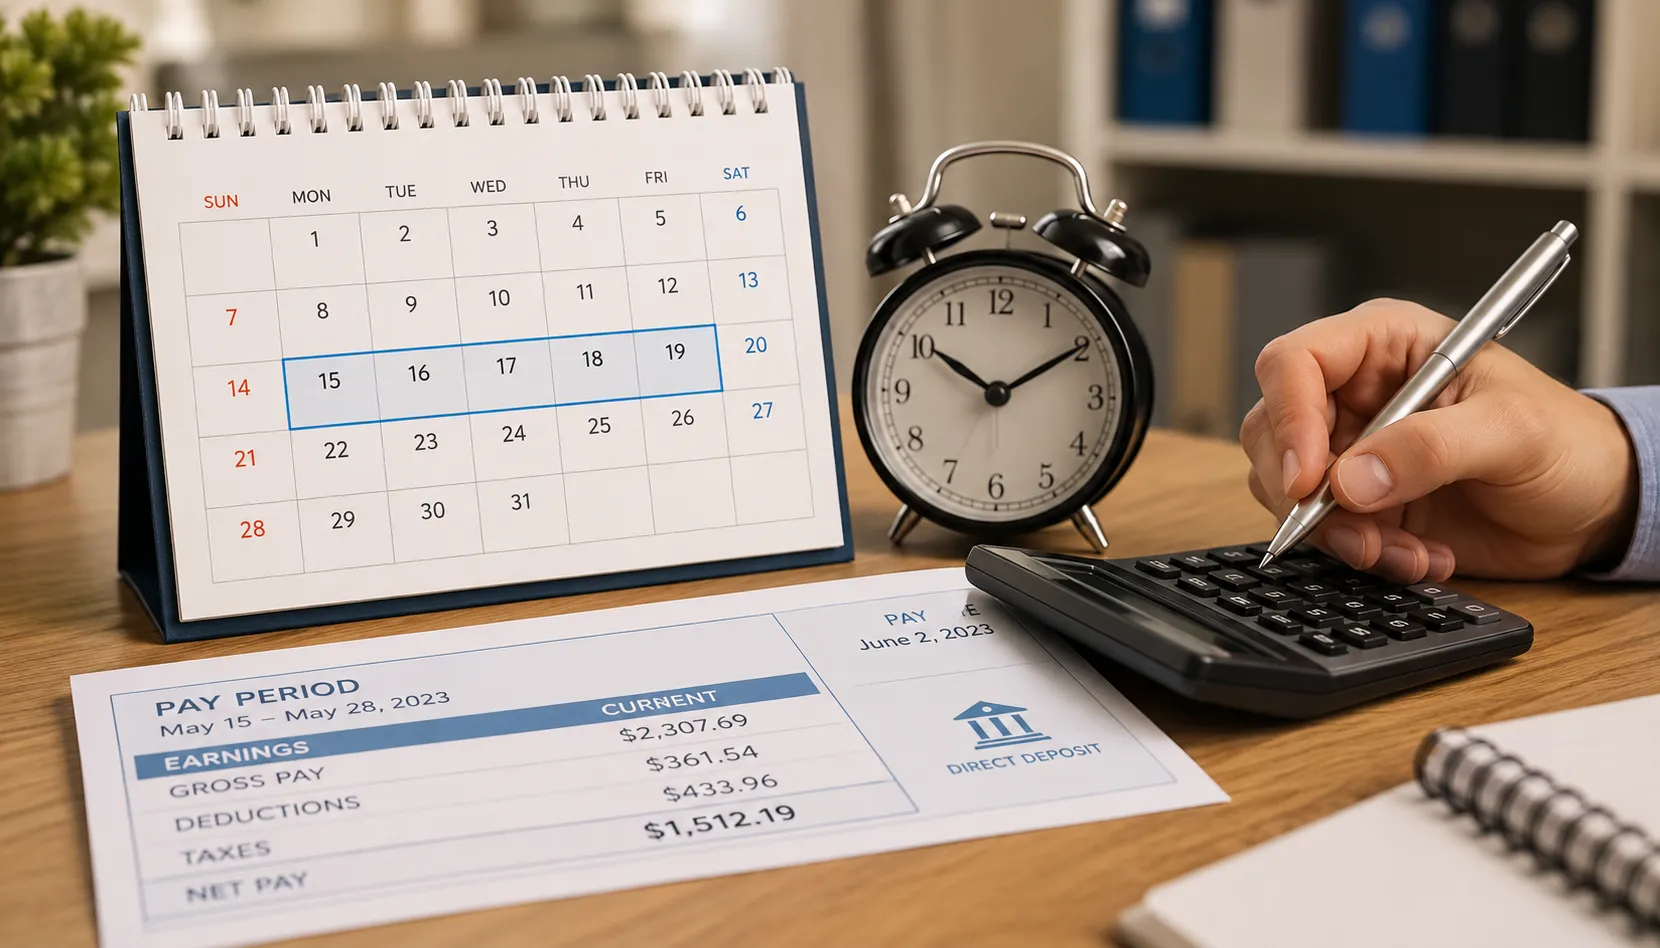
How to Calculate a Time Card With an Unpaid Lunch
For a basic duty-free lunch, the calculation is straightforward.
Suppose an employee works from:
8:00 a.m. to 4:30 p.m.
Total elapsed time:
8 hours 30 minutes
If the employee takes a qualifying 30-minute unpaid lunch:
8 hours 30 minutes − 30 minutes = 8 paid hours
That is different from simply assuming every shift contains an unpaid meal.
The actual lunch arrangement still needs to support excluding the time.
The free time card calculator with lunch and overtime can help reconstruct weekly or biweekly hours, subtract qualifying unpaid meal time and estimate overtime based on the hours entered.
Example: Working Through Half of Lunch
Consider an employee scheduled for a 30-minute lunch from noon to 12:30 p.m.
The employee begins lunch at noon but is required to handle a work issue from 12:10 p.m. until 12:25 p.m.
The employer should not blindly assume the normal 30-minute deduction produces the correct number of hours.
The actual facts need to be reviewed.
The key question is which portion of the period was properly excluded from hours worked under the applicable rules.
Employees should record the interruption accurately rather than simply changing a pay stub after payroll is processed.
What If an Employee Voluntarily Works Through Lunch?
Another common question is whether the time counts if the employer told the employee to take lunch but the worker voluntarily continued performing job duties.
Under the FLSA, employers can have policies requiring employees to follow timekeeping and meal-period procedures.
However, compensability generally depends on whether work was actually performed and whether the employer knew or had reason to know about compensable work.
An employer policy stating "do not work during lunch" does not automatically make actual work disappear from the time record.
Employees should still follow legitimate company procedures for reporting interrupted or missed meal periods.
What If an Employee Eats at the Desk?
Eating at a desk is not automatically paid work, but it is also not automatically an unpaid meal.
The relevant issue is whether the employee remains responsible for job duties.
For example:
- Eating at a desk while freely reading personal messages may still be a genuine break.
- Eating at a desk while required to answer customer calls is different.
- Eating while monitoring a work system or machine may also be different.
Focus on the duties performed and restrictions imposed, not merely where the employee ate.
Should a 15-Minute Break Be Deducted From the Time Card?
Generally, not under the usual federal treatment of short rest periods.
The Department of Labor says breaks of about 5 to 20 minutes ordinarily count as hours worked.
If an employee works an eight-hour paid shift and also receives two normal 15-minute rest breaks, those short breaks are generally not treated like 30-minute duty-free meal periods.
This is one reason employers should use separate timekeeping categories for:
- Paid rest breaks
- Unpaid meal periods
- Actual work time
- Paid leave
What If the Time Card and Pay Stub Show Different Hours?
Do not immediately compare one large total against another.
Start with the dates.
Make sure the time card and paycheck cover the same pay period.
Then compare:
- Clock-in time
- Clock-out time
- Lunch-out time
- Lunch-in time
- Regular hours
- Overtime hours
- Paid leave
- Holiday hours
- Shift differentials
- Retroactive adjustments
If a difference remains, use the detailed timecard-to-pay-stub reconciliation checklist before contacting payroll.
Compare Gross Pay Before Net Pay
When checking whether a lunch deduction reduced a paycheck, compare expected earnings with gross pay first.
Do not begin with the direct-deposit amount.
Gross pay and net pay measure different things.
Gross pay represents earnings before applicable employee taxes and deductions.
Net pay is what remains after payroll taxes, benefits and other deductions.
If one hour of pay is missing, the effect should first be investigated in the earnings and gross-pay calculation.
The difference in take-home pay will usually be smaller than the missing gross amount because payroll taxes and deductions can also change.
Example: Missing Lunch Time Changes Gross Pay
Suppose an employee earns $20 per hour.
Payroll incorrectly deducts one additional hour during the week.
At straight time:
1 hour × $20 = $20 in gross wages
If that hour should instead have been an overtime hour under the applicable federal overtime calculation, the effect could be different.
This is why employees should first determine which workweek the missing time belongs to before estimating the gross-pay difference.
How Should the Hours Appear on a Pay Stub?
Payroll layouts vary, but an hourly employee's statement may include separate lines for:
- REG or regular hours
- OT or overtime
- Holiday pay
- PTO or vacation
- Shift differential
- Other earnings
A guide explaining what is on a pay stub can help employees identify the earnings section before comparing it with a time card.
Do not assume that every compensated hour will appear in one single "hours" field.
Do YTD Hours Help Find Lunch-Break Errors?
Sometimes, but current-period hours are usually the better starting point.
YTD on a pay stub is a cumulative figure.
A YTD hours line may show the accumulated hours associated with a particular payroll category throughout the year.
That can be useful for spotting a larger pattern, but it is less useful for diagnosing whether 30 minutes were incorrectly deducted on one particular Tuesday.
For a single disputed paycheck, start with the current pay period and then use YTD information as a broader consistency check.
Does Fixing Missing Overtime Mean the Overtime Is Tax-Free?
No.
If previously omitted hours are added back and create overtime earnings, those wages can still be subject to payroll withholding.
The 2026 federal deduction associated with qualifying overtime does not simply make every overtime dollar exempt from paycheck taxes.
The ePaystubs guide explaining why overtime is still taxed in 2026 breaks down the difference between payroll withholding and the separate federal income-tax deduction rules.
What Should Employers Do About Automatic Lunch Deductions?
Automatic deductions require reliable exception procedures.
A practical payroll process should allow employees and supervisors to record situations such as:
- Missed lunch
- Interrupted lunch
- Partial lunch
- Required work during lunch
- Incorrect time-clock deduction
The employer should then make sure the actual compensable time flows into payroll.
An automatic 30-minute deduction may appear efficient, but a system that cannot account for exceptions can create recurring discrepancies.
What Records Should an Employee Keep?
If an employee believes meal time is being deducted incorrectly, useful records may include:
- Original time-card screenshots or reports
- Clock-in and clock-out records
- Meal punches
- Work schedules
- Pay stubs
- Emails or messages showing work performed during lunch
- Payroll correction requests
The Department of Labor also offers the WorkWise Timesheet app, which can help track regular hours, breaks, overtime and pay.
Personal records can assist with reconciliation, but they do not replace an employer's official payroll records.
2026 Employee Lunch-Break Pay Checklist
- Confirm how long the scheduled meal period is.
- Determine whether the break is intended to be paid or unpaid.
- Record actual lunch-out and lunch-in times where required.
- Note interruptions involving real work.
- Separate paid short breaks from unpaid meals.
- Check whether payroll automatically deducted lunch time.
- Compare each workweek separately for overtime.
- Compare the time card with current pay-stub hours.
- Compare expected gross earnings before comparing net pay.
- Check applicable state meal and rest-break rules.
2026 Employer Lunch-Break Payroll Checklist
- Document whether meal periods are paid or unpaid.
- Do not classify ordinary 5-to-20-minute rest breaks as unpaid lunches under the federal baseline.
- Ensure employees are sufficiently relieved from duty during unpaid meal periods.
- Provide a way to report interrupted or missed meals.
- Review automatic lunch deductions for exceptions.
- Calculate overtime by workweek rather than averaging two weeks.
- Preserve reliable timekeeping records.
- Reconcile approved hours with payroll before issuing pay statements.
- Check state and local requirements in addition to federal law.
Creating Accurate Pay Statements From Approved Time Records
Once timekeeping records have been reviewed and approved, payroll should use the actual paid hours and earnings when preparing employee statements.
Authorized employers and payroll users can create pay stubs online using legitimate wage, hour, tax and deduction information.
A generated pay statement should reflect genuine payroll records. It should not be used to replace employer time records, conceal missing hours or invent employment income.
Official Government Resources
- U.S. Department of Labor — Opinion Letter FLSA2026-11
- Department of Labor — Meal Periods and Rest Breaks
- Department of Labor — Short Rest Break Rules
- Department of Labor — FLSA Overtime Pay Requirements
- Department of Labor — WorkWise Timesheet
Final Thoughts
An unpaid lunch break is not determined by the word "lunch" appearing on a schedule or time card.
Under the federal baseline, short rest breaks are generally treated as paid work time, while a bona fide meal period can usually be unpaid when the employee is sufficiently relieved from duty.
The Department of Labor's September 2026 opinion letter also shows why meal-period questions can depend heavily on the facts. In that case, employees still had approximately 46 to 54 minutes available for personal purposes after required walking time, and the agency concluded that the 60-minute period remained a bona fide meal period.
For payroll purposes, the most important practice is accurate timekeeping.
Record the hours actually worked, subtract only properly excludable unpaid meal time, calculate overtime by workweek and then compare those figures with the employee's gross earnings on the pay statement.
If the time card and pay stub do not reconcile, investigate the specific dates, meal deductions and overtime hours before assuming the difference is correct.















Sign in to leave a comment.