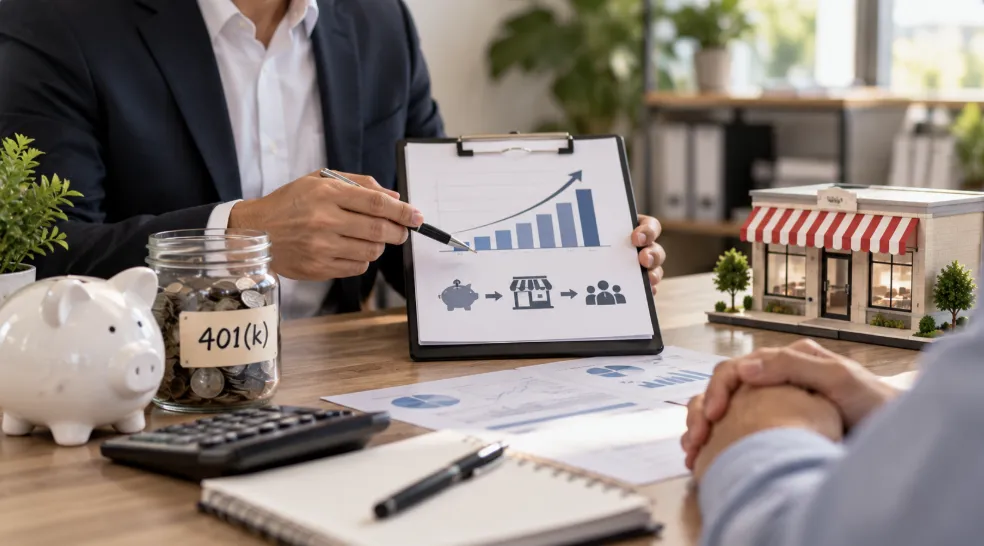

Starting a franchise often requires more than a good business idea. There may be franchise fees, equipment, real estate costs, working capital and other expenses to cover before the business begins generating revenue. For people who have built substantial retirement savings, those funds may raise an interesting question: can retirement money be used to finance a new business?
A 401k rollover to buy a franchise is one option some prospective franchise owners explore. One structure used for this purpose is called a ROBS, or Rollover as Business Startups. It allows eligible retirement funds to be invested in a business under a specific legal and tax structure. Understanding how the arrangement works can help potential franchise buyers determine whether it fits their financial situation.

What Is a ROBS 401k?
A ROBS 401k is a business funding arrangement that allows certain retirement funds to be rolled into a newly established retirement plan connected to a business. The new plan can then invest in the company by purchasing shares of its stock.
Rather than taking a traditional cash distribution from a personal 401k, the funds move through a structured process involving a new corporation and its retirement plan.
The basic concept sounds simple, but the arrangement involves specific rules and administrative responsibilities. That is why anyone considering a ROBS 401k should understand the structure before moving money.
How Does a 401k Rollover to Buy a Franchise Work?
The process generally involves several steps.
First, a new business entity is established, typically as a corporation. That company creates a qualified retirement plan. The individual's eligible retirement funds can then be rolled into the new plan.
The retirement plan uses those funds to purchase stock in the newly established company. The company receives the money and can use the capital for approved business purposes, including expenses associated with purchasing and operating a franchise.
This structure is different from simply withdrawing money from a retirement account and spending it on a franchise. The distinction matters because early withdrawals can potentially create taxes and penalties depending on the individual's circumstances.
Why Do Franchise Buyers Consider ROBS?
Access to capital is one reason entrepreneurs investigate this option. A franchise purchase can involve a considerable upfront investment, and traditional financing may not always cover every expense.
A ROBS arrangement can potentially provide business capital without requiring the owner to take a conventional taxable distribution from a retirement account.
It may also allow an entrepreneur to invest retirement savings directly into a business rather than leaving those funds entirely in traditional retirement investments.
However, there is an important tradeoff. Retirement savings are being exposed to the performance of the business. If the franchise struggles or fails, the retirement funds invested through the structure can also be affected.
What Are the Risks and Responsibilities?
A 401k rollover to buy a franchise should not be treated as a simple funding shortcut.
ROBS arrangements must follow applicable retirement plan and tax rules. The business also has ongoing administrative responsibilities related to the retirement plan.
Another consideration is concentration of risk. Using a substantial portion of retirement savings for one business can reduce diversification. A franchise may have a proven business model, but no business investment is guaranteed to succeed.
Potential franchise owners should also consider their emergency savings, household expenses, debt obligations and the amount of retirement money they are comfortable putting at risk.
Is ROBS Right for Every Franchise Buyer?
No single funding method works for every entrepreneur.
A ROBS 401k may be worth researching for someone who has eligible retirement assets and wants to invest directly in a franchise business. Another buyer may prefer an SBA loan, conventional financing, personal savings or a combination of funding sources.
The franchise itself also matters. Initial investment, ongoing fees, expected operating expenses and working capital requirements can vary considerably between brands.
Before deciding, it is sensible to review the franchise disclosure document, understand the total investment and create a realistic financial plan.
Questions to Ask Before Using Retirement Funds
Before pursuing a ROBS structure, prospective franchise owners can ask:
- How much retirement money would be invested?
- How much cash would remain available for emergencies?
- What are the franchise's total startup and operating costs?
- What administrative responsibilities come with the retirement plan?
- What happens to the retirement funds if the business closes?
- Are there alternative financing options?
- Have qualified tax, legal and financial professionals reviewed the structure?
These questions can help separate the appeal of available capital from the actual financial realities of franchise ownership.
Final Thoughts
A ROBS 401k can provide a way for certain entrepreneurs to use eligible retirement savings as capital for a franchise, but it comes with rules, responsibilities and financial risk. Anyone considering a 401k rollover to buy a franchise should understand the structure carefully and seek advice from qualified professionals before making a decision.
For people who are still researching franchise opportunities, Franchises Available Now can be a useful place to explore different franchise options and compare opportunities before deciding which direction to pursue.























Sign in to leave a comment.