
Planning for retirement involves more than creating enough savings to stop working. One often-overlooked risk is the possibility of needing ongoing assistance with everyday activities later in life. What is long term care insurance can play an important role.
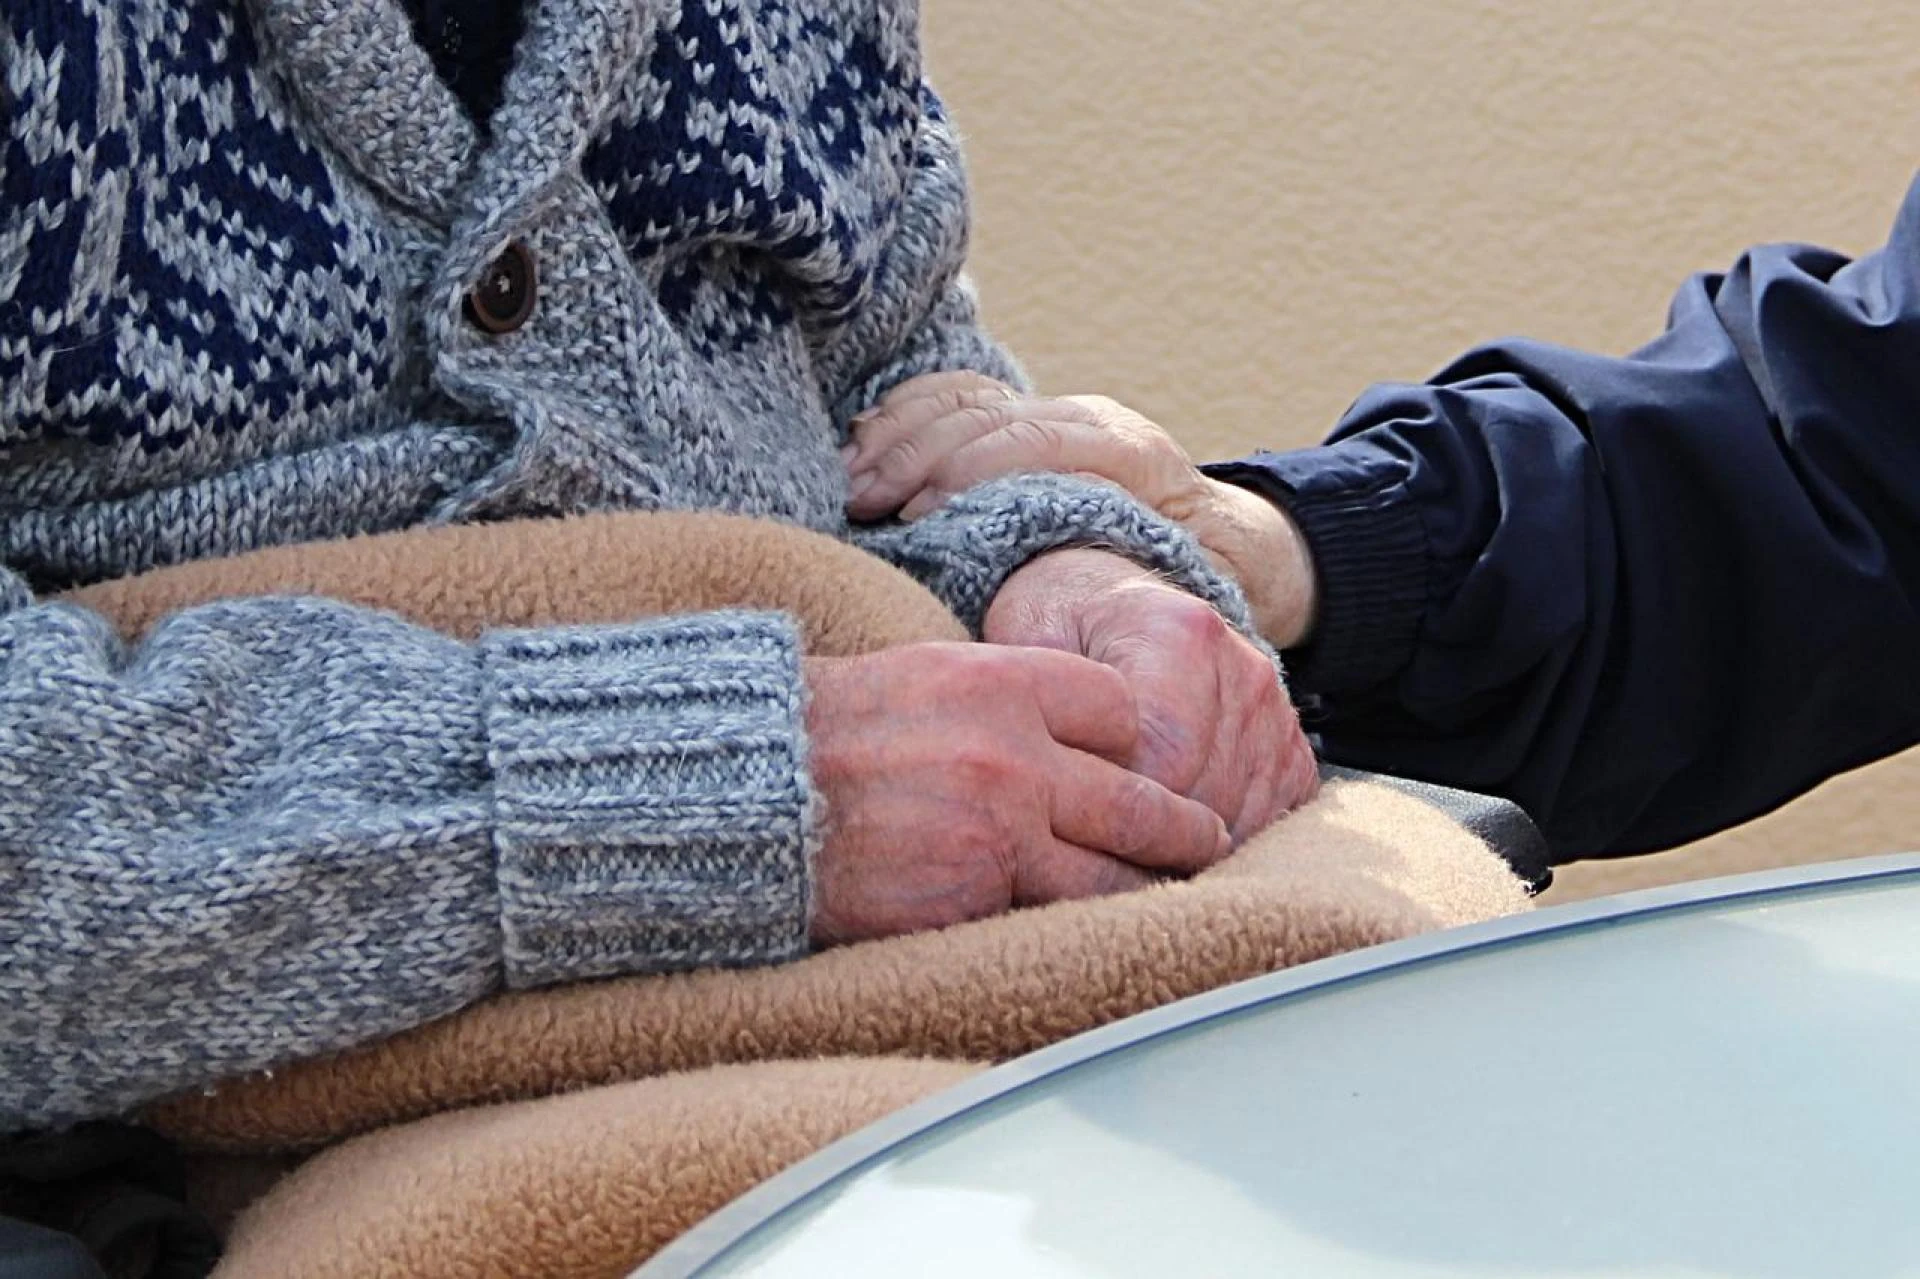
So, what is long term care insurance? It is insurance designed to help pay for extended care and support when a person needs assistance because of aging, chronic illness, disability, or cognitive impairment. Depending on the policy, benefits may help pay for care received at home, in assisted living, or in a nursing facility.
What is long term care insurance Cover?
Unlike traditional health insurance, long-term care insurance focuses primarily on ongoing personal and custodial care rather than treating an illness or injury.
Covered services can include:
- In-home caregivers and home health assistance
- Assisted living expenses
- Nursing home care
- Adult day care
- Certain care coordination services
- Other eligible long-term support services
The exact benefits depend on the policy. Coverage may have a daily benefit limit, a maximum benefit period, or a lifetime benefit pool. Some policies also offer inflation protection to help benefits keep pace with rising care costs.
How Does Long-Term Care Insurance Work?
Most policies require you to qualify for benefits before the insurer begins paying. A common qualification standard involves being unable to perform at least two of six Activities of Daily Living, often called ADLs.
These activities generally include bathing, dressing, eating, toileting, transferring, and continence. Cognitive impairment may also qualify someone for benefits under many policies.
Many policies also have an elimination period. During this period, you may need to pay eligible care expenses yourself before insurance benefits begin. The length can vary substantially by policy.
This is why understanding the policy's benefit triggers, waiting period, daily limits, inflation adjustments, and exclusions is essential before purchasing coverage.
Does Medicare Pay for Long-Term Care?
One of the biggest misconceptions about long-term care is that Medicare will pay for all future care needs.
Medicare may cover certain medical services and qualifying short-term skilled care, but it generally does not function as comprehensive insurance for ongoing custodial assistance such as help with bathing, dressing, or eating.
That distinction can create a significant financial planning gap.
A retirement plan may look strong when measured against normal living expenses, but prolonged care expenses can place additional pressure on savings and retirement income. Long-term care planning helps address that risk before it becomes an emergency.
Who Should Consider Long-Term Care Insurance?
There is no universal answer. The right approach depends on your age, health, income, assets, family situation, retirement goals, and ability to absorb future care expenses.
People approaching retirement may want to evaluate LTC coverage if they want to:
- Protect retirement assets from potentially large care expenses
- Reduce the financial burden on children or other family members
- Maintain greater flexibility about where care is received
- Create a more predictable retirement-income strategy
- Preserve assets intended for a spouse or heirs
The NAIC recommends considering your overall financial resources and ability to afford premiums rather than assuming long-term care insurance is appropriate for everyone.
Traditional vs. Hybrid Long-Term Care Insurance
Traditional long-term care insurance is specifically designed to provide long-term care benefits. It can offer substantial coverage but generally requires ongoing premiums, and the policy may not provide a death benefit if the insured never needs care.
Hybrid policies combine long-term care protection with another financial product, commonly life insurance. If long-term care is needed, the policy may provide benefits for eligible care expenses. If care is never needed, the policy may provide a death benefit to beneficiaries, depending on the contract.
Hybrid coverage can therefore be attractive to people who want their financial plan to address both long-term care risk and legacy objectives. However, costs, benefits, liquidity, guarantees, and policy provisions vary considerably.
What Does Long-Term Care Insurance Cost?
There is no single price for long-term care insurance. Premiums can depend on factors such as age, health, coverage amount, benefit period, inflation protection, policy design, and the insurer.
For example, a policy with a higher daily benefit and stronger inflation protection will generally have a different premium from a policy with lower benefits. Premiums can also change depending on the insurer and policy structure.
Because of this, comparing policies solely by premium can be misleading. The better question is whether the coverage meaningfully addresses the financial risk you are trying to manage.
When Should You Start Planning for Long-Term Care?
Waiting until care is needed is not a practical insurance strategy. Medical underwriting can affect eligibility, and your age and health can influence available options and pricing.
A better approach is to consider long-term care as part of retirement planning before a potential need arises. Review your retirement assets, expected income, family resources, desired care setting, and legacy goals.
You can then compare several approaches, including traditional LTC insurance, hybrid policies, self-funding, and a combination of financial resources.
Build Long-Term Care Into Your Retirement Strategy
The biggest benefit of long-term care planning is not simply having an insurance policy. It is knowing how potential care expenses fit into your broader financial plan.
Ask yourself: If I needed several years of care, where would the money come from? Would paying those expenses significantly reduce my retirement income? Would my spouse or family be financially affected? Would the assets I hope to leave to my heirs remain protected?
Answering these questions early can help you make more informed decisions.
If you are evaluating how long-term care could affect your retirement and asset-preservation goals, Franklin Wealth Strategies can help you explore your options and build long-term care considerations into a broader financial strategy.
Conclusion
So, what is long term care insurance? It is a financial protection tool designed to help cover eligible extended care expenses when you can no longer manage certain daily activities independently. It can help protect retirement assets, provide greater flexibility in choosing care, and reduce the financial pressure placed on loved ones.
However, long-term care insurance is not automatically right for everyone. The decision should consider your health, age, assets, income, retirement objectives, family circumstances, and willingness to self-fund potential care.
Before choosing a policy, compare the benefits, exclusions, elimination period, inflation protection, benefit duration, and premium structure. Franklin Wealth Strategies can help you evaluate how long-term care planning fits within your retirement and wealth-preservation strategy.















Sign in to leave a comment.