When Is the Right Time to Remortgage? A UK Homeowner's Guide

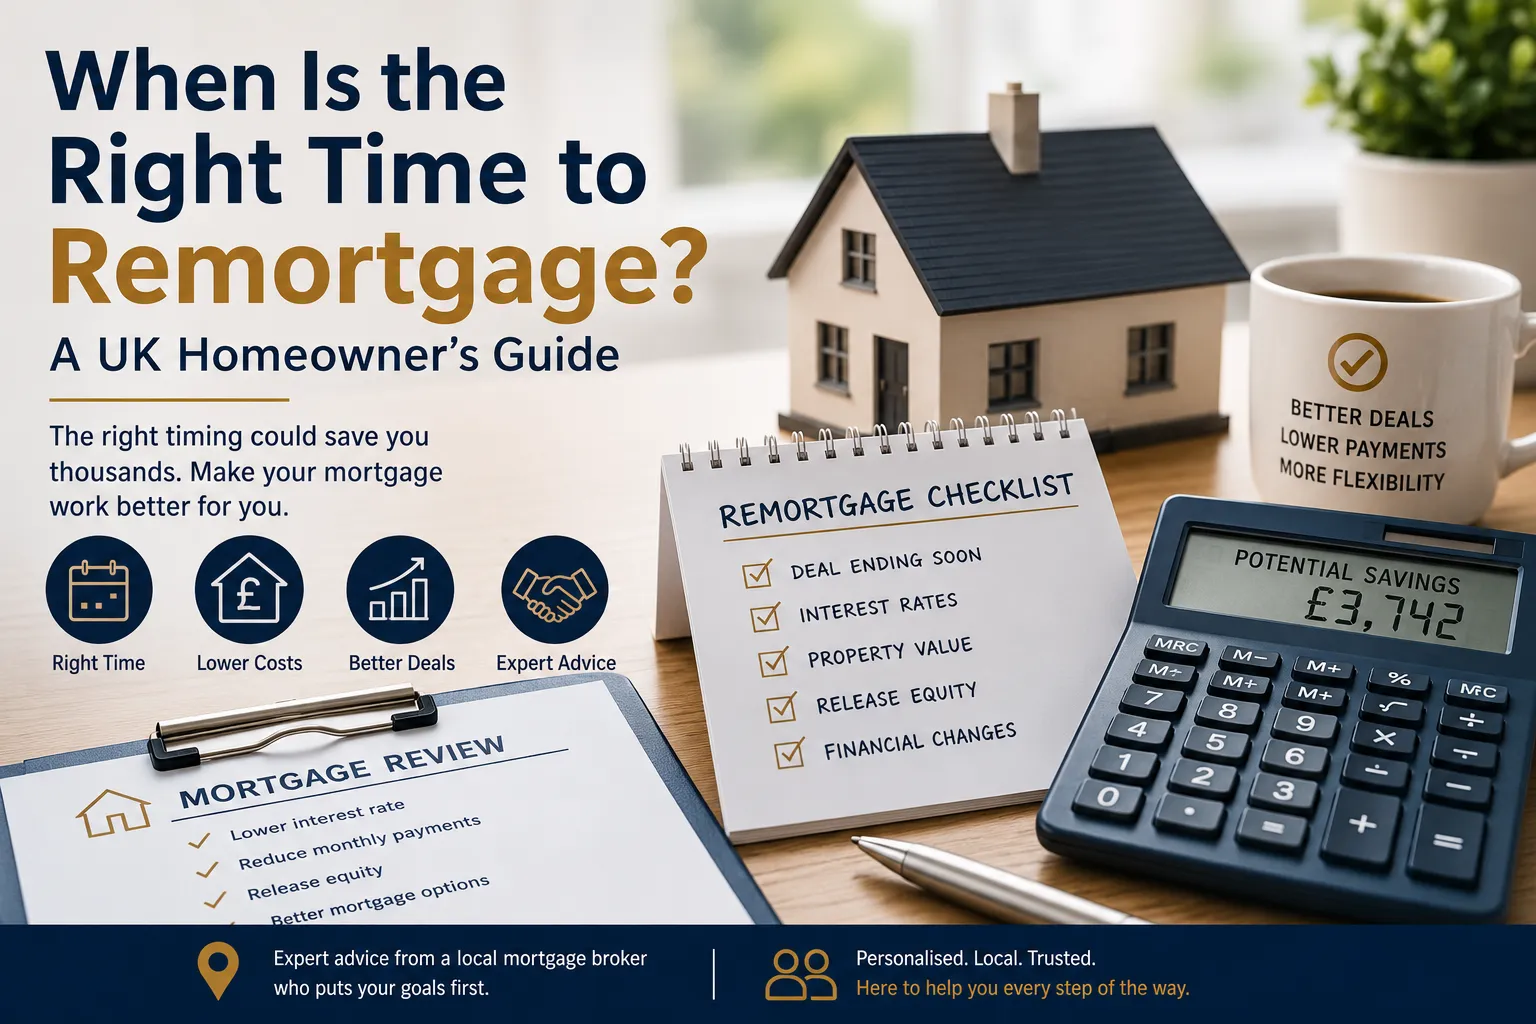
If you own a home in the UK, chances are you've heard the word "remortgage" thrown around by friends, family, or your bank. But knowing when to actually make the move can feel confusing, especially with interest rates shifting and lenders constantly updating their offers. Timing your remortgage correctly can save you thousands of pounds over the life of your loan, while getting it wrong could lock you into a deal that costs you far more than necessary.
What Does Remortgaging Actually Mean?
Remortgaging simply means switching your existing mortgage to a new deal, either with your current lender or a different one. This is different from moving house. You stay in the same property, but you replace your current mortgage arrangement with a new one, usually to get a better interest rate, release equity, or consolidate debt.
Many homeowners assume remortgaging is only necessary when something goes wrong financially. In reality, it's a routine part of responsible homeownership, much like servicing a car before it breaks down rather than after.
Signs It Might Be Time to Remortgage
Your Fixed Rate Deal Is Ending
The most common trigger for remortgaging is the end of a fixed rate period. Most homeowners take out two, three, or five-year fixed deals. Once that period ends, you're typically moved onto your lender's Standard Variable Rate (SVR), which is almost always higher than a competitive fixed rate. If your deal is ending within the next six months, now is the time to start exploring your options.
Interest Rates Have Dropped Since You Took Out Your Mortgage
If the Bank of England base rate has fallen since you last secured a mortgage, there may be significantly better deals available now than when you first borrowed. Even a small reduction in your interest rate can translate into meaningful monthly savings.
Your Property Value Has Increased
If your home has gone up in value, your loan-to-value (LTV) ratio improves, which often qualifies you for better rates. Lenders reserve their most competitive deals for borrowers with lower LTV ratios, so a property revaluation could unlock savings you didn't know were available.
You Want to Release Equity
Some homeowners remortgage specifically to access the equity built up in their property, whether for home improvements, debt consolidation, or helping a family member onto the property ladder. This is a common and legitimate reason to remortgage, provided it's done with proper advice.
Your Financial Circumstances Have Changed
A change in income, employment status, or credit score can affect what deals you're eligible for. Sometimes remortgaging earlier than planned makes sense if your improved financial position opens the door to significantly better terms.
When You Should Think Twice
Remortgaging isn't always the right move. If you're still in the middle of a fixed term, exiting early usually triggers an Early Repayment Charge (ERC), which can sometimes outweigh any savings from switching. It's also worth pausing if your credit situation has recently worsened, as this could limit the deals available to you or result in a less favourable rate than you currently have.
This is exactly where working with a broker becomes valuable rather than optional. A knowledgeable remortgage broker UK homeowners trust can run the numbers for you, weighing ERCs against potential savings so you're not left guessing whether the timing works in your favour. In fact, speaking to a trusted remortgage broker in the UK is often the fastest way to find out.
How Far in Advance Should You Start Looking?
Most mortgage brokers recommend starting the remortgage process around three to six months before your current deal expires. Many lenders allow you to lock in a new rate months ahead of time, which protects you from rate rises while giving you the flexibility to switch if a better deal appears closer to your renewal date.
Starting early also gives you breathing room to sort out paperwork, get a property valuation if needed, and address any credit issues that might affect your application. Leaving it until the last minute often means settling for whatever deal is available rather than the one that actually suits your circumstances.
The Value of Local, Personalised Advice
Every homeowner's situation is different. Two people with the same income and property value might need completely different mortgage products depending on their long-term plans, family circumstances, or appetite for risk. This is why generic online comparisons only tell part of the story.
Working with an adviser who understands the local property market can make a real difference. If you're just getting started on your homeownership journey, it's also worth exploring guidance built specifically for newer buyers, since many of the same principles around timing, rates, and eligibility apply whether you're buying your first home or remortgaging your fifth. A top first time buyer mortgage broker in Bolton can walk you through both scenarios side by side.



Sign in to leave a comment.