
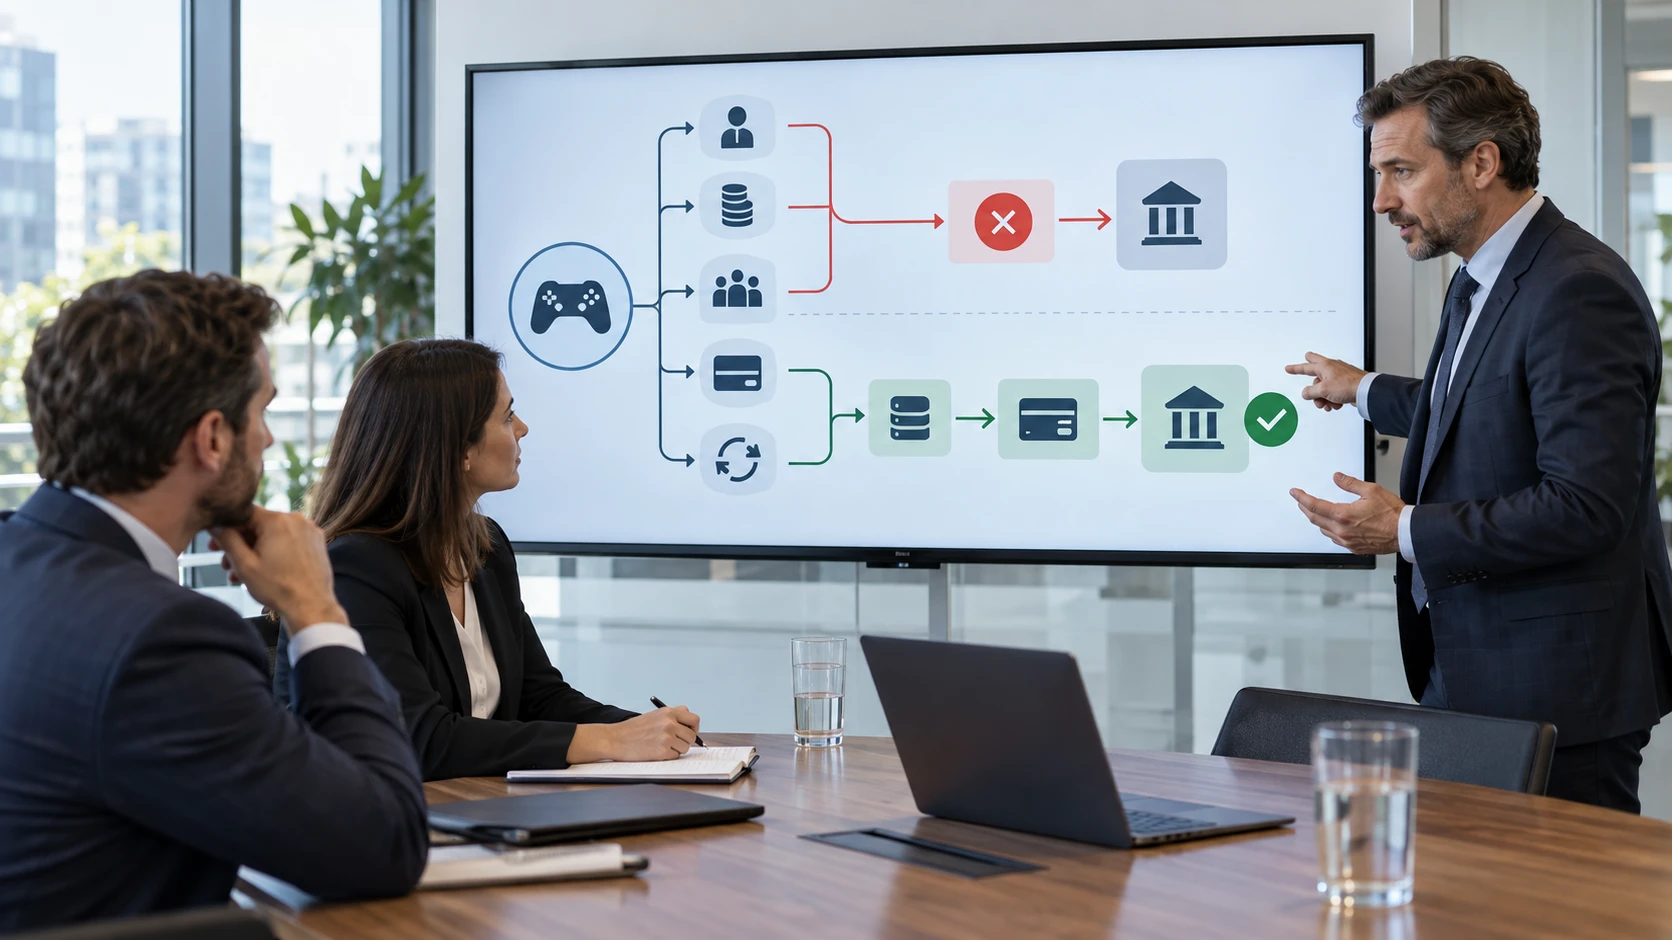
Licensed gambling companies get rejected by banks not because their licence is invalid, but because the structure behind it fails the bank's internal risk assessment. A valid gaming licence proves legal permission to operate — nothing more. It doesn't prove the business is organised, documented, and monitored the way a bank or payment processor needs before taking on a high-risk merchant relationship.
Banks look at the full payment chain: how player deposits come in, how payouts and refunds go out, how chargebacks are tracked, and how operational expenses are kept separate from player funds. They check ownership records, AML and KYC policies, source-of-funds proof, target markets, projected transaction volumes, and chargeback history — all before anyone makes an approval decision. One gap in any of these areas is enough to get rejected, regardless of where the licence was issued.
For operators who've already been turned down, the path forward starts with pinpointing exactly what failed. Was it the documentation? The entity setup? The chargeback ratio? Once that's clear, you fix it — then match the application to a provider with both the appetite and the expertise to approve it. Diagnosis, restructuring, placement. That's what specialist advisers in this space actually do.
Why a licence alone does not make a gambling business bankable
A bank evaluates the full risk stack — not just the licence, but the ownership structure, player geography, payment flows, and control systems.
A licence tells the bank one thing: a regulator reviewed the company at a specific point in time. Everything else — who ultimately owns the business, which markets players come from, how payouts are processed, whether chargebacks are under control — the licence doesn't explain. Banks and payment processors examine all of these layers simultaneously. A gap in any one of them blocks approval, regardless of jurisdiction.
[BLOCK: risk factors matrix (inline visual)]
Ownership transparency, source-of-funds documentation, settlement structure, and player geography each carry independent weight in underwriting. A company with a clean licence but an opaque corporate structure — or one accepting deposits from markets the provider doesn't service — gets the same outcome as an unlicensed operator: rejection or account restriction.
How jurisdiction and licence type affect bank approval
Banks and EMIs assess risk differently, so the same licence may be accepted by one provider and declined by another.
| Licence type | Tier-1 bank | Specialist EMI | Key friction point |
|---|---|---|---|
| UKGC | Often accepted | Widely accepted | MCC 7995 may still trigger policy blocks |
| MGA (Malta) | Selective | Generally accepted | Cross-border player markets scrutinised |
| EU-member state (e.g. Estonia, Denmark) | Selective | Accepted with due diligence | Target market alignment required |
| Offshore (e.g. Curaçao, Isle of Man) | Rarely accepted | Provider-dependent | AML controls and jurisdiction risk flag |
Most major banks include explicit exclusions in their policy — language like "no online gambling" or "no offshore gaming". These reflect AML risk and regulatory uncertainty, not the operator's actual compliance history. An operator with a Curaçao licence serving a European audience will be declined not because the licence is invalid — the problem is that cross-border rights create legal ambiguity that bank compliance teams cannot model. On top of that, MCC 7995 — the merchant category code for gambling transactions — triggers automatically at underwriting, flagging the application as high-risk regardless of jurisdiction or document quality.
What the bank's internal review actually checks
Banks check whether the licence, ownership, funds, player geography, payments, and controls all add up to a risk profile they can accept.
The underwriter builds a picture from specific documents, then tests whether that picture holds together. For gambling companies, a single gap or contradiction between items is enough to pause or kill the application.
What the bank verifies against its checklist:
- Gaming licence — jurisdiction, scope, and whether the issuing authority is accepted by that bank or payment processor.
- UBO and ownership records — full beneficial ownership chain, with no unresolved gaps or nominee arrangements.
- Source of funds — documented evidence of where capitalisation and operating funds originate.
- Player markets — the list of jurisdictions where deposits are accepted, checked against the bank's restricted-country policy.
- Deposit and payout flows — how money enters and leaves the business, and whether the account structure can reflect that cleanly.
- Chargeback history and dispute controls — tracked dispute ratios, plus evidence that the operator maintains deposit records, login data, and player verification logs.
- AML and KYC policies — written procedures the bank can read and assess, not just a declaration that procedures exist.
- Settlement risk — payout timelines, reserve arrangements, and whether the payment provider setup can handle volume at scale.
Consistency matters as much as content. A business bank account application showing a Curaçao licence but listing EU player markets — or describing low transaction volumes while projecting rapid growth — creates contradictions the underwriter can't resolve. They'll either ask for more, or decline.
Payment flows, chargebacks, and the red flags that stall approval
Gambling payments carry elevated risk of disputes, refunds, and settlement problems — which is why providers examine the entire payment flow before opening an account.
A provider doesn't look at a single descriptor. It assesses deposits, withdrawals, player refunds, bonus settlements, and chargeback history as one connected chain. A player who loses money will sometimes file a dispute with their bank — especially if they don't recognise the billing descriptor. That's a chargeback. When the dispute ratio climbs, the provider introduces reserves, tightens limits, or closes the account.
A clean payment structure separates player funds from operational money, uses consistent descriptors, and has documented refund procedures. A problematic structure mixes settlements, runs funds through opaque legal entities, and leaves no audit trail. Providers read this as unmanageable risk and decline before the relationship begins — regardless of whether a licence is in place.
Rejection reasons you can fix before reapplying — and ones you cannot
Applications are most often declined for fixable reasons: document inconsistencies, weak source-of-funds evidence, unclear business descriptions. Reapplying without addressing the actual problem is exactly how gambling companies accumulate multiple consecutive rejections.
Quick fixes — resolve before reapplying:
- Expired documents or bank statements.
- Typos and mismatches in company name, address, or registration details.
- Missing AML/KYC policies or incomplete ownership structure information.
- No description of target player markets or transaction volume projections.
- Billing descriptors that players don't recognise and dispute.
Structural problems — reapplying alone won't resolve these:
- The licence jurisdiction is not accepted by the target bank or payment provider.
- Accepting players from markets the provider does not support.
- Complex corporate structure with unexplained beneficial owners.
- No documented chargeback history or dispute management process.
- Business model falls outside what the provider is willing to underwrite in gambling.
Which advisers fix the structure when the bank says no
Yes — if the adviser resolves the actual rejection cause: a compliance problem, a structural issue, or a payment risk — rather than simply resubmitting the same application.
The right choice of adviser depends on why the bank declined. Regulatory or compliance counsel rewrites AML/KYC policies and closes the gaps the bank identifies during document review. Corporate structuring advisers untangle UBO complexity or rebuild account separation so that player funds, merchant settlements, and operating expenses sit in clearly defined structures. Banking-introduction specialists know which banks actually underwrite gambling businesses and frame applications in terms underwriters recognise. Payment consultants audit the entire payment chain and remove red flags — descriptor mismatches, unsupported markets, undocumented refund flows — that sink an application before it reaches the credit committee.
Among firms working specifically with licensed gambling operators:
- MGL Solutions handles end-to-end structural cases — from licence review and AML policy rebuild through to banking placement and payment rail setup.
- Vixio GamblingCompliance advises on regulatory and compliance positioning across multiple jurisdictions and helps close the documentation gaps that cause applications to be turned down at the underwriting stage.
- Pentasia Financial specialises in corporate finance and banking advisory for gambling businesses — including post-rejection restructuring and provider matching for operators with complex ownership chains.
A mismatch between adviser and problem costs time. If the issue is documentation — missing KYC logs, outdated source-of-funds evidence — the fix is compliance work, not a new banking introduction. If the issue is structure — for example, a holding company registered in a jurisdiction the bank considers opaque — a restructuring adviser comes first, and a new application follows only after that work is done.
Step-by-step: how advisers rebuild a bankable structure after rejection
Diagnose the real rejection reason, fix what's fixable, and resubmit with a cleaner structure and harder compliance evidence.
- Identify the specific rejection trigger — licence type, jurisdiction, AML/KYC gaps, corporate structure, or payment routing. Each problem has a different fix.
- Audit existing documentation — deposit records, player verification logs, refund history, support records. Missing or outdated files are the fastest win: one complete compliance pack, ready to review.
- Tighten AML and KYC policies — rewrite procedures to match what the bank actually expects, producing an updated policy document the reviewer can assess without chasing context.
- Restructure accounts — separate player funds, merchant settlements, and operational costs so the bank can trace where money comes from and where it goes.
- Address deeper structural issues — if the holding structure or market routing is the blocker, advisers redesign entity arrangements or cut player markets down to what the provider will accept.
- Assemble the approval pack — licence records, ownership documents, AML policies, volume projections, and chargeback history in a single reviewed submission.
Descriptor changes and document updates can close in days. Restructuring a holding entity or switching payment rails is weeks of operational work.
Matching the right adviser to each type of blockage
The right adviser depends on the specific problem: compliance counsel, onboarding specialist, payment consultant, or structural adviser — each covers a distinct part of the fix.
| Blockage type | Adviser | What they deliver |
|---|---|---|
| Weak AML/KYC | Compliance counsel | Policies, procedures, and a standardised compliance pack ready for bank review |
| Poor application narrative | Onboarding specialist | Structured documentation, ownership summaries, clear source-of-funds explanation |
| Chargeback risk or payment flow gaps | Payment consultant | Rebuilt transaction flow, descriptor policy, dispute management process |
| Entity or account structure mismatch | Structural adviser | Aligned corporate structure, separated gaming and operational accounts |
Each measures success differently: compliance counsel by signed policies, onboarding specialist by approval rate, payment consultant by dispute ratio, structural adviser by clean fund separation. No one guarantees approval. If an adviser promises a fast result without first reviewing the licence, markets, and payment history — that's not the right person. A full structural rebuild takes weeks, not days.
Choosing the right banking and payment partner after a rejection
The main options are specialist banks, EMIs, and combined payment platforms built to work with gambling operators.
| Provider type | Sector tolerance | Onboarding speed | Geographic scope | Settlement model | Best fit when… |
|---|---|---|---|---|---|
| Mainstream bank | Low | Slow | Broad | Standard | Rarely viable for gambling |
| Specialist bank | High | Moderate | Selective | Tailored | Licence is strong, volumes are stable |
| EMI | High | Fast | Broad | Rolling reserve | Rapid restart needed post-rejection |
| Payment-platform combination | High | Moderate | Flexible | Split-flow | Complex payout and refund flows |
Select by compatibility, not by brand. An EMI that understands gambling and accepts your licence jurisdiction will deliver more than a mainstream bank that is nominally open to the sector but has no experience handling chargebacks and multi-currency settlements.



















Sign in to leave a comment.