

Small-town India has a strong tradition of saving money within families, neighbourhoods and local communities. Many people prefer financial arrangements that they can understand, access easily and discuss directly with someone they trust. In places where formal banking services may feel complicated or distant, community-based financial organisations can offer an alternative way to save and borrow. This growing interest in member-only lending firms reflects the importance of accessible financial services, personal relationships and local economic needs.
Nidhi companies are one example of this model. They are public companies established to encourage thrift and savings among their members and provide loans to those members under the applicable legal framework. Unlike conventional financial institutions that serve a broad customer base, Nidhi companies operate within a restricted membership structure. This approach can appeal to small traders, salaried employees, shopkeepers and families looking for organised ways to manage savings and meet borrowing needs. However, their activities must comply with the Companies Act, 2013, the Nidhi Rules, 2014, and applicable amendments.
One reason these organisations attract attention is their connection with local communities. In smaller towns, financial decisions are often influenced by personal experience, word-of-mouth recommendations and familiarity with the people managing an institution. A member may feel more comfortable discussing a loan with an organisation that understands local business conditions and household expenses. For small entrepreneurs, access to funds can help manage inventory purchases, repair equipment or meet short-term working capital needs. Nevertheless, familiarity should not replace careful financial assessment, and members should always examine the organisation’s terms before depositing money or borrowing.
Another factor is the demand for disciplined savings. Many households receive income from small businesses, agriculture, daily employment or seasonal activities. Setting aside money regularly can be difficult when expenses vary throughout the year. A structured membership arrangement may encourage people to maintain a savings habit and monitor their contributions. When managed responsibly, this can support better financial planning. Members should still check the permitted deposit terms, interest rates, maturity conditions and withdrawal rules instead of assuming that every scheme offers immediate access to funds.
For entrepreneurs interested in entering this sector, nidhi company registration in india involves more than choosing a name and incorporating a business. A proposed company must meet the applicable incorporation requirements and follow the legal conditions governing Nidhi operations. Depending on the rules applicable to the company, requirements relating to membership, net owned funds, declarations and regulatory filings may also apply. In particular, incorporation should not be confused with government declaration as a Nidhi. Promoters need to verify the current requirements, including Form NDH-4, before beginning or continuing Nidhi activities. This distinction is important because a company cannot assume that its name or incorporation certificate alone authorises every activity associated with a Nidhi.
Technology is also changing how smaller financial organisations communicate with members. Digital payment records, electronic statements and online accounting systems can make transactions easier to track. Members may be able to check deposits and repayments without travelling frequently to an office. At the same time, digital convenience does not automatically establish financial credibility. Organisations must protect member information, maintain accurate records and communicate clearly about transaction charges, repayment schedules and applicable conditions. Members should retain their own receipts and verify account entries regularly.
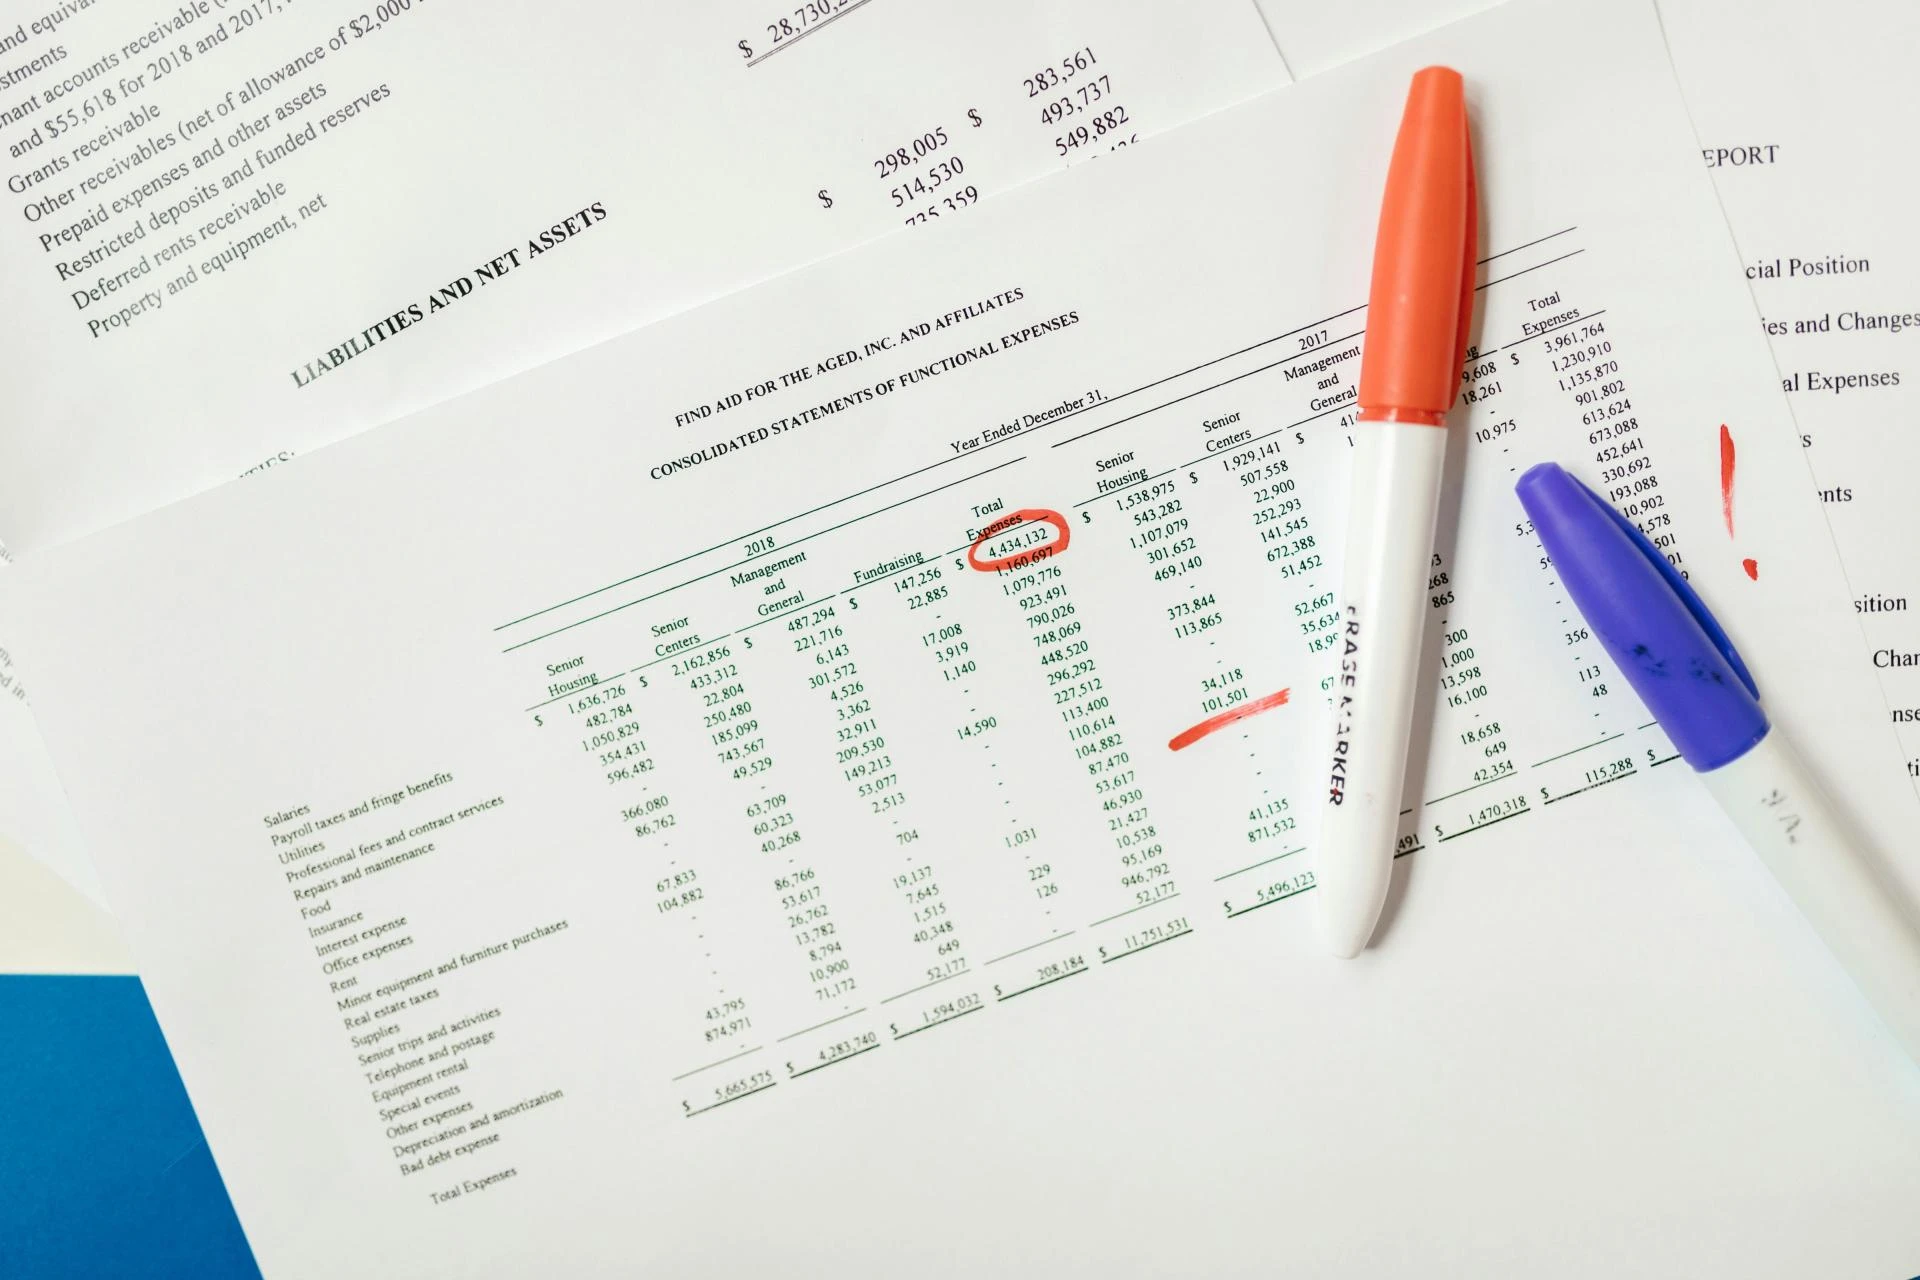
Strong governance is essential as the sector develops. The nidhi company annual compliances include applicable statutory filings, maintenance of records, financial reporting and compliance with Nidhi-specific requirements. These obligations help establish accountability and support the proper functioning of a member-based organisation. Directors and promoters should maintain accurate accounts, monitor lending activities and ensure that members receive clear information about the organisation’s policies. Failure to meet legal requirements can lead to regulatory action and may affect the company’s ability to carry out its activities.
Savers must also recognise the risks associated with depositing money in a Nidhi company. Deposits accepted by Nidhi companies are not insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC). If an organisation fails or fraud occurs, recovering deposited funds may be difficult or incomplete. Members should independently verify whether the company has been declared as a Nidhi by the Central Government, review its terms and avoid relying solely on unusually high-return promises. They should never treat a community reputation as a substitute for regulatory verification.
The rise of member-only lending firms in small towns reflects a continuing need for accessible savings and borrowing options. Their long-term contribution will depend on responsible management, transparent transactions and compliance with applicable laws. When members understand their rights and risks, and promoters prioritise accountability over rapid expansion, these organisations can support local financial participation without encouraging unrealistic expectations. Sustainable growth comes from protecting members’ interests while maintaining the trust on which the mutual-benefit model depends.










Sign in to leave a comment.