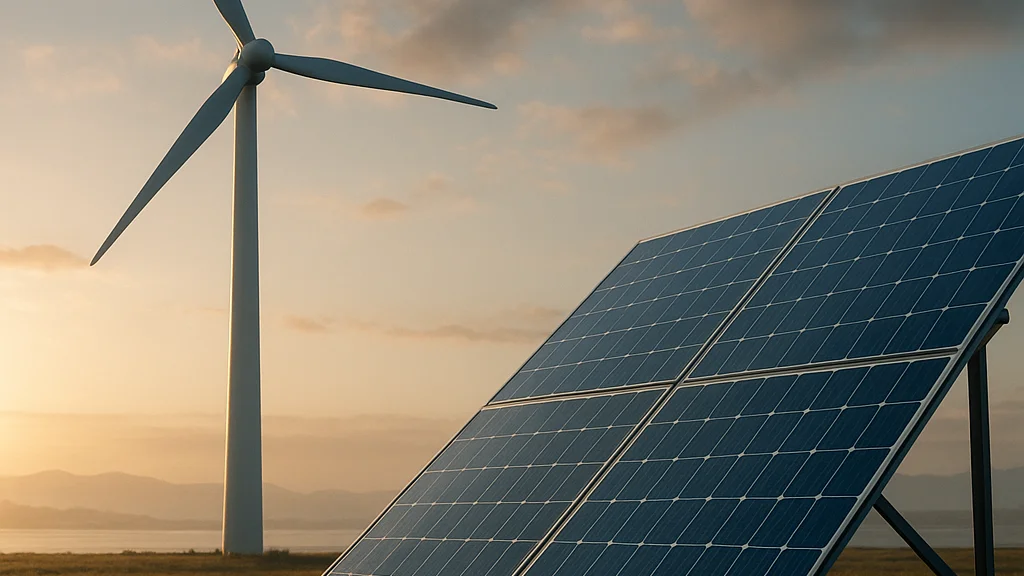
A global buildout that has moved from promise to system-wide force
Stand on a ridge in California at sunrise and the energy transition feels cinematic: utility-scale solar arrays waking up in long geometric rows, transmission lines humming toward coastal cities, batteries waiting for the evening ramp, and offshore wind ambitions inching from policy decks into steel and cable. Yet the bigger story is not local. It is planetary. Wind and solar energy capacity growth worldwide has accelerated to the point where these technologies are no longer niche additions to the grid; they are increasingly the default source of new power generation.
That shift became impossible to ignore after a run of data-heavy milestones in 2025 and 2026. According to pv magazine International, summarizing recent global assessments, solar and wind dominated net power capacity additions in 2025. Separate reporting from MSN and Yahoo highlighted a symbolic threshold: wind and solar overtook gas worldwide for the first time in electricity generation share during a period of geopolitical stress and commodity volatility.
For readers tracking EV adoption, this matters more than it first appears. Electric vehicles only become truly climate-positive at scale when the grid itself cleans up. Every gigawatt of new wind and solar capacity lowers the carbon intensity of charging, softens exposure to fossil fuel price shocks, and changes the economics of transport electrification. If you want a primer before going deeper, WriteUpCafe has a useful overview in Beginner’s Guide to Wind and Solar Energy Capacity Growth. For this piece, though, I want to push beyond the basics and examine what the numbers actually mean, where the bottlenecks now sit, and why 2026 looks less like a continuation of old trends and more like the start of a new operating model for global power systems.
Wind and solar are no longer just expanding; they are beginning to set the pace for how the rest of the power system must adapt.
How the world got here: from subsidy story to industrial scale
A decade ago, most mainstream commentary still treated wind and solar as policy-supported alternatives that needed special pleading. Costs were falling, yes, but integration concerns dominated boardroom conversations. Utilities worried about intermittency, policymakers argued over subsidy design, and investors often preferred gas because it looked dispatchable, familiar, and fast to build. That old framing now feels dated.
The change did not happen because one breakthrough solved everything. It happened because several curves bent at once. Module manufacturing scaled dramatically, especially in Asia. Turbine design improved, with larger rotors and taller towers unlocking better capacity factors onshore while offshore projects matured in Europe and parts of Asia. Grid software improved. Battery storage costs dropped enough to become commercially relevant in more markets. Meanwhile, extreme fossil fuel price swings made supposedly dependable thermal generation look financially fragile.
Policy also matured. Early feed-in tariffs gave way to auctions, corporate power purchase agreements, tax credits, contracts for difference, renewable portfolio standards, and industrial policies aimed at domestic supply chains. The United States added a major catalyst with clean-energy incentives embedded in recent federal legislation, while Europe responded to energy security pressures after the Russia-Ukraine war by accelerating renewable deployment and permitting reform. China, already the giant in manufacturing and installations, continued to build at a pace that reshaped global totals almost by itself.
One reason capacity growth now looks explosive is that solar in particular benefits from short development cycles. A gas plant or nuclear reactor can take years longer to finance and build; a large solar project can move from approval to operation much faster when land, interconnection, and equipment are available. Wind projects tend to be more complex, especially offshore, but they still slot into a decarbonization strategy that values speed. Readers who want a broader companion piece can compare this analysis with How Wind and Solar Energy Capacity Is Expanding Worldwide, which maps the expansion trend in a more introductory format.
- Solar became the fastest-scaling power technology because manufacturing scale and modular deployment reinforced each other.
- Wind remained critical because it often produces at different hours and seasons than solar, improving system balance.
- Batteries and digital grid tools reduced the practical limits of variable renewable integration.
- Energy security concerns turned renewables from a climate option into a strategic asset.
That final point is underrated. Countries do not need to import sunlight or wind. They do need steel, copper, polysilicon, inverters, transformers, and capital—but once projects are built, fuel-price exposure drops sharply. In a world repeatedly jolted by shipping disruptions, sanctions, and regional conflict, that advantage has become central rather than peripheral.
The numbers behind capacity growth worldwide
Capacity is not the same thing as generation, and that distinction matters. A gigawatt of solar does not produce the same annual electricity as a gigawatt of gas or nuclear because output depends on weather, location, and operating profile. Still, capacity growth is the clearest leading indicator of where the power sector is headed. New installations tell us what developers, utilities, regulators, and lenders believe will make economic sense over the next two to three decades.
Recent reporting points in one direction. According to pv magazine International, solar and wind accounted for the overwhelming majority of net global power growth in 2025. That is a profound shift from the years when coal and gas still dominated incremental additions. Reporting carried by Yahoo and MSN, citing the Ember Global Electricity Review, underscored another marker: wind and solar together generated more electricity globally than gas for the first time.
The scale is easier to grasp when broken into a few structural realities.
- Solar is the volume leader. It is generally cheaper and faster to deploy than most alternatives, especially utility-scale projects paired with batteries.
- Wind remains indispensable. Onshore wind still offers some of the lowest-cost bulk power in strong-resource regions, while offshore wind, despite cost turbulence, is strategically valuable for densely populated coastal markets.
- China is the decisive force. Its domestic additions and manufacturing capacity influence global pricing, equipment availability, and annual installation records.
- Emerging markets are now central. India, Brazil, parts of the Middle East, and several African markets are becoming increasingly important demand centers.
There is also a useful caution in the data. As Politifact noted in a 2026 fact-check discussing broader energy claims, wind and solar still account for a relatively modest share of total global primary energy even as they command a much larger and rapidly rising slice of electricity generation. That distinction trips up plenty of public debates. Electricity is only one part of the energy system; transport, heavy industry, shipping, aviation, and heating still contain large fossil fuel loads. But because electricity can decarbonize other sectors through EVs, heat pumps, and green hydrogen, power-sector gains have outsized strategic importance.
Capacity growth is the front edge of a wider economic transition: first the grid gets cleaner, then the machines that run on the grid follow.
Seen through that lens, wind and solar growth is not merely an electricity story. It is the foundation beneath electric mobility, data-center expansion, industrial electrification, and long-term energy independence.
What changed recently: 2026 is about resilience, not just climate math
The most interesting development in 2026 is that the case for wind and solar has broadened. Climate remains the anchor argument, but resilience and affordability are now doing equal work. Energy markets have been repeatedly stressed by geopolitical conflict, supply chain disruptions, and weather extremes. During those moments, renewable generation does not solve every problem, yet it often acts as a stabilizer by reducing the amount of imported fuel a system must buy at elevated prices.
That theme appeared clearly in coverage from The Independent, which reported that solar and wind were helping shield the global economy from the worst energy-price impacts linked to tensions around Iran and the Strait of Hormuz. Even readers who dislike dramatic headlines should take the underlying point seriously: every additional unit of renewable generation lowers exposure to volatile hydrocarbon markets. In practical terms, that means fewer emergency fuel purchases, less inflationary pressure from gas spikes, and lower operating costs for electrified transport.
Meanwhile, 2026 policy conversations have shifted toward second-order problems. The old question was whether renewables could grow. The new question is whether grids, permitting systems, and supply chains can keep up. Interconnection queues are swelling in the United States. Europe is still working through transmission bottlenecks and offshore wind cost resets. China is adding astonishing volumes of capacity but also wrestling with curtailment risk and the need for more flexible system operation. India is pushing hard on solar and storage while trying to expand transmission fast enough to absorb new generation from resource-rich regions.
Three developments stand out this year.
- Utilities are procuring more solar-plus-storage rather than solar alone, especially in markets with steep evening demand ramps.
- Governments are focusing more aggressively on transmission corridors, grid modernization, and faster permitting.
- Industrial policy is expanding beyond generation into domestic manufacturing of modules, cells, inverters, transformers, cables, and batteries.
That industrial angle matters for clean transport too. EV factories, battery plants, and data centers are all electricity-hungry loads. Regions that can add clean power quickly become magnets for investment. Silicon Valley has understood this for years in the abstract; now the rest of the economy is learning it in spreadsheets. The consequence is subtle but powerful: wind and solar capacity growth is becoming a competitiveness issue, not just an environmental one.
Regional leaders and why their trajectories differ
Global totals can obscure the fact that wind and solar growth follows very different regional logics. China remains the headline leader, but its dominance is not simply a function of climate ambition. It combines industrial strategy, massive domestic demand, state-backed infrastructure planning, and a manufacturing ecosystem that can produce at extraordinary scale. When China accelerates, global module prices, equipment inventories, and annual installation records all move with it.
The United States tells a different story. It has world-class renewable resources, deep capital markets, and major tax incentives, but growth is filtered through fragmented permitting, local opposition in some regions, and transmission constraints that can delay projects even when economics are attractive. Still, the long-term direction is clear. Solar continues to expand rapidly, and battery pairings are increasingly standard in high-penetration markets. Offshore wind has faced setbacks, yet state procurement targets and federal lease activity keep the sector strategically alive.
Europe is balancing urgency with complexity. The continent has leaned heavily into wind, especially offshore, and accelerated solar after the gas shock triggered by Russia's invasion of Ukraine. But cost inflation, higher interest rates in the recent past, and supply chain pressures complicated project economics. Even so, Europe remains a policy laboratory for market design, flexibility services, and cross-border integration.
Then there are the emerging leaders. India is perhaps the most consequential after China because its electricity demand is rising fast and its policy choices will shape global emissions trajectories. Brazil has become a standout in both wind and solar, supported by strong resources and competitive project economics. Gulf states are scaling large solar parks as part of diversification strategies. Across Africa, progress is uneven but increasingly important, especially where distributed solar can leapfrog weak grid infrastructure.
For a leader-focused companion read, WriteUpCafe's Top 5 Wind and Solar Energy Capacity Growth Leaders offers a country-by-country snapshot. The bigger analytical takeaway is this: there is no single template. Some markets are driven by industrial policy, others by import dependence, others by land economics, and still others by pure demand growth. What unites them is that wind and solar are now central to capacity planning almost everywhere.
The constraints that could slow the boom
Anyone claiming the growth path is frictionless is selling a fantasy. Wind and solar energy capacity growth worldwide is robust, but the limiting factors are increasingly physical and institutional rather than ideological. The first is transmission. Generation can be built far faster than new long-distance lines, especially in democracies where siting disputes, environmental review, and fragmented jurisdictions stretch timelines. A solar farm that cannot connect on time is not a climate solution; it is stranded capital.
The second bottleneck is grid flexibility. As solar penetration rises, midday prices can collapse while evening demand remains high. That creates the famous duck curve problem in places like California, but versions of it are appearing elsewhere too. Batteries help. Demand response helps. Flexible industrial loads help. Better regional interconnection helps most of all. Yet these solutions require market reforms, software investment, and utility planning that are often slower than the pace of renewable deployment.
Third comes supply chain concentration. Solar manufacturing remains heavily centered in China, and while that has lowered costs globally, it has also increased geopolitical sensitivity. The same concern applies to certain critical minerals and grid components. Western governments are trying to diversify, but domestic manufacturing scale takes time. Offshore wind has its own supply chain headaches, from specialized vessels to turbine component bottlenecks.
Then there is social license. Onshore wind can face local opposition over viewsheds, noise concerns, and land use. Utility-scale solar can trigger debates over farmland, habitat, and community benefit-sharing. The lesson from successful markets is not to bulldoze concerns but to structure better compensation, clearer timelines, and smarter siting rules.
- Transmission delays can hold back otherwise economic projects for years.
- Interconnection queues create uncertainty that raises financing costs.
- Flexible capacity, especially batteries, must scale alongside solar.
- Permitting reform is now as important as generation incentives.
- Supply chain diversification will shape pricing and energy security through the late 2020s.
These are solvable problems, but they are not minor. The energy transition has entered the infrastructure phase, where success depends less on proving the technologies work and more on building the connective tissue that lets them work together at continental scale.
Why this matters for EVs, industry, and the next decade of electrification
From my corner of the Bay Area clean-tech world, the most exciting part of this story is the feedback loop between renewable power and electrified demand. EV adoption increases electricity consumption, but it also creates flexible load opportunities through smart charging and, eventually, wider vehicle-to-grid participation. More solar on the grid makes midday charging cheaper. More wind can support overnight charging in strong-resource regions. Batteries smooth the rough edges. The result is not just lower emissions; it is a more dynamic and software-defined energy system.
Data centers add another twist. AI infrastructure is driving huge electricity demand growth in several markets, and developers increasingly want clean power contracts to meet corporate targets and manage long-term cost risk. That pressure can accelerate renewable procurement, but it can also intensify competition for transmission access and grid upgrades. Heavy industry, meanwhile, is beginning to explore electrification pathways that only make sense if low-cost clean power is abundant.
This is why the distinction between capacity growth and system transformation matters. Adding gigawatts is necessary, but the real prize is abundant clean electricity that changes what the economy can electrify next. Heat pumps replace gas furnaces. Electric trucks become more compelling. Green hydrogen projects find better economics in select locations. Ports and warehouses reduce diesel dependence. The power sector becomes the platform layer for decarbonizing everything else.
Readers looking for a broader reference can also consult Complete Guide to Wind and Solar Energy Capacity Growth, which complements this analysis with a wider survey of technologies and market structures. My own view is straightforward: the countries and regions that solve renewable integration fastest will capture the next wave of manufacturing, software, and mobility investment.
The future of clean transport does not arrive only through better vehicles; it arrives through cleaner, cheaper, and more reliable electrons.
That is the hidden headline inside all these capacity charts. Wind and solar are not merely replacing legacy generation at the margins. They are setting the terms for the next industrial cycle.
What to watch next
Over the next few years, the most revealing metrics will not be annual installation headlines alone. Watch curtailment rates, transmission approvals, battery deployment, interconnection wait times, and the spread of time-of-use pricing that nudges demand into periods of abundant renewable output. If those indicators improve, the current growth story could compound into something even larger: an era of structurally cheaper electricity in many regions.
There are also strategic questions hanging over 2027 and beyond. Will offshore wind regain cost momentum after the recent turbulence? Can emerging markets secure affordable finance at the scale needed to avoid locking in new fossil infrastructure? Will domestic manufacturing efforts in the United States, Europe, and India become durable enough to diversify supply chains without sharply raising costs? And can policymakers move faster on transmission, the least glamorous but most decisive piece of the puzzle?
My expectation is that solar will remain the volume champion, batteries will become standard companions in more markets, and wind will continue to matter most where seasonal and nighttime generation balance solar-heavy systems. The strongest grids will be those that combine all three with smarter demand management. That future is already visible in fragments from California to China to the North Sea. The challenge now is stitching those fragments into coherent national and regional systems.
Wind and solar energy capacity growth worldwide has passed a threshold. The question is no longer whether these technologies can scale. They already have. The question is whether institutions can scale with them—fast enough to unlock cheaper power, cleaner transport, and a less fragile global energy economy. For anyone who cares about EVs, climate, industrial competitiveness, or just avoiding the next fuel-price shock, that is the story to watch.








Sign in to leave a comment.