
The Bionic Quadruped Revolution: Navigating Market Dynamics and Strategic Opportunities
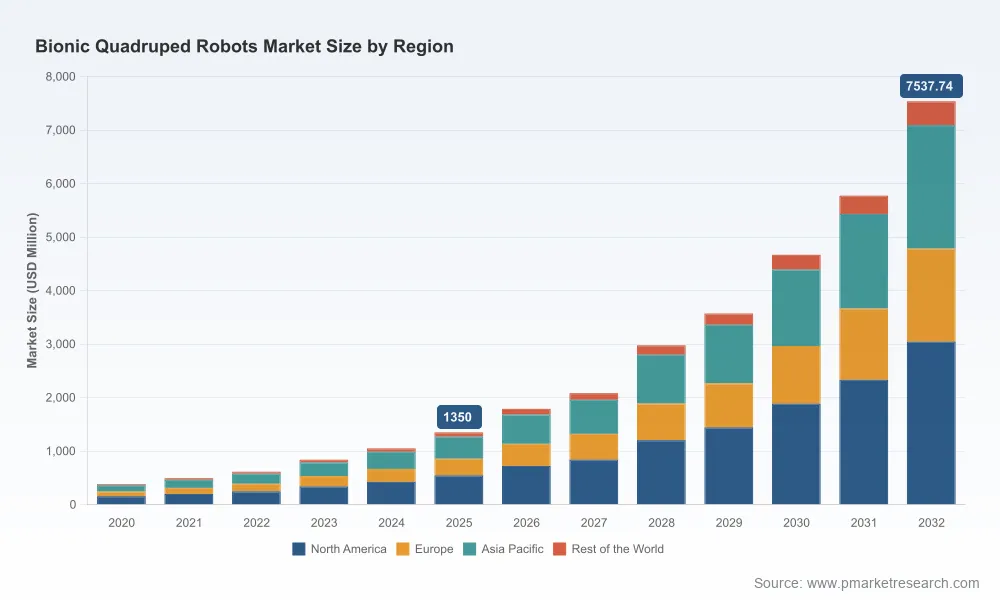
The global market for bionic quadruped robots has transitioned from experimental prototypes to commercially viable assets at an unprecedented pace. Valued at approximately 385.4 million USD in 2020, the sector surged to 1.35 billion USD by 2025, reflecting a compound annual growth rate of 27.85 percent through the forecast period ending in 2032. This trajectory underscores a fundamental shift in how industries perceive legged automation: no longer niche curiosities, but essential tools for navigating unstructured environments where wheeled or tracked systems fail. The market is projected to expand significantly over the coming years, driven by broader adoption across critical sectors and continuous technological maturation.
Despite this momentum, the industry stands at a critical juncture. The rapid expansion masks underlying complexities that vendors and adopters must navigate carefully. The proliferation of platforms has outpaced the development of unified safety protocols, creating a fragmented landscape where performance benchmarks vary widely. Furthermore, the high cost of advanced actuation systems and sensor suites continues to constrain deployment in cost-sensitive applications, even as economies of scale begin to emerge. Companies are also grappling with the challenge of moving beyond pilot programs to full-scale operational integration, where reliability and total cost of ownership become decisive factors.
The concentration of market value among a select group of established players highlights the competitive intensity. A handful of organizations command a significant share of revenue, leveraging deep engineering expertise and early-mover advantages in specific verticals. However, the barrier to entry is lowering in certain segments, particularly where software capabilities and AI-driven autonomy are becoming more accessible. This dynamic creates both pressure on incumbents to defend their positions and opportunities for new entrants to carve out niches through specialized applications or regional manufacturing strategies. Understanding these structural forces is essential for stakeholders aiming to capitalize on the bionic quadruped wave without falling prey to hype-driven missteps.
Key Drivers Shaping the Bionic Quadruped Landscape
Technological Innovation and Autonomy Breakthroughs
At the core of market expansion lies a rapid acceleration in hardware and software capabilities. Advanced actuation systems, combining hydraulic and electric technologies, are enabling robots to achieve dynamic stability and terrain adaptability previously thought difficult to commercialize. High-performance sensors, including LiDAR, inertial measurement units, and multi-spectral cameras, provide the perception layer necessary for autonomous navigation in complex, unstructured environments. These components are converging with sophisticated control algorithms that allow quadrupeds to recover from slips, adjust gait in real time, and operate with minimal human intervention. The result is a shift from teleoperated machines to semi-autonomous or fully autonomous agents capable of executing repetitive inspection, monitoring, and data collection tasks with increasing reliability. The integration of embodied AI further enhances these platforms, enabling them to interpret contextual cues and adapt behavior without explicit programming for every scenario.
Polymeric Aluminum Ferric Sulfate Market
Recent product launches and demonstrations illustrate the pace of this evolution. In early 2026, Faraday Future introduced the FX Aegis professional quadruped EAI robot, targeting security and companionship applications and marking one of the first deliveries of a quadruped platform by a US-based company. This move signals the expansion of the addressable market beyond traditional industrial use cases into public-facing and service-oriented domains. Simultaneously, AMC Robotics showcased its AI-powered Kyro quadruped for autonomous security at an international exhibition, emphasizing the growing focus on integrated intelligent decision-making rather than mere locomotion. These developments reflect a broader trend where software differentiation is becoming as critical as mechanical design, and where the ability to process environmental data in real time determines commercial viability.
Regulatory Evolution and Standardization
The regulatory environment is undergoing a significant transformation that directly impacts deployment confidence and market scalability. The development of ISO 25785-1 represents a milestone as the first international safety standard specifically addressing dynamically stable industrial mobile robots, including quadrupeds. This standard addresses balance performance, fall-zone formulas, and legged locomotion hazards, providing a much-needed framework for risk assessment and operational safety. As these standards move toward formal adoption, they will likely reduce the uncertainty that has historically slowed procurement decisions, particularly in regulated industries such as oil and gas, chemical processing, and public infrastructure. The ISO 25785-1 standard and related updates will also help harmonize testing protocols, making it easier for buyers to compare platforms and for manufacturers to validate compliance across multiple jurisdictions.
Parallel updates to existing industrial robot standards, including revisions emphasizing application-based risk assessment, functional safety, and lifecycle documentation, now explicitly support the integration of mobile platforms such as legged systems. This alignment reduces the regulatory friction that once isolated quadruped robots from broader automation ecosystems. Meanwhile, the EU AI Act classifies certain high-risk AI systems, including robots operating in public spaces, healthcare, and workplaces, mandating conformity assessment, transparency, and human oversight mechanisms. For quadruped vendors, this means that autonomy features must be designed with compliance in mind from the outset, influencing architecture choices and data handling practices. Companies that proactively embed these requirements into their development cycles will gain a competitive advantage as certification becomes a prerequisite for market access in key regions.
Demand-Side Shifts and Operational Economics
End-user demand is being reshaped by the need to reduce operational risk, improve data quality, and address labor constraints in hazardous or inaccessible environments. Industries such as industrial inspection and maintenance, defense and public safety, research and education, and construction and mining are increasingly turning to quadruped robots to perform tasks that expose human workers to danger or require persistent monitoring. The value proposition extends beyond safety; organizations are recognizing that autonomous data collection can yield higher frequency, more consistent, and richer datasets than periodic manual inspections. This shift is driving procurement strategies toward platforms that offer not just mobility, but integrated sensing, analytics, and seamless integration with existing asset management or security workflows. As operators move from proof-of-concept trials to sustained deployments, the focus is shifting toward total cost of ownership, uptime guarantees, and the ability to scale fleets without proportional increases in operator headcount.
Supply Chain Dynamics and Cost Structure Pressures
The supply chain for bionic quadruped robots remains influenced by the availability and cost of critical components. Advanced actuation systems and high-performance sensor suites represent key hardware bottlenecks, and fluctuations in raw material prices or semiconductor availability can impact production timelines and margin structures. In response, manufacturers are pursuing multiple strategies to mitigate these pressures. Some are verticalizing production by establishing regional manufacturing subsidiaries to enhance scalability and reduce logistical friction. For example, AMC Robotics established a wholly owned subsidiary in Vietnam to expand manufacturing capacity for its Kyro quadruped, reflecting a broader trend toward distributed production models that balance cost efficiency with supply chain resilience. Others are focusing on modular architectures that allow incremental upgrades and lower entry-level costs, making platforms accessible to a wider range of users while preserving upgrade paths for advanced applications. As component costs gradually decline and manufacturing processes mature, the cost structure of bionic quadrupeds is expected to improve, enabling broader adoption and more aggressive pricing strategies in competitive segments.
PW Consulting
Competitive Landscape and Strategic Positioning
The competitive arena for bionic quadruped robots is characterized by a mix of established pioneers, agile regional players, and cross-industry entrants, each pursuing distinct strategic positioning. Boston Dynamics continues to leverage its Spot platform for industrial inspection, security, and remote monitoring in complex environments, benefiting from extensive field validation and strong brand recognition tied to advanced mobility and payload flexibility. Its approach emphasizes reliability, ecosystem partnerships, and gradual expansion into new application domains. Unitree Robotics, based in Hangzhou, has gained traction by producing affordable high-performance bionic quadrupeds, including the Go2 and B2 series, for consumer, industrial, and research uses, with strong global shipment volumes. This strategy focuses on democratizing access to capable hardware, making quadruped platforms viable for a broader customer base and fostering community-driven development and integration.
Gas Detectors Market
ANYbotics differentiates itself through a focus on industrial inspection in hazardous and explosive environments, with the ANYmal X platform designed to meet advanced certification requirements. This specialization positions the company strongly in sectors where safety compliance and operational resilience are non-negotiable, appealing to buyers in oil, gas, and chemical industries who prioritize verified robustness over general-purpose features. Deep Robotics manufactures bionic quadrupeds such as the Lite 3, LYNX M20, and X30 series, targeting industrial inspection, power station operations, and hazardous terrain navigation. Its portfolio reflects a dual emphasis on versatility and ruggedness, serving both routine inspection cycles and demanding operational contexts. Ghost Robotics specializes in the Vision 60 quadruped for defense, security, and industrial applications, incorporating manipulator capabilities that extend functionality beyond mobility and sensing into active task execution. This positioning aligns with defense and public safety customers seeking platforms that can carry out physical interventions as well as surveillance.
The market is also attracting new entrants and adjacent players seeking to leverage embodied AI and automation trends. Faraday Future's entry with the FX Aegis robot for security and companionship illustrates how companies outside traditional robotics are expanding into quadruped platforms, often with a strong emphasis on AI integration and user experience. AMC Robotics is building momentum through AI-powered autonomous security applications and strategic manufacturing expansion, including a Vietnam-based subsidiary aimed at scaling production. These moves highlight a trend where geographic diversification and production scalability are becoming competitive differentiators, particularly for companies seeking to serve global demand while managing cost and supply chain risks. The competitive landscape is likely to see further consolidation as larger players acquire niche capabilities, while specialized firms may flourish by dominating particular verticals or regional markets. Buyers should evaluate not only current feature sets but also each vendor's roadmap, certification trajectory, and ability to support long-term fleet scaling and integration needs.
Future Trends and Strategic Horizons
Looking ahead, the bionic quadruped market is likely to be shaped by several converging trends that will redefine value creation and competitive dynamics. First, the integration of embodied AI and edge-based autonomy will accelerate, moving platforms from structured, pre-mapped operations toward adaptive decision-making in dynamic environments. As algorithms improve and on-device compute becomes more efficient, quadrupeds will handle increasingly complex tasks such as multi-modal inspection, anomaly detection, and context-aware navigation without continuous human oversight. This trend expands the addressable use cases and raises the strategic importance of software stacks, data pipelines, and model update mechanisms. Second, standardization and regulatory clarity will mature, lowering adoption friction and enabling broader deployment in safety-critical sectors. As ISO standards for dynamic stability, locomotion performance, and risk assessment gain traction, and as frameworks like the EU AI Act take full effect, vendors that have built compliance into their design processes will enjoy faster time-to-market and stronger customer trust. This shift will also raise the bar for new entrants, making certification and documentation capabilities a meaningful competitive moat.
Third, manufacturing strategies will increasingly emphasize regionalization and modular hardware architectures to balance cost, resilience, and customization. Expect more companies to establish production footprints close to key demand centers, reducing lead times and currency exposure while enabling localized support and faster iteration. Modular designs will allow customers to start with base platforms and add sensors, manipulator arms, or specialized payloads as needs evolve, improving capital efficiency and extending platform lifecycles. These trends create clear commercial opportunities: software and integration providers can position themselves as enablers of autonomy and analytics; component suppliers with differentiated actuation or sensor technologies can capture premium value; and end-users that invest early in data infrastructure and workforce training will realize faster returns from fleet deployments. At the same time, uncertainties remain. Supply chain disruptions for critical components, evolving regulatory interpretations, and the risk of overpromising on autonomy capabilities could slow adoption if not managed carefully. Organizations should therefore pursue phased deployment strategies, validate performance against clear operational metrics, and maintain flexibility in vendor selection and technology roadmaps.
Actionable Insights for Decision Makers
For manufacturers, the priority is to align product development with the dual imperatives of performance differentiation and regulatory readiness. Investing in modular hardware, robust safety certifications, and AI-driven autonomy that can be updated over the air will position platforms for longer lifecycles and broader adoption. Companies should also evaluate supply chain diversification and regional manufacturing options to mitigate component bottlenecks and respond faster to localized demand. For investors, due diligence should extend beyond headline specifications to examine certification roadmaps, total cost of ownership profiles, and the strength of integration ecosystems. Platforms that demonstrate repeatable deployment metrics, clear compliance pathways, and scalable support structures are more likely to sustain growth as the market matures and procurement standards tighten. For procurement and operations leaders, pilot programs should be designed with measurable KPIs tied to safety, data quality, uptime, and labor reallocation, rather than technology demonstration alone. Early engagement with vendors on data integration, fleet management, and training requirements will reduce friction during scale-up and improve return on investment. In all cases, timely access to granular market intelligence, including detailed segmentation, regional demand patterns, and vendor benchmarking, can sharpen strategy and accelerate execution. Comprehensive research reports provide the depth needed to navigate this rapidly evolving landscape with confidence, offering customized perspectives for specific industries and strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Bionic Quadruped Robots Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com
























Sign in to leave a comment.