
Navigating the Xylene Sulfonic Acid Market: Strategic Trends and Commercial Opportunities
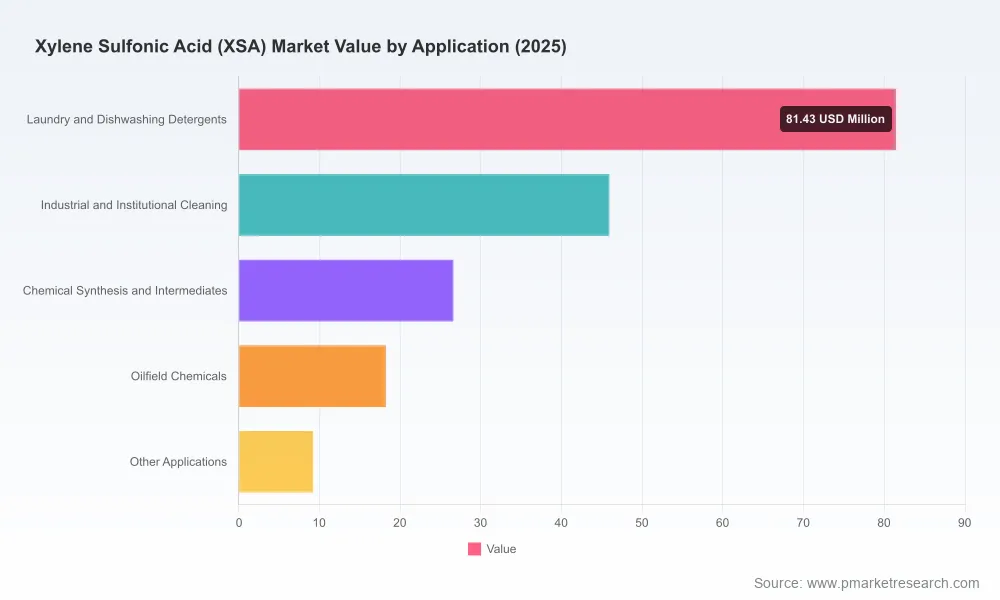
The global xylene sulfonic acid (XSA) market has transitioned from a mature, commodity-driven landscape into a sector defined by formulation innovation, regulatory clarity, and shifting end-use dynamics. Valued at approximately 142.1 million USD in 2020, the market reached 181.37 million USD by 2025, reflecting a compound annual growth rate of 5.02 percent through the forecast horizon extending to 2032. This trajectory signals steady expansion rather than explosive disruption, positioning XSA as a reliable enabling ingredient across cleaning, chemical synthesis, and specialty industrial applications. Yet steady growth masks underlying structural shifts that strategists and operators must decode to capture value. The market’s evolution is no longer dictated solely by volume demand; it is increasingly shaped by supply chain resilience, formulation efficiency, and the regulatory environment that governs hydrotrope and coupling agent usage. Understanding these forces requires looking beyond headline figures and examining how product architectures, regional manufacturing footprints, and input cost volatility interact to create distinct commercial pathways.
Structural Expansion Meets Emerging Friction Points
The XSA market’s baseline growth reflects its entrenched role as a solubilizing and wetting agent in formulations that require stable performance across variable water hardness, pH ranges, and temperature conditions. Demand has broadened as manufacturers seek ingredients that improve viscosity control, enhance active ingredient dispersion, and support cleaner label profiles. This functional versatility explains why the market continues to scale even as end-use categories compete for margin and formulation real estate. However, three structural challenges are reshaping how participants position themselves and allocate capital.
The first challenge is the interplay between raw material cost volatility and margin preservation. XSA production ties directly to xylene and sulfuric acid markets, both of which have experienced notable price swings driven by crude oil dynamics, fertilizer demand, and regional capacity constraints. When input costs rise sharply, manufacturers face a choice: absorb compressed margins, pass costs downstream through price adjustments, or reformulate to reduce dosage intensity. The ability to navigate this triad without disrupting customer relationships or formulation performance has become a core competitive differentiator.
The second challenge lies in balancing performance requirements with formulation modernization. End-users increasingly prioritize ingredients that support concentrated products, reduce packaging waste, and maintain efficacy with fewer auxiliary components. This shift pressures suppliers to deliver higher-active or more consistent formulations that enable dosage reduction while preserving hydrotropic and coupling functionality. Companies that treat XSA purely as a volume ingredient risk losing relevance as formulators seek solutions that contribute to broader product architecture goals.
The third challenge is regulatory visibility and compliance infrastructure. XSA benefits from a comparatively stable regulatory posture that recognizes its role as a processing aid and formulation component, but this status does not eliminate the need for rigorous documentation, supply chain transparency, and proactive registration management. Markets with mature chemical governance frameworks increasingly reward suppliers that can demonstrate traceable production practices, consistent quality control, and clear stewardship pathways. In this environment, compliance becomes a commercial asset rather than a back-office obligation.
Innovation, Policy, and Demand Dynamics Reshaping Value Creation
Several converging forces are driving how the XSA market evolves, and each carries distinct implications for product strategy and commercial positioning.
Worldwide 2,4-Xylenesulfonic Acid Market
Technological innovation centers on formulation efficiency and consistency. Higher-active liquid and powder architectures, improved stabilization profiles, and tighter batch-to-batch control enable customers to achieve target performance with lower additive loads. This matters because hydrotrope and coupling applications often compete for formulation space against surfactants, chelants, and solvents. Suppliers that offer predictable rheology support, clearer solubility curves, and application-specific guidance help formulators reduce trial-and-error cycles and accelerate time-to-market. The strategic implication is clear: value capture increasingly depends on how well a product integrates into customer development workflows rather than on volume alone.
PW Consulting
The policy and regulatory environment continues to shape regional accessibility and procurement confidence. In markets with established chemical frameworks, XSA maintains recognition that supports continued use in detergent and cleaning formulations, including as a processing aid. This regulatory clarity reduces uncertainty for manufacturers and encourages long-term formulation commitments. At the same time, regions with evolving chemical management systems may experience delayed adoption or increased documentation requirements until registration and stewardship expectations stabilize. Suppliers that invest early in compliance readiness and transparent reporting gain a smoother path to market entry and stronger customer trust.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Demand-side behavior reflects a broader shift toward concentrated, efficient, and application-flexible cleaning and industrial processes. Consumers and institutional buyers are drawn to products that deliver performance with reduced water content, smaller packaging footprints, and streamlined ingredient lists. For B2B users, the emphasis is on reliability, dosing precision, and compatibility with automated or high-throughput cleaning systems. These preferences favor XSA offerings that enable formulation compactness and stable performance across operating conditions. Companies that align their product narrative with these outcome-oriented goals can position XSA not simply as a raw material but as a formulation enabler that supports broader sustainability and efficiency objectives.
Supply chain and cost structure changes add another layer of strategic complexity. Regional capacity imbalances, logistics constraints, and feedstock price movements influence where and how XSA is produced and distributed. Participants with flexible manufacturing footprints, diversified sourcing strategies, and responsive inventory management can better absorb shocks and maintain service levels. Conversely, operations overly dependent on narrow feedstock channels or single-region logistics face greater exposure when commodity markets shift. The commercial opportunity lies in designing supply strategies that prioritize reliability, visibility, and scenario planning, especially for customers who view supply continuity as a non-negotiable requirement.
Competitive Architecture and Differentiation Pathways
The competitive landscape reflects a mix of established producers with strong application focus and regional manufacturers that compete on specificity, quality consistency, and customer support. Firms such as Pilot Chemical Company and Enaspol a.s. illustrate how suppliers are building defensible positions through product architecture and formulation alignment rather than competing solely on price.
Pilot Chemical Company’s emphasis on an aqueous solution architecture designed for household, industrial, and institutional cleaning applications highlights a market approach centered on ready-to-use performance and integration ease. By offering a product that functions as a hydrotrope in diverse cleaning formulations, the company aligns its offering with customers who value formulation stability, predictable handling, and broad application compatibility. This positioning reduces reformulation friction and supports faster adoption in markets where cleaning performance and consistency are paramount.
Enaspol a.s. demonstrates a complementary differentiation path by focusing on a higher-active solution that serves as both a hydrotrope and a coupling agent. This product orientation appeals to formulators seeking stronger functional contribution per unit, which can support dosage optimization and more compact formulations. The strategic advantage here is not merely concentration; it is the ability to provide a product that performs across multiple formulation roles while helping customers manage ingredient lists and performance trade-offs.
Together, these examples illustrate a broader industry trend: differentiation is increasingly defined by how well a supplier’s offering fits into the customer’s formulation process, performance targets, and operational constraints. Price competition remains present, but sustained advantage tends to come from application expertise, technical support, quality reliability, and alignment with end-use requirements. The market is not fragmenting into purely commodity and premium tiers so much as it is stratifying around use-case fit and service intensity. Suppliers that invest in technical guidance, consistent specification management, and responsive customer engagement are better positioned to command preference even when input costs fluctuate.
At the same time, the market structure suggests room for selective consolidation and targeted new entry. Mature regional players may pursue partnerships, distribution expansions, or production optimization to strengthen reach and cost efficiency. New entrants, if they enter, are more likely to succeed by focusing on niche application needs, specific regional demand pockets, or differentiated product attributes rather than attempting to compete broadly on scale alone. The evolution of the landscape will likely favor participants that treat XSA as part of a broader formulation-support ecosystem rather than as an isolated chemical transaction.
Forward Outlook: Three Trends Defining the Next Phase
Looking ahead to the medium term, several trends are likely to shape how value is created and captured in the XSA market.
The first trend is formulation-centric competition. As cleaning and industrial applications continue to seek concentration, efficiency, and performance stability, suppliers will be evaluated not only on active content but on how effectively their product enables downstream goals. This includes solubility behavior, compatibility with surfactants and other actives, stability across storage conditions, and ease of integration into manufacturing lines. Companies that provide robust technical documentation, application recommendations, and consistent specification performance will gain preference in procurement decisions, especially where formulation cycle time and reliability matter.
The second trend is regional supply chain realignment. Input cost volatility, logistics complexity, and demand distribution will continue to influence where production and inventory are positioned. Participants that can balance regional responsiveness with cost discipline will be better equipped to serve customers who require dependable delivery and predictable pricing. In practice, this may mean dual-sourcing strategies, localized inventory buffers for critical markets, and closer coordination between production planning and customer demand signals. The strategic value lies in reducing uncertainty for buyers while preserving operational flexibility for suppliers.
The third trend is regulatory and stewardship maturity as a commercial lever. Markets with clear chemical governance frameworks will continue to reward transparency, documentation quality, and proactive compliance practices. Even where restrictions are minimal, customers increasingly expect suppliers to support their own sustainability, safety, and reporting objectives. This creates an opportunity for suppliers to differentiate through stewardship messaging, supply chain traceability, and consistent quality assurance. Over time, these attributes can become part of the purchasing rationale, particularly for larger buyers and multinational formulators that must satisfy internal and external audit expectations.
Each trend carries opportunity, but also risk. Formulation-centric competition can raise the bar for technical capability and customer support, penalizing suppliers that rely on passive sales models. Regional realignment may create short-term cost advantages in some markets while exposing others to tighter margins or longer lead times. Regulatory stewardship can strengthen trust, but it also requires ongoing investment in documentation, quality systems, and communication. Companies that anticipate these dynamics and build capabilities early are more likely to convert market growth into durable commercial advantage.
Actionable Pathways for Decision Makers
For manufacturers and formulators, the priority is to treat XSA selection as a formulation decision with broader operational consequences. Evaluate products based on how they support dosage efficiency, stability, and integration into target applications rather than focusing narrowly on unit price. Where possible, pilot higher-active or application-tailored offerings to determine whether they enable formulation simplification or performance gains that justify the transition. Strengthening technical dialogue with suppliers can also reduce development friction and improve long-term reliability.
For investors and corporate developers, the market warrants attention as a steady-growth specialty ingredient space with differentiation potential rather than a high-volatility commodity play. The most compelling opportunities typically lie with operators that combine consistent quality, application support, and supply chain resilience. Monitoring input cost trends, regional capacity shifts, and regulatory developments can help identify where competitive advantages are likely to widen or compress. Assessing whether a target company’s product portfolio aligns with end-use efficiency trends and whether its commercial model supports technical engagement can provide a clearer view of long-term positioning than headline revenue growth alone.
For procurement and supply chain leaders, the strategic focus should be on continuity, specification consistency, and total cost of ownership. Price fluctuations in feedstocks can create tempting short-term sourcing shifts, but those shifts must be weighed against qualification risk, quality variability, and service reliability. Building supplier relationships that include clear performance expectations, documentation support, and contingency planning can reduce exposure when markets tighten. Where feasible, diversifying sources while maintaining strict specification controls can balance resilience with cost discipline.
The XSA market is not defined by sudden disruption; it is defined by how effectively participants translate functional utility into formulation advantage, supply reliability, and regulatory confidence. The organizations that capture the most value will be those that align product strategy with end-use outcomes, invest in technical and compliance readiness, and treat supply chain resilience as part of the commercial proposition. For decision makers seeking to move from broad market awareness to actionable detail, comprehensive market intelligence can provide the granular segmentation, cost-structure context, and competitive benchmarking needed to sharpen planning and prioritize investments.
For detailed analysis of this topic, please visit the official page: Worldwide Xylene Sulfonic Acid (XSA) Market
Lacy Lee
Senior Marketing Manager
[email protected]
PW Consulting: www.pmarketresearch.com




















Sign in to leave a comment.